Home Is Where The Argument Starts
Your brother wants the family house, but he also wants a family discount. You expected to share its value. In the US, your rights depend on ownership, estate documents, state law, and timing.
 LightField Studios, Shutterstock Images
First, Are Your Parents Still Alive?
If your parents are alive and legally own the house, the decision generally belongs to them. They can generally choose their buyer and price, even if their children expected an inheritance. Your expectations don't create ownership rights.
An Expected Inheritance Isn't Ownership
Being named in a will isn't the same as appearing on a deed. A will concerns property left at death, not a present-day stake in someone's home. A promised future inheritance is not the same as shared ownership now. That distinction is crucial before you demand a vote.
And A Will Can Change
A parent with the necessary legal capacity can generally revise a revocable will. If a specifically promised house is sold during the owner's lifetime, that gift may no longer exist. An inheritance conversation isn't a guarantee.
Start With The Deed
The title documents show who legally owns the property. Your parents, one surviving parent, a trust, or someone else might appear there. Identify the actual owner before discussing a buyout, and review any restrictions recorded against the title.
Survivorship Can Change Everything
A jointly owned home with a right of survivorship may pass directly to the surviving owner, outside the deceased owner's will. The house might therefore be unavailable for immediate inheritance by the children.
No Will Doesn't Automatically Mean Half
When someone dies without a valid will, state intestacy rules determine who inherits. A surviving spouse and other relatives can affect the calculation. Don't assume two siblings receive equal halves, especially if a surviving spouse has inheritance rights.
Power Of Attorney Isn't A Blank Check
If your brother is acting for a living parent under financial power of attorney, different safeguards apply. Agents must prioritize the parent's interests and keep records. Buying their home cheaply for himself deserves independent scrutiny.
 Amnaj Khetsamtip, Shutterstock
A Trust Adds Another Layer
If the property belongs to a trust, its terms and the trustee's responsibilities matter. Trustees must consider beneficiaries' interests and avoid improper self-dealing. Check the trust's terms for a family purchase.
Probate Brings New Rules
After an owner dies, probate may involve collecting assets, resolving debts, and distributing what remains. The executor or court-appointed personal representative generally administers the estate. Beneficiaries aren't necessarily immediate co-owners of each asset.
The Executor Doesn't Get A Free House
Managing an estate doesn't mean personally owning everything inside it. Executors must follow the governing will and their fiduciary responsibilities. If your brother is the executor, that title alone doesn't entitle him to choose a bargain price for himself.
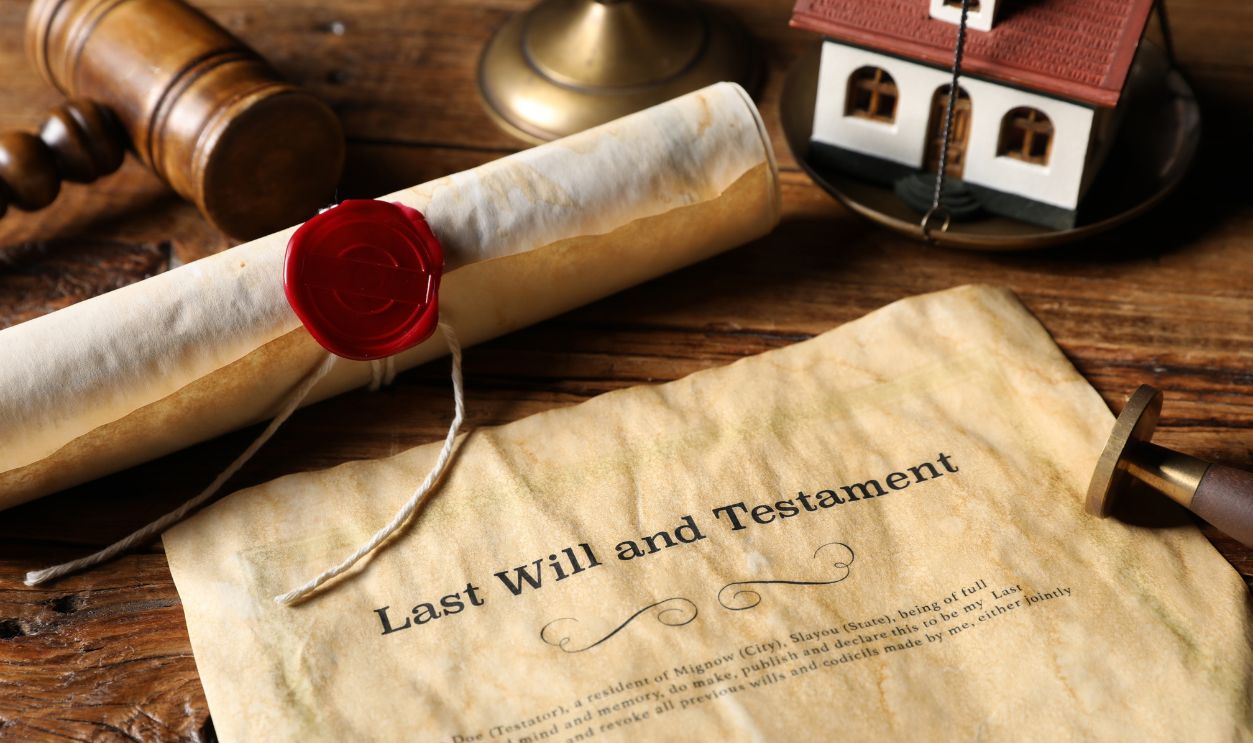
But You May Not Have A Veto
An authorized personal representative may have power to sell estate property without securing every beneficiary's approval. Rules vary by jurisdiction and governing documents. Your right to a fair administration isn't necessarily a right to personally approve each sale.
Self-Dealing Raises Red Flags
The rules become stricter when an executor purchases estate assets personally. Maine law, for example, makes certain conflicted transactions voidable unless properly authorized, approved, or consented to after disclosure. Protections vary by state, so seek advice before consenting.
You Can Request An Explanation
Beneficiaries generally have rights to information about estate administration and can challenge fiduciary misconduct. Ask who authorized the sale, whether a valuation exists, and how proceeds will be allocated. Get the answers in writing and preserve copies of the documents you receive.
Read The Actual Will
A will might leave the home to both children, give one child a particular asset, or divide the overall estate by percentage. Those instructions differ, and an equal share of the overall estate does not necessarily mean an equal share of every asset. Confirm what's written before deciding that each sibling is owed half the house.
Get A Neutral Appraisal
A licensed third-party appraisal offers a more defensible starting point than your brother's preferred number. A broker's suggested listing price can also inform negotiations, but neither sibling should simply announce the home's value and expect unquestioning agreement.
Condition Still Matters
A house needing major repairs may not command the same price as a renovated neighbor's property. Consider documented repair needs, the local market, and the appraisal together. A discount needs a defensible basis, not simply the argument that keeping the house in the family is desirable.
Here's What The Discount Costs
Suppose the home's fair market value is $600,000 and your brother offers $450,000. That's a $150,000 difference. If the estate would otherwise distribute sale proceeds equally, your share could be $75,000 lower before costs and debts.
Don't Forget The Mortgage
Market value isn't the same as equity. An outstanding mortgage, tax lien, or home-equity loan reduces the value available to owners. Calculate secured debt and resulting net equity.
Estate Bills Take Priority
Probate administration includes settling valid debts and taxes before distributing the remaining estate. That means even a valuable house doesn't automatically translate into an equally valuable inheritance. Request the estate's finances, not just its sale price.
A Buyout Is A Real Option
If you and your brother inherit equal ownership, he can potentially keep the house by purchasing your interest. An appraisal, equity calculation, and written distribution agreement make the transaction clearer. Focus on your share of net value.
He Still Needs Financing
Wanting the house and qualifying to purchase it are different matters. A sibling buying out another may need a mortgage or other financing. Ask how much he'll pay, when, and what happens if financing fails.
Put Every Term In Writing
Document valuation, mortgage payoff, closing expenses, payment date, and transfer terms. A real estate or estate attorney can draft the agreement. Promises aren't substitutes for enforceable terms, particularly when relationships are already strained.
Caregiving Is A Separate Conversation
Maybe your brother maintained the home or cared for your parents for years. Those contributions matter but don't automatically justify a discount. Any compensation or adjustment should reflect the governing documents, applicable law, and an agreement everyone understands.
 Inside Creative House, Shutterstock
Taxes Can Complicate A Family Discount
For federal gift-tax purposes, transferring property for less than full consideration may partly count as a gift. Inherited property generally has a date-of-death tax basis, unlike many lifetime gifts. Seek tax advice before changing the price.
If You Already Co-Own It
Co-ownership gives you a genuine property interest, although each owner's rights depend on the deed and state law. If you can't agree, a partition proceeding can sometimes end joint ownership through a court-ordered sale. Litigation carries costs and should generally come after an effort to reach a documented agreement.
 Evgeny Atamanenko, Shutterstock
So, Do You Get A Say?
If your parents own the house, you can raise concerns without claiming a legal vote. If you're a beneficiary, demand transparency; if you're a co-owner, assert your property rights. Identify the owner, obtain documents, and request an independent valuation.
You May Also Like:
Sources: 1, 2, 3, 4, 5, 6, 7, 8, 9, 10, 11, 12, 13, 14, 15, 16, 17, 18