I broke up with my boyfriend. I want out. But both our names are on the lease. My landlord won’t remove me—and now I can’t get approved elsewhere because I’m “already on a lease.” Am I financially trapped? Here’s what’s actually happening—and what you can realistically do.
Buying a home together can feel like the ultimate pre-marriage power move. But if only one partner will be on the mortgage and the deed, the arrangement stops looking equal very quickly. In plain terms, yes, you could end up paying toward a home you do not legally own.
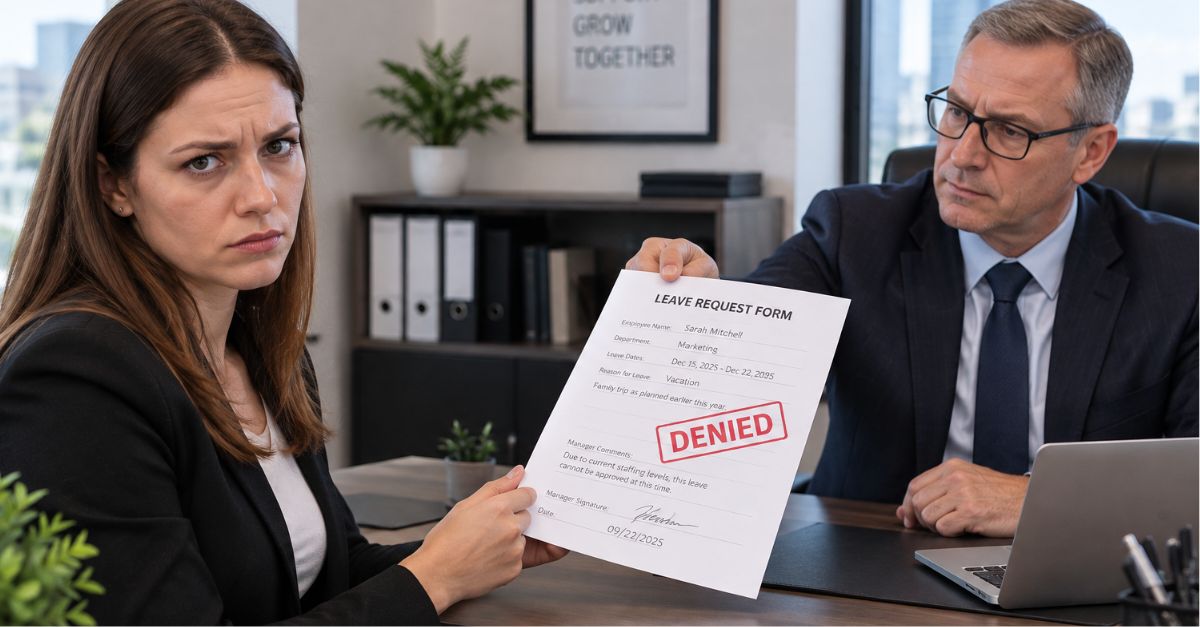
If your employer says your unused vacation days will vanish on December 31, it can feel like a bait and switch. That feeling gets even worse when the reason you did not take time off is simple: the company was too short-staffed to let you go. The frustrating truth is that whether they can do that often depends on where you work, what your policy says, and whether your vacation is treated as earned wages under state law.
Paying off your mortgage does not make retirement living free. Discover the overlooked housing, healthcare, insurance, tax, maintenance, transportation, and everyday costs retirees still need to budget for.
Your father promised you his classic 1969 Ford Mustang, but the title was still in his name when he died. Learn whether the estate controls the car, how verbal promises and wills affect ownership, and what steps could help you keep the Mustang.
A store card opened for a one-time renovation discount can look like a harmless shortcut. But if your spouse opened that account in your name without your permission, the discount may be the smallest part of the story. What starts at the checkout counter can quickly turn into identity theft, credit damage, and a legal mess inside a marriage.
It often starts with love and ends with resentment. One sibling lives nearby and becomes the default caregiver, while another lives hours away and gets accused of doing too little. The painful question is whether a brother or sister can fairly demand reimbursement for caring for an aging parent.
It is an argument happening at kitchen tables all over America. One spouse wants the guaranteed win of paying down the mortgage faster, while the other wants to chase the higher long-term returns that stocks have often delivered. The truth is that investing is not always better than becoming debt-free, and the smartest answer depends on your interest rate, your risk tolerance, and your timeline.
It sounds like a windfall, but inheriting a house can turn into a family standoff fast. One common flashpoint is when relatives assume the new owner should let someone stay there for free, sometimes for months or even years. If you inherited your grandmother’s home and now feel pressure to house an unemployed cousin indefinitely, the real question is not whether you are selfish. It is whether you are being asked to shoulder a financial burden that was never actually yours.
It is a stomach-dropping moment. Your parents paid for college years ago, never mentioned repayment, and now they want the money back because you earn more than your siblings. The big legal question is simple but loaded: can a gift be turned into a loan after the fact.