an-elderly-woman-in-pink-long-sleeves-looking-at-documents-while-sitting

Old Money Rules That Stopped Working Once Interest Rates Changed


September 22, 2026 | J. Clarke

Old Money Rules That Stopped Working Once Interest Rates Changed


The Old Playbook Was Built For Cheap Money

Americans got used to near-zero rates. The Federal Reserve cut its target to 0%–0.25% in March 2020, then raised it to 5.25%–5.50% in 2023. On July 29, 2026, it stood at 3.50%–3.75%.an-elderly-woman-in-pink-long-sleeves-looking-at-documents-while-sittingSHVETS production, Pexels.com
Advertisement

“Cash Barely Earns Anything” Is Outdated

When rates were near zero, hunting for extra savings yield felt pointless. The national savings rate was just 0.06% in late 2021; by August 2026, it was 0.38%, making cash placement more consequential.
Confident businessman in formalwear pointing at tablet computerViktoriia Hnatiuk, Shutterstock

Advertisement

Your Main Bank Is Not Automatically Best For Savings

Convenience once dominated because yields were tiny almost everywhere. Once rates rose, rate-shopping mattered again. Even the national average moved sharply from 2021 lows, so automatically leaving every spare dollar in one account became harder to justify.

Shutterstock-2757439465, Caucasian middle aged man handing cash to young adult bank teller behind glass counter, both interacting during financial transaction inside bank branch officeAnnaStills, Shutterstock

Advertisement

Short-Term Cash Deserves A Rate Check

Money needed soon should remain accessible, but “keep it anywhere” is no longer harmless. Savings accounts, CDs, money market funds, and Treasury bills can offer different yields, restrictions, and risks, so short-term cash deserves comparison too.
Shutterstock-1203993637, business partners showing money to exchange. holding US dollar, offers dollar bank note. cash in business, Paying compensation to partners.Janon Stock, Shutterstock

Advertisement

CDs Are Not Automatically Too Boring To Consider

A CD generally requires leaving money deposited for a set term, with a penalty for early withdrawal. That tradeoff matters more when rates are meaningful. In August 2026, the national 12-month CD rate was 1.71%.

Shutterstock-2605545069, Scene showing woman discussing documents with bank employee at reception counter with senior in background observing from seatAnnaStills, Shutterstock

Advertisement

Longer CDs Do Not Always Pay More

The old assumption says a longer lockup should earn more. Not always: in August 2026, the national 12-month CD rate was 1.71%, while the five-year national CD rate was about 1.36%.
Shutterstock-2359889345, Credit card with bank ststement report on desk, asian man verify the accuracy of bank statement after using credit card to pay for merchandiseLek_charoen, Shutterstock

Advertisement

Money Market Funds Are Not Just Fancy Savings Accounts

Money market funds invest in short-term debt and their yields generally reflect short-term rates. The SEC also stresses that they are investments, not bank deposits, and can lose value. Similar uses do not make the products identical.
Man with glasses holding a bank card while typing on a keyboard, sitting in front of a computer.Tima Miroshnichenko, Pexels

Advertisement

Emergency Funds Still Need Liquidity, But Yield Matters

Emergency money must be available when trouble hits, so the highest rate is not automatically best. Still, with savings rates above their 2021 lows, checking yield and withdrawal terms is no longer a meaningless exercise.
HK WTSD Wong Tai Sin District zh:牛池灣 Ngau Chi Wan zh:彩虹站 MTR Choi Hung Station concourse shop in August 2022TMMSUMERA LVINGO, Wikimedia Commons

Advertisement

Treasury Bills Are Not Only For Wealthy Investors

Treasury bills mature in four to 52 weeks and can be bought through TreasuryDirect in $100 increments. They are auctioned below or at face value and pay face value at maturity, putting them within reach of ordinary savers.
A smartphone displaying a currency converter surrounded by dollar and euro banknotes, highlighting exchange ratesUMA media, Pexels

Advertisement

I Bonds Do Not Lock In One Headline Rate Forever

I bonds combine a fixed rate with an inflation rate that resets every six months. Bonds issued from May through October 2026 carried a 4.26% composite rate, including a 0.90% fixed component. Future composite rates can change.
Shutterstock-2673004335, Stressed asian young businessman hand write management budget for saving cost expenses of monthly, male holding bills and receipt for to payment on table at home. Financial, finance of banking conceptKmpzzz, Shutterstock

Advertisement

Savings Interest Is Not Too Small To Think About At Tax Time

The IRS says interest from bank accounts, money market accounts, CDs, and many bonds is generally taxable. When yields rise, that income can become more noticeable, so the after-tax return matters more than the headline rate alone.
A businessman using a smartphone and credit card for online banking in a modern café.Vitaly Gariev, Pexels

Advertisement

“Pay Off Every Mortgage Fast” Needs Context

Mortgage math depends heavily on when the loan was originated. Freddie Mac’s average 30-year fixed rate ended 2020 at 2.67%; on September 10, 2026, it was 6.76%. One payoff rule cannot treat those borrowing costs alike.
Shutterstock-2707122069, Couple having a consultation with a financial advisor about real estate investment and insurancePreciousJ, Shutterstock

Advertisement

Refinancing Is Not An Automatic Escape Hatch

Borrowers who remember falling mortgage rates may assume they can refinance later. But refinancing carries costs, and today’s rates can be far above pandemic-era levels. The CFPB says borrowers should compare APRs, not only advertised interest rates.
Shutterstock-1239372607, Kiev, Ukraine - November 23, 2018: Queue at the national bank PrivatBank in the city center. Payment of utility services.ShapikMedia, Shutterstock

Advertisement

A “No-Cost” Refinance Is Not Free

The CFPB says lenders generally create a “no-cost” refinance by charging a higher rate for lender credits or adding closing costs to the new loan balance. The charge changes form, but it does not disappear.
Smiling mature couple meeting with bank manager for investmentRido, Shutterstock

Advertisement

An ARM Is Riskier If Your Plan Is “I’ll Refinance”

Adjustable-rate mortgages can start below fixed rates, but payments can rise after resets. The CFPB specifically cautions borrowers not to assume they will be able to sell or refinance before an adjustment occurs.
Businessman holding a model house symbolizing real estate investment.Kindel Media, Pexels

Advertisement

A HELOC Is Not Permanently Cheap Mortgage Money

HELOCs usually have variable rates, according to the CFPB, so payments can change as market rates move. Payments can also rise after the draw period ends, when borrowers begin repaying principal as well as interest.
A person analyzing a return on investment report with a pen in hand on a desk.Kindel Media, Pexels

Advertisement

The Lowest Mortgage Rate Is Not Always The Cheapest

Interest rate and APR are different. The CFPB says mortgage APR includes the rate plus points, broker fees, and certain other charges. Comparing only the quoted rate can hide what obtaining that rate actually costs.
Shutterstock-2672173697, Stressed real estate agents face debt, bankruptcy, mortgage crisis, financial worries, taxes, loans, expenses, contracts, and housing market pressures.SAI SU PAW KA, Shutterstock

Advertisement

Paying Mortgage Points Does Not Always Save Money

Discount points are upfront fees for a lower mortgage rate. CFPB research says borrowers generally benefit only if they keep the loan beyond the break-even point. Selling or refinancing earlier can erase the expected savings.
Stressed young asian woman calculating monthly home expensesDavid, Adobe Stock

Advertisement

The Monthly Car Payment Is Not The Main Number

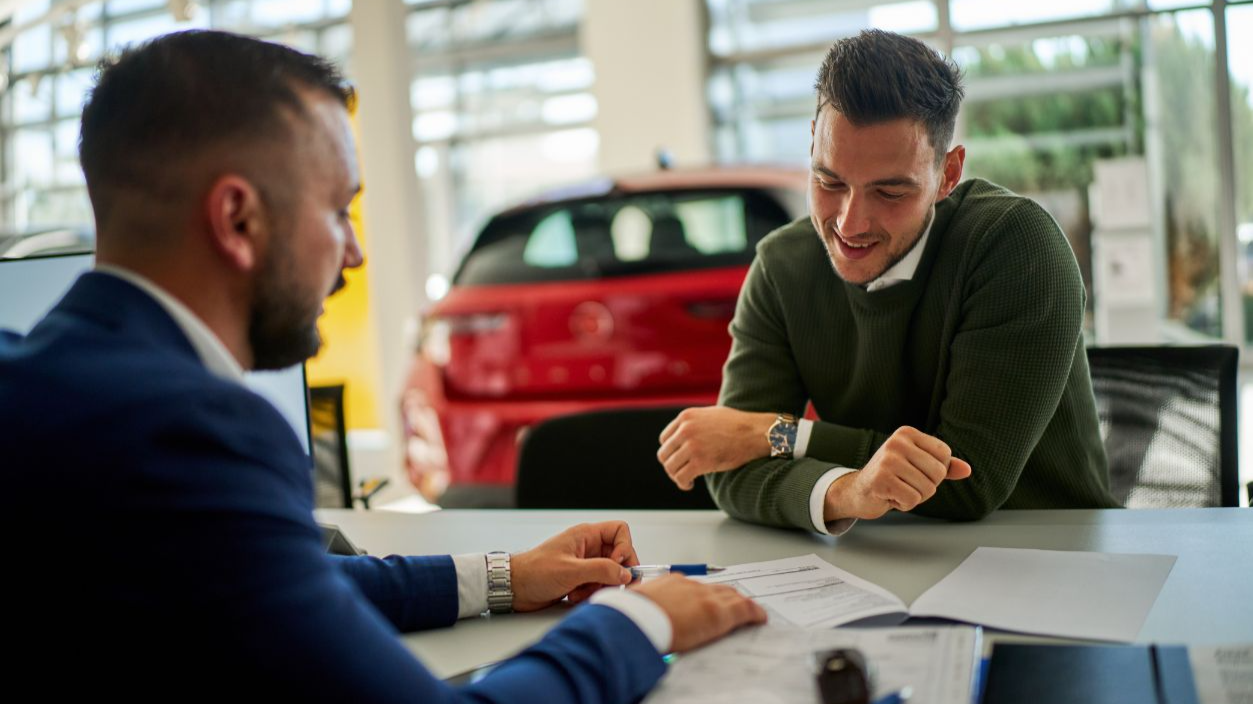
The CFPB recommends comparing APR, term, amount financed, and total cost. Its example shows a $20,000 loan at 4.75% costing $1,498 in interest over 36 months, versus $3,024 over 72 months.
Shutterstock-2582442077, Car salesman and a customer engage in a discussion at a dealership table. Documents and a car key are on the table, with a vehicle visible in the background through large windowsf.t.Photographer, Shutterstock

Advertisement

Stretching A Car Loan Can Cost More Than It Saves

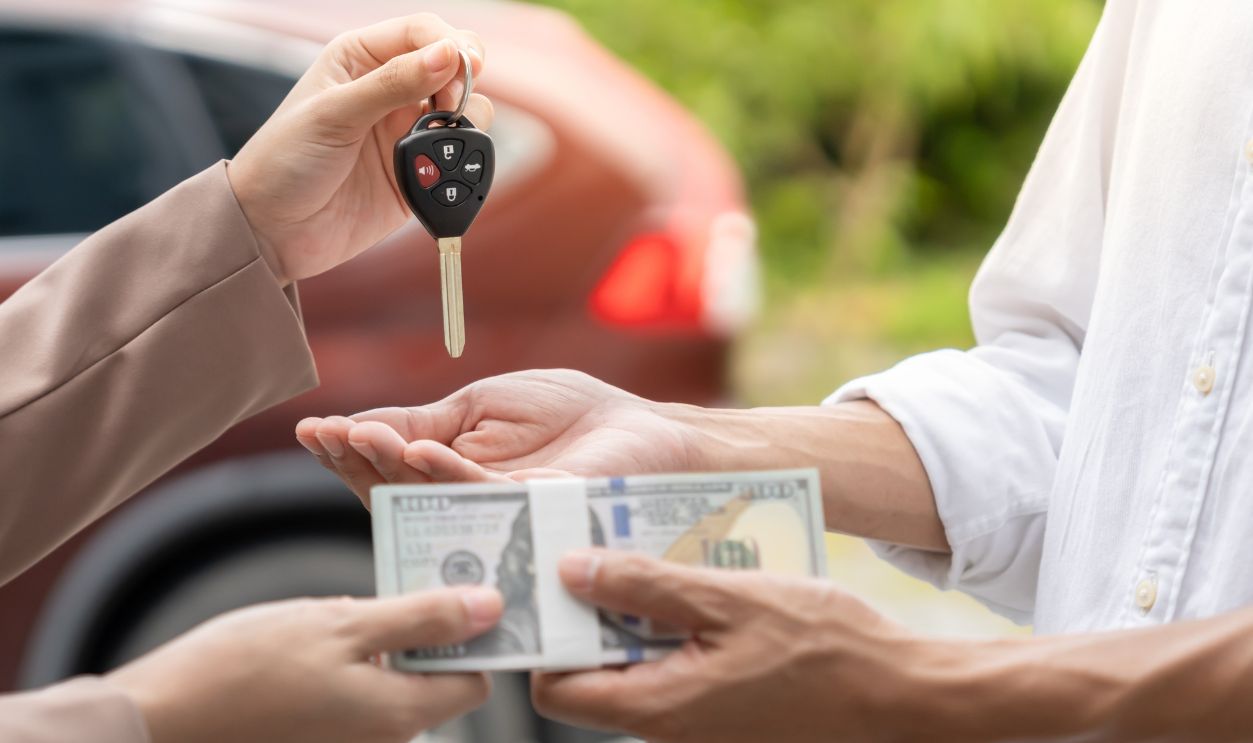
A longer term lowers the monthly payment but keeps interest accruing for more months. In the CFPB example, doubling a $20,000 loan’s term from 36 to 72 months more than doubles total interest.
Shutterstock-2642986133, lease, rental and selling car. Car agent sent key for new owner. Customer pass on money for buy. rent car, Sales, loan credit financial, insurance, Seller, dealer, installment, Used carshisu_ka, Shutterstock

Dealer Financing Deserves A Comparison

The CFPB notes that a dealer’s offered rate can exceed the lender’s “buy rate,” with the difference compensating the dealer. Comparing outside financing before signing can reveal whether convenience carries a substantial premium.
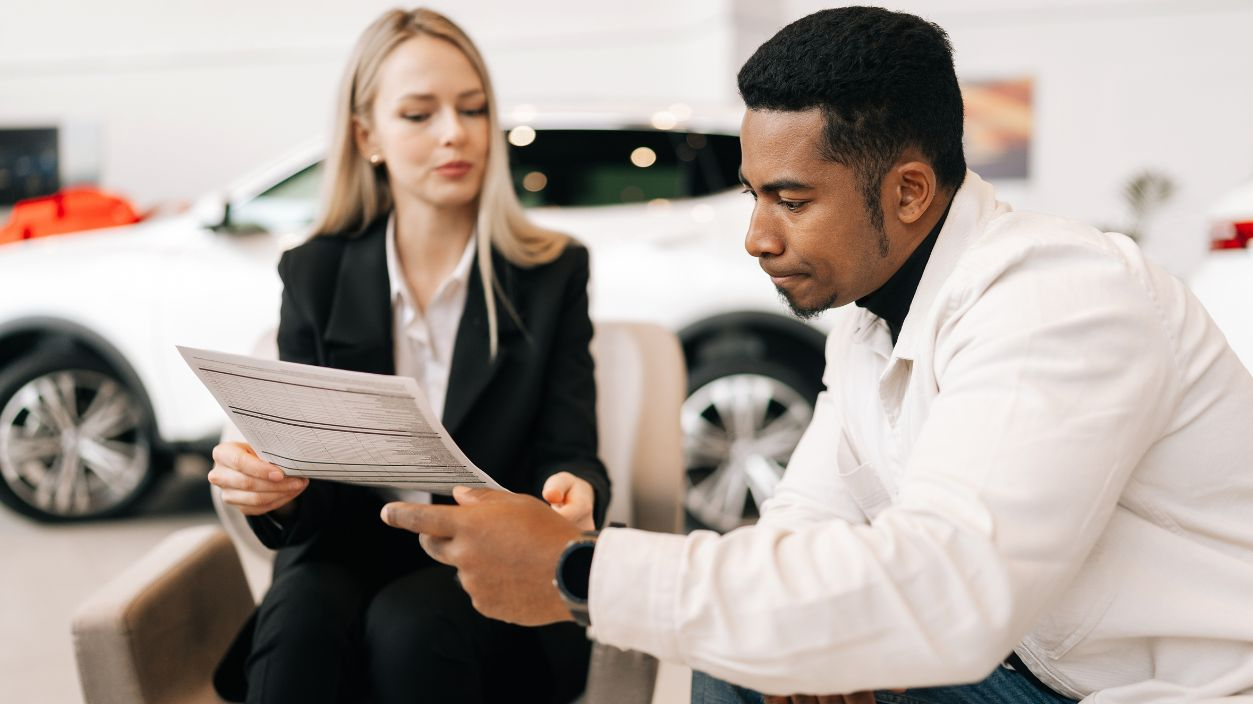
Shutterstock-2556812455, Medium shot of female manager consulting doubtful black buyer, giving purchase agreement for review at showroom. Thoughtful African client receiving car purchase contract before signing in dealershipDikushin Dmitry, Shutterstock

Advertisement

Variable Credit-Card APRs Move With The Market

The CFPB explains that a variable APR changes with an index, often the prime rate. When benchmark rates rise, carrying a balance can become more expensive even without additional spending. The rate is not permanently static.
Shutterstock-1361534768, Young couple in budget planning conceptElnur, Shutterstock

Advertisement

New Student Loans Do Not Cost What Older Loans Did

Federal student-loan rates are fixed for each loan, but new loans receive new rates. Undergraduate Direct Loans were 2.75% in 2020–21; for 2026–27, the rate is 6.52%. Different graduating classes can face very different borrowing costs.
File:2023 PVCC Graduates - 070.jpgPiedmont Virginia Community College (PVCC), Wikimedia Commons

Advertisement

Bonds Are Not Automatically The “Safe” Part

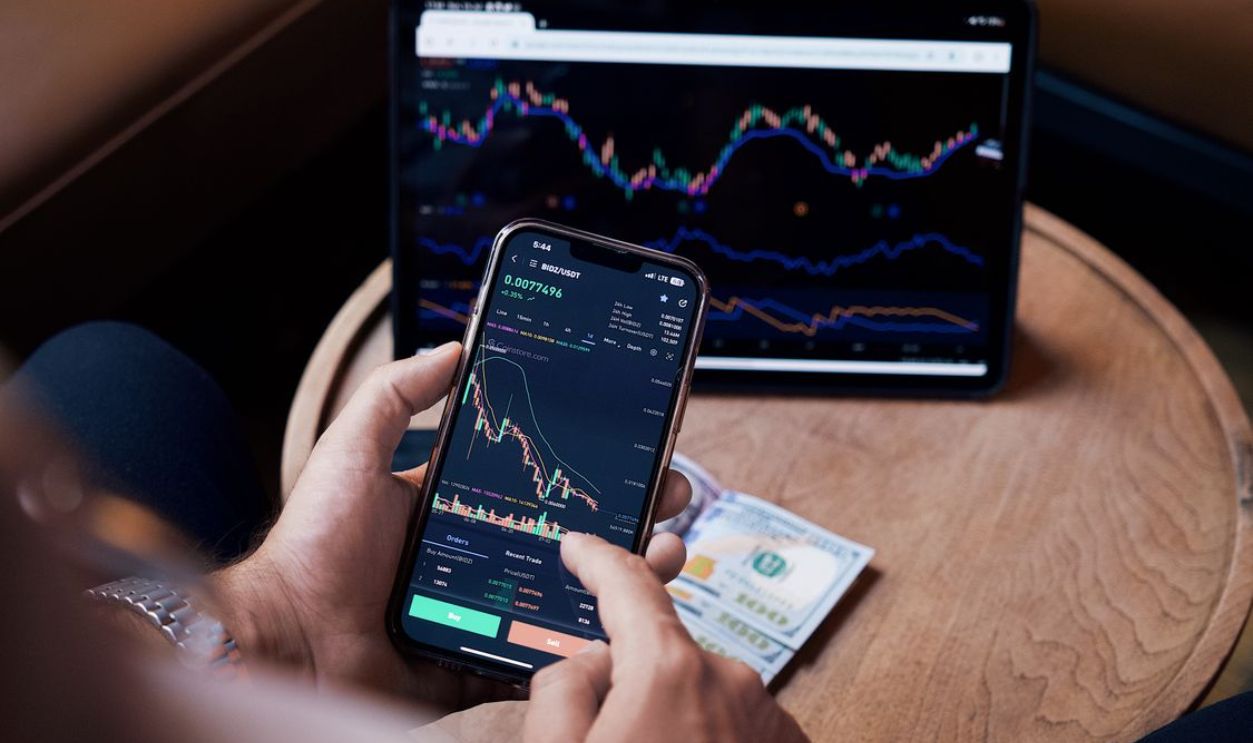
The SEC explains that fixed-rate bond prices generally fall when market rates rise. That does not make every bond unsafe, but it means bond values can decline as rates change. “Safe” depends on which risk matters.
investing stocksiam hogir, Pexels

Advertisement

Long-Term Bonds Are Not A Substitute For Cash

Interest-rate risk is generally greater for longer-maturity bonds because distant payments are more sensitive to rate changes. Treasury bills, by contrast, mature within one year. Money needed soon should not be treated like long-duration bond money.
Serious business man trader analyst looking at computer monitorinsta_photos, Adobe Stock

Advertisement

The New Rule Is To Check The Rate

Interest rates reshape saving, borrowing, and investing. Rules formed during years of ultra-cheap money can fail when cash yields more and debt costs more. Compare the rate, term, fees, taxes, liquidity, and risk before following an old shortcut.
Shutterstock-2424450137, Smiling female financial advisor, attorney lawyer or bank manager consulting client investor reading document at business meeting reviewing legal paper file planning taxes working in office.insta_photos, Shutterstock

Advertisement

You  May Also Like:

Grow Your Money: A Beginner's Guide To Trading Stocks

Is This The Most Prized Commodity Of All Time?

Kevin O'Leary Gives His Best Advice For Investing And A Successful Career
Sources:  1, 2


READ MORE

Propvalue-Int

Upgrades You Should Implement To Increase Your Property Value

The housing market is competitive, to say the least. If you want your home to stand out on the market, here are some things you can do to make it seem brand new.
December 19, 2024 Ethan Vestby
Last Will

Things You Need In Your Will That Too Many People Forget

Think your will is complete? Even the most carefully crafted ones often miss necessary elements that could leave your family in limbo. If you want it to be a peaceful ride, continue reading.
January 15, 2026 Miles Brucker
Fb Og Image - Career Changes

Simple Career Changes To Make More Money In 2025

If you're looking to change tracks in 2025 and jump into a new career but aren't looking to go back to school or spend time and money retraining in an entirely new profession, here are some career changes you can make to make more money next year.
January 1, 2025 Jack Hawkins
Husbandgamblinginternal

My husband hid over $100K in gambling debts while I thought he had the money invested. At 55, our retirement is off-track. What happens next?

It can be devastating to discover hidden debt if you're in your 50s, but there are steps you can take to protect your future and your retirement.
October 29, 2025 Sammy Tran
Laidoff50Internal

Laid Off In Your 50s: Strategies For Moving Forward

Losing your job is bad enough, but being laid off in your 50s hits especially hard. We look at strategies for getting back on track.
October 30, 2025 Alex Summers
Leasemileage-Simple

My Lease Is Ending And I’m Over The Mileage Limit. Should I Buy It Out Or Turn It In?

You’re cruising toward the end of your lease, feeling pretty good… until you check the odometer and your contract. You’re thousands of miles over the limit, and those little extra miles are about to cost real money. Do you pay the mileage fees and turn it in, or buy out the car and keep it? The good news is that you actually have more control here than it feels like.
December 3, 2025 Peter Kinney


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕