Retiring At 50 Means You Need 40+ Years Saved
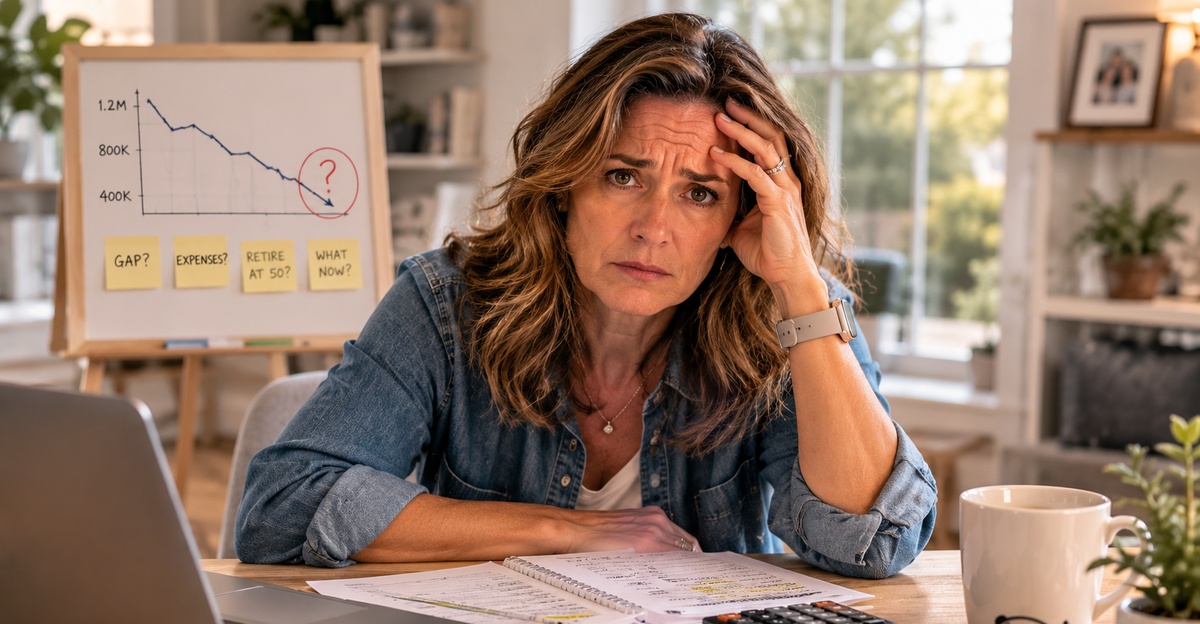
Retiring at 50 isn’t early anymore—it’s very early. That means your money may need to last 40+ years, not the traditional 25–30. The question isn’t just whether $400K is enough today, but whether it can sustain decades of withdrawals, inflation, and market volatility. This is a longevity problem as much as a savings problem.
The Brutal Truth: $400K Alone Won’t Carry You to 90
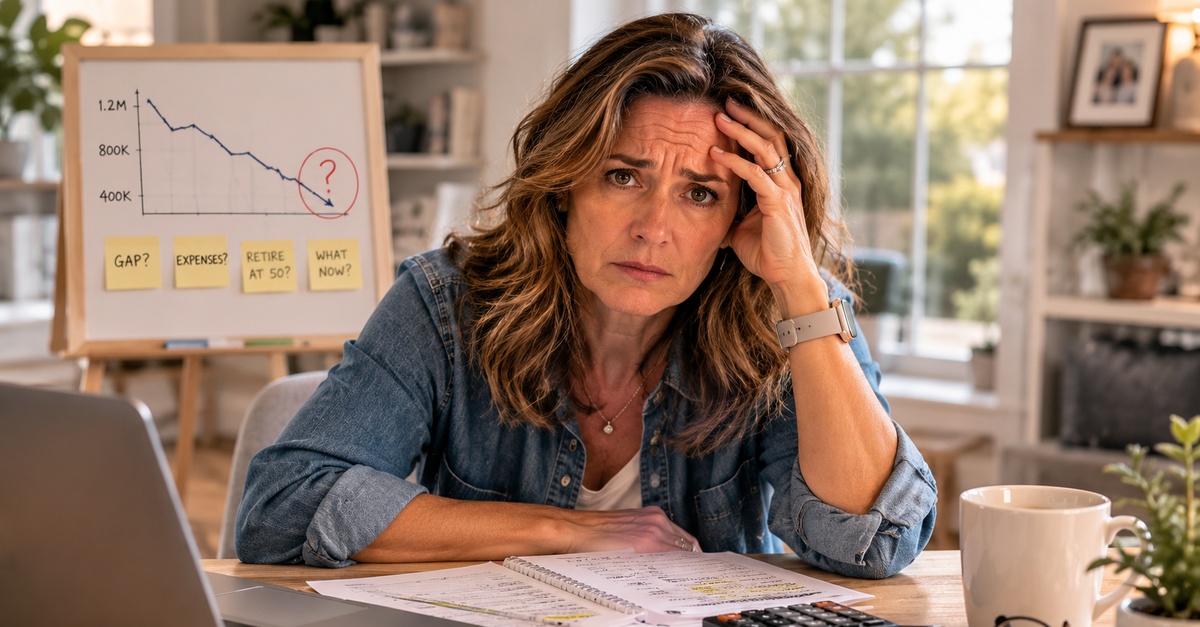
If you’re hoping to fully retire at 50 with $400K, the math doesn’t support it. Even conservative assumptions would put your safe annual withdrawal far below what most people need to live. This doesn’t mean your goal is dead—it means your strategy needs to change. Right now, there’s a gap, and it’s likely significant.
Start With the 4% Rule—Then Question It
The 4% rule suggests you can withdraw about 4% of your portfolio annually without running out of money over ~30 years. On $400K, that’s about $16,000 per year. But you’re aiming for a 40+ year retirement, so even 4% may be too aggressive. A safer range might be closer to 3–3.5%, which shrinks your income further.
What Do You Actually Need to Live On?
Before calculating the gap, you need a real number for annual expenses. Are you aiming for $40K/year? $60K? More? Many people underestimate healthcare, housing, and lifestyle costs—especially over decades. Your retirement target should reflect your actual life, not a hopeful guess.
 Centre for Ageing Better, Unsplash
Reverse-Engineer Your Target Number
Once you know your desired annual income, you can work backward. For example, needing $50K/year at a 4% withdrawal rate means a $1.25M portfolio. At 3.5%, that jumps closer to $1.43M. That’s your real target—not $400K.
The Gap Is Likely Six Figures (Or More)
If your target is $1.25M and you have $400K, your gap is $850K. That’s the number you need to close through savings, investing, or income strategies. Seeing it clearly is uncomfortable, but it’s also empowering. Now you’re solving a real problem, not guessing.
Time Is Your Biggest Lever (Even If You Hate That)
If you’re currently far from 50, you still have time to grow your investments. Compound growth can do heavy lifting—but only if you give it enough runway. Even an extra 5–10 working years can dramatically shrink your gap. Early retirement is often about timing trade-offs.
Your Savings Rate Needs to Be Aggressive
Closing a large gap requires more than passive contributions. You may need to save 20–40% of your income, depending on your timeline. That could mean cutting expenses, increasing income, or both. The math rewards discipline here.

Investment Returns Matter—But Don’t Overreach
You can’t rely on unrealistic returns to close the gap. A reasonable long-term assumption is 5–7% after inflation, depending on your asset mix. Chasing higher returns usually means higher risk, which can backfire—especially as you approach retirement. Your plan needs to survive bad markets too.
Consider Partial Retirement as an Approach
Full retirement at 50 might not be necessary. Many people shift to part-time work, consulting, or passion projects that generate income. Even earning $15–25K/year can drastically reduce the pressure on your portfolio. This hybrid model makes the math far more achievable.
Your Lifestyle Expectations Might Need Adjusting
If your current savings don’t match your retirement vision, one has to give. Downsizing your home, relocating, or simplifying your lifestyle can reduce your required income. Lower expenses = smaller portfolio target = smaller gap. This is one of the fastest levers you can pull.
 Alicia Christin Gerald, Unsplash
Inflation Will Quietly Erode Your Plan
Over 40 years, inflation is not a minor detail—it’s a major force. What costs $50K today could be $90K+ in the future, depending on inflation rates. Your investment strategy must outpace inflation, not just match it. Ignoring this leads to underestimating your true needs.
Healthcare Costs Are a Wildcard
Retiring before traditional retirement age means bridging years without standard benefits. Private insurance, out-of-pocket costs, and unexpected health issues can add significant expenses. These are often underestimated in early retirement plans. Build a buffer—don’t assume best-case scenarios.
Sequence of Returns Risk Is Real
The 'sequence of returns' risk refers to the danger of poor market returns early in retirement. If markets drop right after you retire, your portfolio can take a permanent hit. This risk is amplified with longer retirements. Your plan needs flexibility to handle bad early years.
 Volodymyr Hryshchenko, Unsplash
Can You Increase Income Instead of Just Cutting Costs?
Cutting expenses has limits—earning more doesn’t. Career moves, side hustles, or entrepreneurship can accelerate your savings dramatically. Even a temporary income boost can significantly shrink your gap. This is often the most overlooked lever.
Delay Full Retirement—Even Slightly
Moving your retirement age from 50 to 55 can make a massive difference. You gain more savings time, fewer years to fund, and potentially higher investment growth. It’s not failure—it’s optimization. Many “early retirees” succeed by adjusting timelines, not abandoning goals.
Tax Strategy Matters More Than You Think
Where your $400K is held matters—taxable accounts, retirement accounts, or tax-free vehicles all behave differently. Withdrawals, capital gains, and tax brackets will impact your real income. A tax-efficient withdrawal strategy can stretch your money further. This is an area worth professional guidance.
Build Multiple Income Streams
Relying on a single portfolio is risky over 40+ years. Rental income, dividends, business income, or royalties can diversify your retirement cash flow. Multiple streams reduce pressure on your savings. They also provide flexibility if one source underperforms.
Stress-Test Your Plan
Don’t rely on one projection. Test your plan against different scenarios—lower returns, higher inflation, longer lifespan. If your plan only works in perfect conditions, it’s not a plan. You need resilience, not optimism.
You’re Not Behind—You’re Just Early
Many people aiming for retirement at 50 are ahead of the average saver. The issue isn’t failure—it’s ambition. You’re trying to compress decades of saving into a shorter window. That requires a sharper, more intentional strategy.
The Bottom Line: Close the Gap or Redefine the Goal
Right now, $400K likely isn’t enough for a full retirement at 50. But with higher savings, adjusted expectations, or hybrid income, the goal can still be within reach. The real question isn’t “Can I retire?”—it’s “What version of retirement can I afford?” Answer that honestly, and you’ll build a plan that actually works.