Woman nervous older men arguing

I’m buying my first home and my dad says I should get an adjustable-rate mortgage, but my uncle says always go fixed. Now I’m panicking—who’s right?


May 14, 2026 | Jesse Singer

I’m buying my first home and my dad says I should get an adjustable-rate mortgage, but my uncle says always go fixed. Now I’m panicking—who’s right?


Everyone Has an Opinion

Buying your first home comes with a flood of advice, especially about your mortgage. Fixed vs. variable might sound simple, but it can shape your finances for years. When two people you trust completely disagree, it’s easy to feel stuck before you’ve even begun.
Woman nervous older men arguing Factinate

Advertisement

What a Fixed-Rate Mortgage Actually Does

A fixed-rate mortgage locks in your interest rate for the entire loan term—typically 15 or 30 years in the U.S.—so your principal and interest payments stay consistent over time. Even if market rates rise significantly, your core payment won’t change, which makes long-term planning much easier.
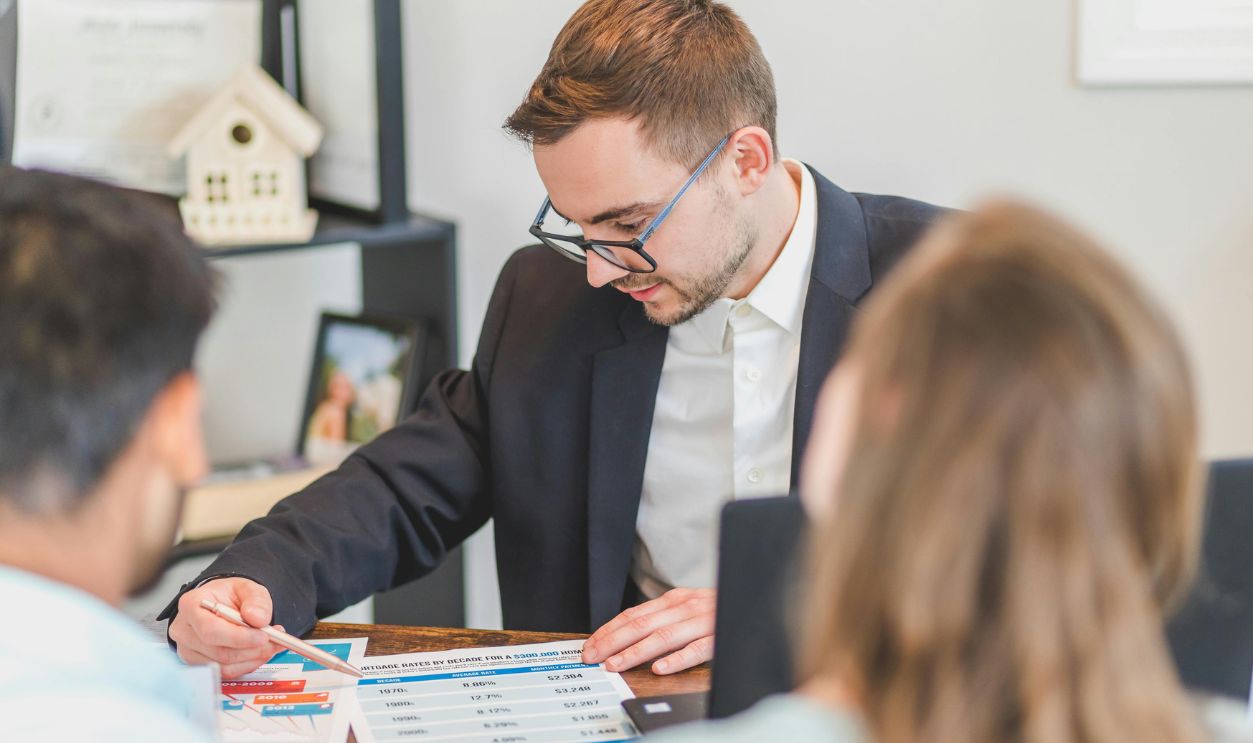
A real estate agent explains mortgage options to clients in an office setting.RDNE Stock project, Pexels

Advertisement

Why Mortgages Work Differently in Other Countries

In the U.S., fixed-rate mortgages often last 15 or 30 years with one locked-in rate. But in Canada, the U.K., and parts of Europe, borrowers often deal with shorter fixed periods or terms before the rate resets or the mortgage is renewed. That difference helps explain why advice can vary so widely across generations and regions.
Focused woman analyzing papers with a laptop open, symbolizing thoughtful considerationNataliya Vaitkevich, Pexels

Advertisement

What a Variable-Rate Mortgage (ARM) Really Means

In the U.S., a variable-rate mortgage is usually called an adjustable-rate mortgage (ARM). These loans start with a lower fixed rate for a set period—like 5, 7, or 10 years—then adjust periodically based on market rates. After that initial period, your monthly payment can go up or down depending on economic conditions.
Failing To Refinance High-Rate Loans As Interest Rates DeclineKarola G, Pexels

Advertisement

Why Fixed Rates Feel Safer

Fixed rates are popular because they remove uncertainty. If interest rates rise significantly, your payment won’t change. During past rate spikes, homeowners with fixed mortgages avoided the kind of sudden payment increases that adjustable-rate borrowers sometimes experienced.
A woman in a plaid coat counts American dollars at a desk with a notebook and laptop.Yan Krukau, Pexels

Advertisement

Why Variable Rates Can Look Attractive

ARMs often start with lower interest rates than fixed mortgages. That means lower monthly payments early on, which can help buyers qualify for a home, reduce upfront costs, or free up cash for other expenses like renovations or savings.
Person holds US dollars over financial papers, showing income or budget analysis.Tima Miroshnichenko, Pexels

Advertisement

What History Shows in the U.S.

Over long periods, fixed-rate mortgages have been the dominant choice in the U.S., especially for first-time buyers. After the 2008 housing crisis, many borrowers became more cautious about adjustable rates due to the risks tied to rising payments and market volatility.
Young woman working on laptop while relaxing on a sofa with pillows, indoorsMatilda Wormwood, Pexels

Advertisement

The Risk Factor You Need to Understand

With an ARM, your rate could increase after the initial fixed period. For example, a 5/1 ARM adjusts once per year after year five, and rates can rise several percentage points over time. That can translate into hundreds of dollars more per month, depending on your loan size.
A young couple enjoys a relaxing day at home using their laptop on the couchAnete Lusina, Pexels

Advertisement

Rate Caps Offer Some Protection

Most ARMs include caps that limit how much your rate can increase annually and over the life of the loan. For example, a 2/2/5 cap limits annual increases to 2% and total increases to 5%. These caps help, but they don’t fully remove the risk of higher payments.
A mortgage broker and client discussing loan options in a modern office setting.RDNE Stock project, Pexels

Advertisement

Budget Stability Matters More Than You Think

If your budget is tight, even a modest rate increase could create pressure. Fixed rates eliminate that uncertainty, which is why many first-time buyers prefer them when stretching to afford a home in the first place.
HomeequityinternalCast of Thousands, Shutterstock

Advertisement

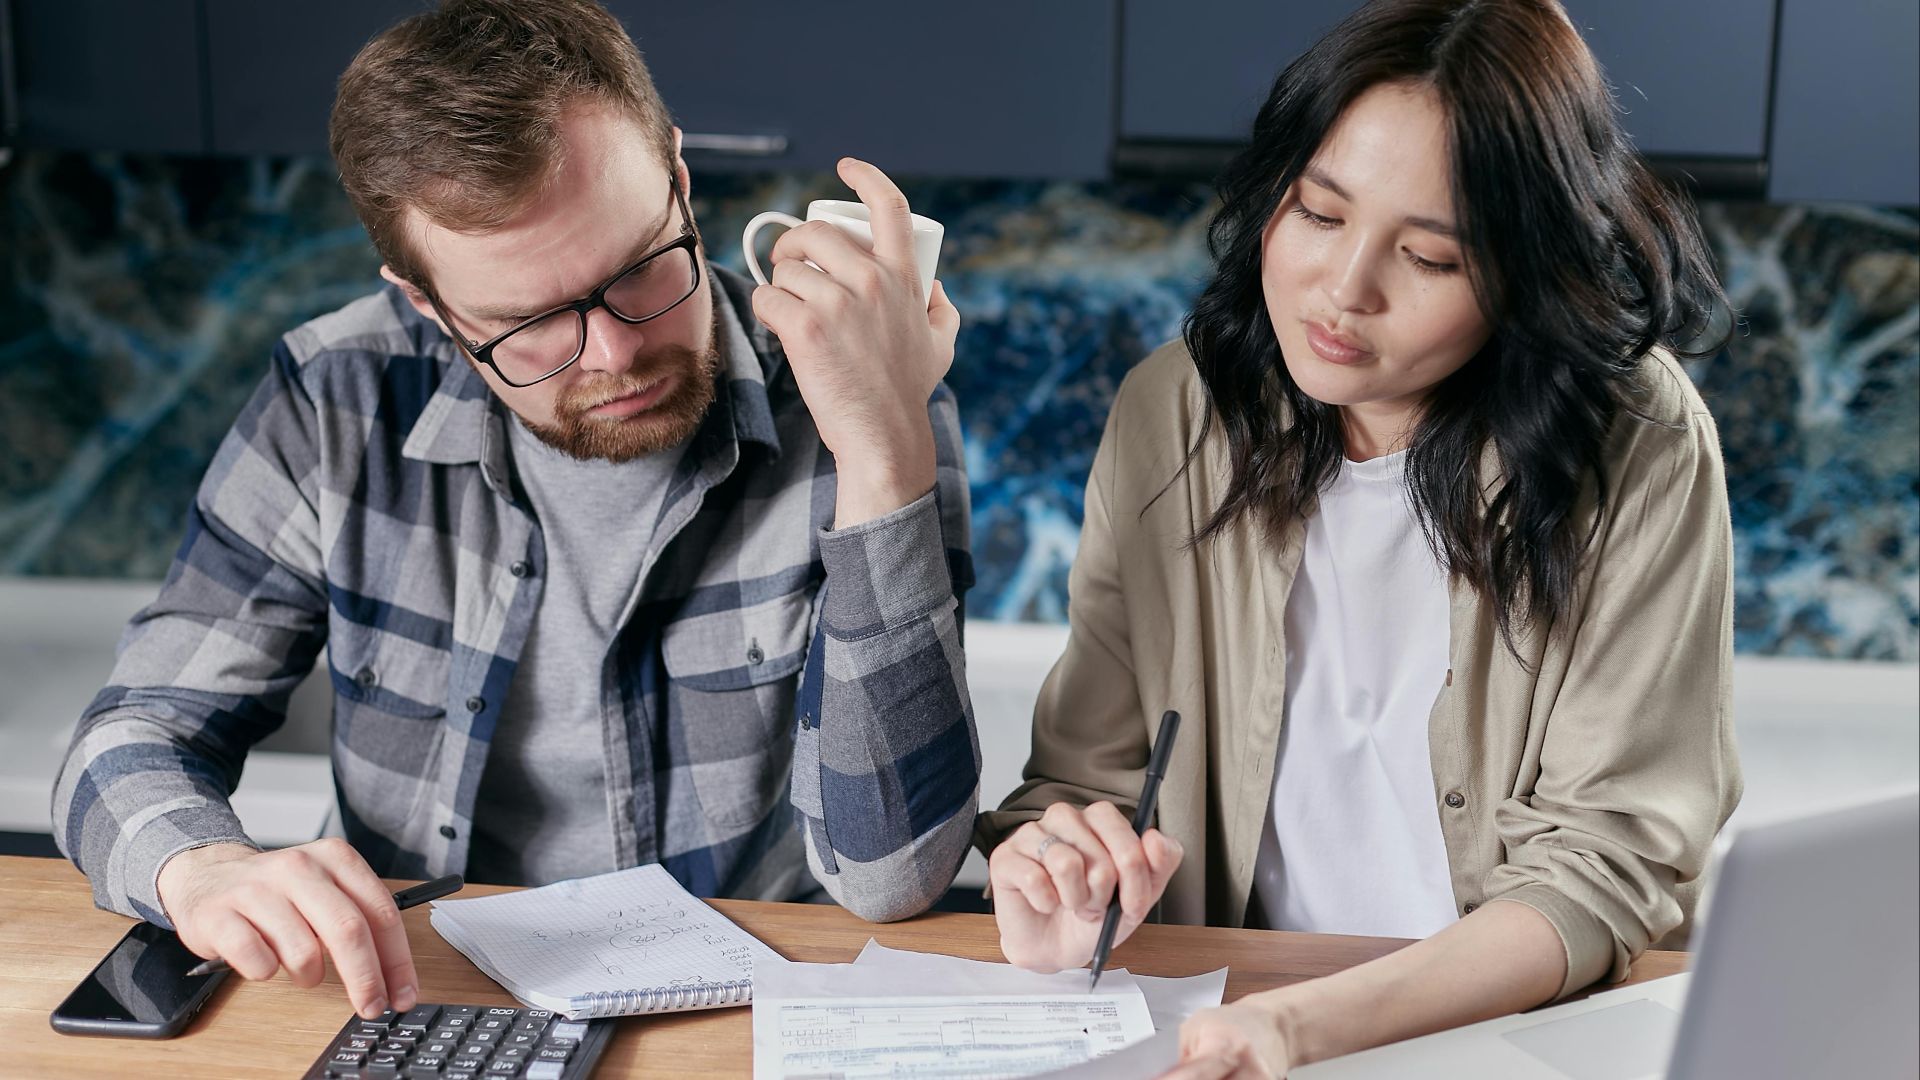
Your Time Horizon Changes the Equation

If you plan to move or refinance within a few years, an ARM can make sense because you may never reach the adjustment period. Longer-term homeowners, especially those planning to stay 10+ years, tend to benefit more from fixed stability.
A couple reviewing household bills and budget using a calculator and laptop at their kitchen table.Mikhail Nilov, Pexels

Advertisement

Interest Rates Don’t Stay Still

Mortgage rates are influenced by inflation, Federal Reserve policy, and the broader economy. When inflation rises, borrowing costs usually follow, which directly impacts adjustable-rate mortgages and future refinancing opportunities.
Underestimating InflationFast-stock, Shutterstock

Advertisement

The Stress Factor Is Real

Even if an ARM could save money, it’s not always worth the uncertainty. Financial stress is one of the top concerns for homeowners, and unpredictable payments can make budgeting feel unstable month to month.
Woman in blue sleeves appears stressed while looking at receipts and money, symbolizing financial stress.www.kaboompics.com, Pexels

Advertisement

First-Time Buyers Often Choose Predictability

In the U.S., most first-time buyers choose 30-year fixed mortgages. Predictable payments make it easier to manage other new costs like property taxes, insurance, maintenance, and unexpected repairs.
Three adults discuss a home insurance policy at a meeting table indoors.Mikhail Nilov, Pexels

Advertisement

When Variable Rates Make More Sense

ARMs can work well for buyers with strong financial cushions, stable income, or clear short-term ownership plans. If you expect to move, sell, or refinance before the adjustment period begins, the lower starting rate can provide real savings.
A woman working from home on a sofa with a laptop and documents, managing finances.Nataliya Vaitkevich, Pexels

Advertisement

Don’t Forget About Refinancing

Many homeowners refinance when rates drop or their financial situation improves. This flexibility means even a fixed-rate mortgage isn’t necessarily permanent, and you can adjust your strategy later if conditions change.
A realtor finalizes a home sale with a handshake agreement, welcoming new homeowners to their property.Thirdman, Pexels

Advertisement

Penalties and Flexibility

Some U.S. mortgages include prepayment penalties, but many common home loans do not. The key is to check your loan estimate and closing documents before signing. If you might refinance, sell, or pay extra early, this detail matters more than people realize.
Businesswoman in a blazer reviewing documents at a desk. Professional office setting with laptop and papersMART PRODUCTION, Pexels

Advertisement

Stress-Test Your Budget

Ask yourself what would happen if your payment increased by $200–$500 per month. If that scenario feels uncomfortable or unrealistic, a fixed rate may be the safer and more sustainable option.
Hands handling cash and calculator for budget planning. Modern financial scene.www.kaboompics.com, Pexels

Advertisement

Family Advice Comes From Experience

Your dad and uncle are likely speaking from their own experiences—and possibly very different interest rate environments. What worked well for them may not perfectly apply in today’s market conditions.
two men talkingLinkedIn Sales Solutions, Unsplash

Advertisement

What Experts Usually Recommend

Most financial experts suggest choosing based on your risk tolerance and financial stability. Fixed rates offer consistency and peace of mind, while ARMs offer flexibility and potential cost savings.
a woman with pink hair is looking at a laptopParabol | The Agile Meeting Tool, Unsplash

A Simple Way to Decide

If you value certainty and steady payments, fixed is usually the better choice. If you’re comfortable with some risk and want lower initial costs, an ARM could work depending on your timeline.
A serious businessman focusing intently on his work, using a laptop indoorsMART PRODUCTION, Pexels

Advertisement

You’re Not Locked In Forever

Even with a 30-year mortgage, your first loan choice does not have to be permanent. Many homeowners refinance, sell, or change strategies later, though current data shows the typical U.S. homeowner now stays in place for about 12 years. That makes the initial decision important—but not irreversible.
Consider Reverse Mortgage Options CarefullyPeopleImages.com - Yuri A, Shutterstock

Advertisement

The Bottom Line

Both your dad and your uncle are giving advice that works in different situations. Fixed offers peace of mind and predictability. Variable offers flexibility and potential savings. The right answer depends on your finances, your timeline, and how much uncertainty you’re comfortable handling.
happy-homeowners-celebrating-relocationfizkes, Shutterstock

Advertisement

You Might Also Like:

My landlord says repairs will only be done if I stop "nagging him." Water is leaking onto my bed. Can they really refuse basic fixes?

My real estate agent helped me close the sale of my house. She usually gets a 5% commission, but is demanding 10% for 'extra work.' Should I pay her?

Sources:  1, 2, 3


READ MORE

Rss Thumb - Parents Retirement Account Left To One Sibling

My parents left their retirement account to only one child—but there are two of us. I'm cut out. Did they understand what they were doing?

Your parents left their retirement savings to your sibling and nothing to you. Here's what inheritance laws say and when you can challenge their decision.
October 22, 2026 Jack Hawkins
Rss Thumb - 1960S Jobs

Jobs From The 1960s That Baby Boomers Never Imagined Would Be Taken Over By Computers—Did You Have One Of These Jobs?

Remember these jobs from the 1960s? Discover the once-common careers that Baby Boomers knew well before computers, automation, and AI changed the workplace forever.
October 22, 2026 Jack Hawkins
1980s woman eating pizza

Pizza Chains From The 1980s That Baby Boomers Couldn’t Get Enough Of—But Are Now Hard To Find

Remember the pizza chains Americans loved in the 1980s, from arcade-filled restaurants to regional favorites that have disappeared or become hard to find.
October 22, 2026 Allison Robertson
Dagmar Berghoff, Max Schautzer, 1. Treffen;Vorbereitung, ARD-"Wunschkonzert", Buffet,;Restaurant

Forgotten Buffet Chains That Americans Loved Because They Seemed Like A Deal—Even If They Weren't

Remember America's forgotten buffet chains, from Old Country Buffet to Ryan's. Discover why families loved these all-you-can-eat restaurants, whether they were really bargains, and why so many disappeared.
October 21, 2026 Marlon Wright
Rss Thumb - 1970S Grocery Store Trading Cards

Trading Stamp Rewards From The 1970s That Baby Boomers Loved—But Gen Z Wouldn't Believe Could Get You A Family Vacation

Remember S&H Green Stamps? Discover the surprising grocery store trading stamp rewards Baby Boomers collected in the 1970s, from toasters to televisions.
October 21, 2026 Jack Hawkins


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕