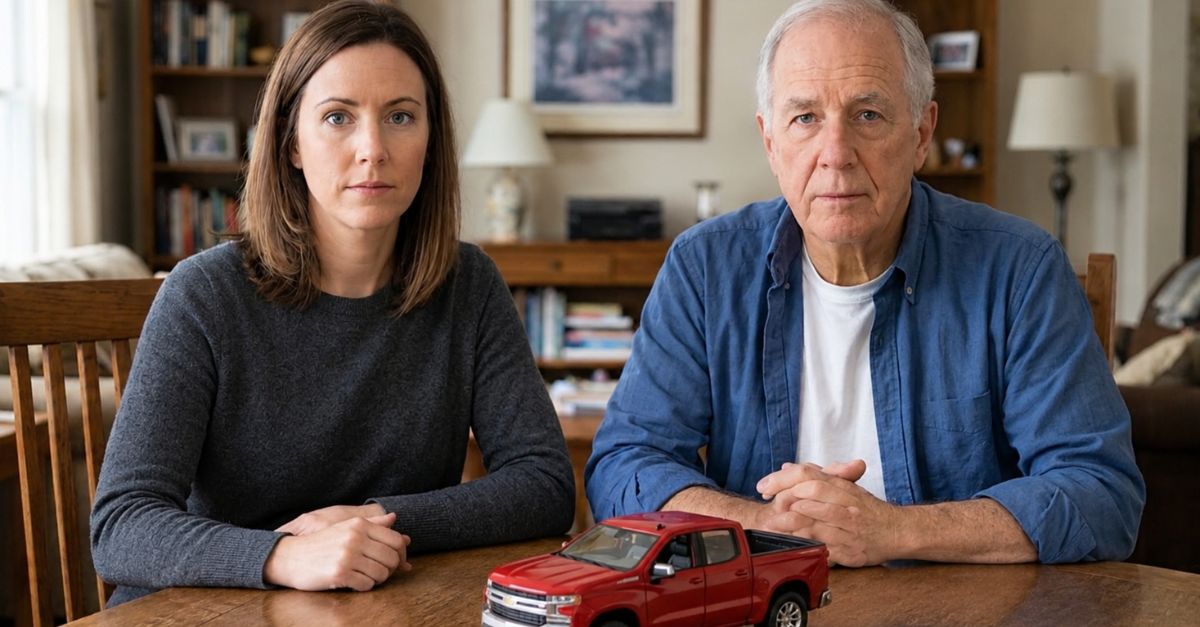
Family Portrait with a Toy Truck

My father wants me to cosign his new truck because he's retired and has little income. I want to, but it derail my own mortgage?


November 12, 2026 | Miles Brucker

My father wants me to cosign his new truck because he's retired and has little income. I want to, but it derail my own mortgage?


The Family Favor That Can Mess With Your Mortgage

When a retired parent, the person who raised you, asks you to cosign a truck loan, it's hard to say no. But cosigning isn't just a kind gesture. According to the Consumer Financial Protection Bureau, you would be legally responsible for the full loan if the main borrower stops paying, and not everyone can afford that risk.
Family Portrait with a Toy TruckFactinate

Advertisement

Your Financial Future Is Not Guaranteed

If you are planning to buy a home, that favor can come with real costs. Mortgage lenders look hard at your monthly debts, your credit, and your ability to repay. A truck loan with your name on it can affect all three, even if your father says he will handle every payment.
Two men in discussion over vehicle maintenance documents in a garage setting with trucks in the background.Gustavo Fring, Pexels

Advertisement

The Risk Is Unavoidable.

Cosigning your father’s new truck could absolutely hurt your mortgage plans, or at least make the process much tougher, pricier, or slower. The main problem is this: The loan can show up on your credit report as your debt. That can raise your debt-to-income ratio and drag down your credit if anything goes wrong.

White pickup truck parked at dusk with sunset skyJustin Wolff, Unsplash

Advertisement

What Cosigning Really Means

Cosigning means you are joining the loan contract with the borrower. The Federal Trade Commission says creditors can go after cosigners if the borrower does not pay. In plain terms, you are not just backing your father up. You are agreeing to be responsible for the truck loan.
a man and a woman sitting at a white tableCarrie Allen www.carrieallen.com, Unsplash

Advertisement

Your Name Goes On The Debt

This is the part many people miss. Even if you never drive the truck, never get the statements, and never make a payment, the loan can still appear on your credit reports. Mortgage underwriters do not care who uses the vehicle. They care who is legally on the hook for the debt.
two people sitting at a desk writing on a piece of paperKoda Bookkeeping, Unsplash

Advertisement

Mortgage Lenders Watch Your Debt-To-Income Ratio

One of the first things a mortgage lender checks is your debt-to-income ratio, or DTI. The CFPB explains that lenders compare your monthly debt payments to your gross monthly income to see whether you can handle a mortgage. A new truck payment can push that number up and shrink the mortgage you qualify for.
Mortgage broker and client sealing a deal with a handshake in a bright, modern office.RDNE Stock project, Pexels

Advertisement

What Counts In That Calculation

Your DTI usually includes debts like car loans, student loans, credit cards, and your expected mortgage payment. If you cosign the truck, that monthly payment may count against you. That can happen even if your father has not missed a single payment.
Close-up of a hand with pen analyzing financial rates on paper with a calculator and laptop nearby.RDNE Stock project, Pexels

Advertisement

Fannie Mae Has A Key Rule Here

Fannie Mae, one of the biggest names in the mortgage market, publishes lending rules many lenders follow. Its guide says a debt can sometimes be left out of your DTI if someone else has made the payments for at least 12 months from that person’s own account. That may sound helpful, but it is not automatic, and it does not help much if the truck loan is brand new.
The Colonial Revival headquarters of Fannie Mae, designed by architect Leon Chatelain, Jr. in 1956, located at 3900 Wisconsin Avenue, N.W., in the Cathedral Heights neighborhood of Washington, D.C.User:AgnosticPreachersKid, Wikimedia Commons

Advertisement

Freddie Mac Has Similar Standards

Freddie Mac allows something similar in certain cases. But lenders usually want solid proof, like 12 months of on-time payments from the other party and records showing you are not the one making them. If your father is only now shopping for a truck, that payment history will not be there when you apply for a mortgage.
Three individuals collaborating on financial documents during a business meeting.AI25.Studio  Studio, Pexels

Advertisement

Timing Can Change Everything

If you expect to apply for a mortgage in the next few months, cosigning now is especially risky. A new loan can hit your credit report quickly. That means mortgage lenders may see it before you even get to preapproval.
Shutterstock-2710599541, Mortgage Real Estate, woman hand using calculator to calculate home finance, accounting on bell, budget management. Doing finance, budgeting and tax calculation, monthly expensesgroviapoto, Shutterstock

Advertisement

A New Loan Can Also Trim Your Credit Score

Credit scores can be affected when you take on new debt. MyFICO says opening a new account can lower the average age of your accounts, and the hard inquiry from the application can matter too. The drop may be small, but even a small shift can matter when you are trying to get a mortgage.
Reversemortgageinternalfizkes, Shutterstock

Advertisement

Why A Few Points Can Matter A Lot

Mortgage rates are often tied to credit score ranges. If cosigning bumps you into a lower bracket, your rate could go up. Over the life of a mortgage, even a slightly higher rate can cost you thousands of dollars.
Hands using a calculator with real estate documents on a desk, indicating a financial transaction or meeting.RDNE Stock project, Pexels

Advertisement

The Biggest Risk Is Missed Payments

The truck payment may look affordable now, but retirement income can be tight. If your father misses a payment, that late mark can land on your credit reports too. The CFPB warns that late payments on a cosigned loan can hurt the cosigner’s credit just as much as the borrower’s.
Couple looking stressed over bills at kitchen tableVitaly Gariev, Unsplash

Advertisement

Repossession Would Not End The Problem

If the truck gets repossessed after a default, the lender could still come after the remaining balance if selling the truck does not cover the loan. As a cosigner, you could owe that leftover amount. That is one of the biggest risks, and it often gets overlooked.
Tow truck operator loading white GMC pickup truck on street in daytime.Jonathan  Reynaga, Pexels

Advertisement

Retirement Income Can Raise Extra Concerns

Your father being retired does not automatically make him a bad borrower, but limited income changes the picture. Lenders care about steady ability to repay. If his income is low enough that he needs a cosigner, that may be a sign the loan is already stretching his budget.
Elderly man with eyeglasses reviewing documents at a laptop. Indoor setting with natural light.SHVETS production, Pexels

Advertisement

Good Intentions Do Not Change The Math

You may trust your father completely. But lenders are not looking at family trust. They are looking at paperwork, debt, and ratios. On paper, a cosigned truck loan is still your liability.
Two men engaged in a business consultation, reviewing documents in a professional setting.Kampus Production, Pexels

Advertisement

Can You Tell The Mortgage Lender It Is Really His Debt

You can explain it, but that usually is not enough. Lenders work from written rules and documented payment records. Without the right proof, the truck payment may still count in your DTI and cut into how much you can borrow.
A financial advisor discusses paperwork with a client at a desk in a modern office.RDNE Stock project, Pexels

Advertisement

There Is One Narrow Exception

If your father has already made the payments for at least 12 months from his own account, some lenders using Fannie Mae or Freddie Mac rules may be able to leave that debt out of your DTI. But that only works if there is a clear payment history and the records to back it up. It does not fix the problem for a brand-new truck loan taken out right before a mortgage application.
Hands holding financial documents with calculator and laptop on office desk, business analysis scene.RDNE Stock project, Pexels

Advertisement

Do Not Overlook Insurance And Ownership Questions

Cosigning can also create confusion around title, registration, and insurance, depending on how the deal is set up and what the dealer requires. Ask whether your name will be on the title, not just the loan. That detail can affect liability and paperwork in ways people often miss.
Three business professionals in discussion over a contract in a modern office setting.www.kaboompics.com, Pexels

Advertisement

Could This Stop A Mortgage Entirely

In some cases, yes. If the truck payment pushes your DTI above a lender’s limit, you may no longer qualify for the mortgage amount you need. Even if you still qualify, you may get approved for less house than you expected.
Professionals examining documents in an office business meeting setup.Gustavo Fring, Pexels

Could It Just Make The Mortgage More Expensive

That is another very real outcome. A slightly lower credit score or a higher DTI can lead to worse loan pricing. So the truck loan might not kill your mortgage, but it can quietly make buying a home more expensive.
Miniature wooden house with keys and contract symbolizing real estate transactions.Atlantic Ambience, Pexels

Advertisement

What If You Already Cosigned

If the paperwork is already signed, talk to your mortgage lender as early as you can. Ask exactly how that loan will be treated in underwriting. If there is enough time, your father may be able to build the kind of payment history that helps later, but do not assume that will solve everything.
A couple discusses financial documents with their advisor, highlighting investment strategies.Mikhail Nilov, Pexels

Advertisement

Can You Be Removed Later

Usually, no, not just because the borrower asks. In most cases, the loan would need to be refinanced into your father’s name alone, if he qualifies, or paid off. That means getting out may depend on his future income and credit, not what you want.
Three professionals engaging in a business discussion over coffee in a modern café setting.Vitaly Gariev, Pexels

Advertisement

Safer Ways To Help Your Father

If you want to help without tying your credit to the truck, there are other options. You could help with a down payment, help him look for a cheaper vehicle, or shop around for lenders that work with retirees. You could also help him go through his budget and figure out what payment is actually manageable.
Salesman and client inspecting a pickup truck in a car dealership, discussing features.Gustavo Fring, Pexels

Advertisement

Ask These Questions Before You Sign Anything

Find out the exact monthly payment, total loan amount, interest rate, loan term, and whether extra products have been added to the deal. Ask how the payment fits into your father’s fixed income and what his backup plan is if costs go up. If the answers are vague, pay attention.
Shutterstock-2703657715, Accounting, finance or refund, mortgage and tax. Senior father with adult son in home reading documents for bank payment. copy spaceLysenko Andrii, Shutterstock

Advertisement

Watch Out For Dealership Pressure

Car financing offices are built to move deals along quickly. That can make cosigning sound normal and harmless. The FTC and CFPB both warn that cosigning is a serious legal step, so slow down and read every document before you agree to anything.
serious customer listen to salesman before signing document, making purchase in dealershipRoman Chazov, Shutterstock

Advertisement

When Saying No Is The Smart Financial Choice

Saying no to a parent can feel rough, especially when the request is wrapped up in family trust. But protecting your ability to buy a home is not selfish. It is a practical choice based on the real legal and credit risks that come with cosigning.
Shutterstock-2703883219, Young son and elderly father having conversation. White haired old man in his 60s or 70s sitting on sofa at home together with adult son, talking about life and sharing advice. Senior parents conceptStudio Romantic, Shutterstock

Advertisement

The Bottom Line Before You Sign

If you plan to apply for a mortgage soon, cosigning your retired father’s new truck is usually a high-risk move. It can raise your DTI, affect your credit score, and leave you exposed to payment problems you do not control. Before you sign, talk to a mortgage lender and make sure you know exactly what this family favor could cost you.
Senior father and adult son carefully going over documents in their kitchenMiljan Zivkovic, Shutterstock

Advertisement

READ MORE

Family Portrait with a Toy Truck

My father wants me to cosign his new truck because he's retired and has little income. I want to, but it derail my own mortgage?

When a retired parent asks you to cosign a truck loan, it can feel less like a financial decision and more like a loyalty test. But cosigning is not a symbolic gesture. According to the Consumer Financial Protection Bureau, a cosigner becomes legally responsible for repaying the full loan if the primary borrower does not pay.
November 12, 2026 Miles Brucker
Facebook   Internal

My wife wants to give our children their inheritance now to see them enjoy it. What could go wrong with early gifts?

It is easy to see the appeal of handing children part of their inheritance while you are still around to watch them use it. A down payment, student loans, or help with childcare can change a family’s trajectory much more at 35 than at 65. But once money leaves your control, a heartfelt gift can create tax headaches, family resentment, or even leave you short later in life.
November 12, 2026 Miles Brucker
Facebook   Internal

My employer says I have to repay training costs if I quit within three years. Can a job legally come with an exit fee?

You accept a new job, sign the onboarding packet, and then spot a clause that says you owe thousands of dollars if you leave too soon. It sounds like an exit fee, and for many workers it feels like a trap. The good news is that these clauses are not automatically enforceable just because an employer put them in writing.
November 12, 2026 Miles Brucker
The Deal Sounds Simple Until It Doesn't

My brother offered to buy my share of our family business, but wants to pay me from future profits. Is that a really risky deal?

In the short term, your brother buying your share of the family business, to be paid from future profits, keeps things fair, flexible, and low-drama, but it can also leave you holding far more risk than you think. The real question is not whether your brother means well. It's whether your financial plan still works if profits drop, get delayed, or never arrive.
November 12, 2026 Miles Brucker
Fct Internal + Fb Image

My landlord wants me to pay for a professional carpet cleaning before moving out, but the carpet is clean. Can he really force me?

If your landlord says you must pay for professional carpet cleaning before you move out, you are not alone. This is one of the most common move-out disputes renters run into, and it often shows up right when people are juggling deposits, movers, and deadlines. The frustrating part is that the answer is not the same in every state, and in some places the landlord’s demand may not hold up at all.
November 12, 2026 Miles Brucker
Claw Refund - Fb

My boss wants to deduct customer refunds from my sales commission. Can I lose money because someone changed their mind?

Few paychecks sting like a commission check that suddenly shrinks because a customer asked for a refund. It feels personal, but in most cases the answer depends less on fairness and more on your contract, your state’s wage laws, and whether the commission had already been “earned.” That is the key word that keeps coming up in court decisions, labor agency guidance, and attorney explanations.
November 12, 2026 Miles Brucker


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕