The Stock vs. Mortgage Showdown
This argument plays out at kitchen tables everywhere. One spouse wants the sure thing of paying down the mortgage faster. The other wants the higher long-term gains stocks have often delivered. The truth is simple: investing is not always better than becoming debt-free. The right answer depends on your interest rate, your comfort with risk, and how long you have before you need the money.
 Pavel Danilyuk, Pexels, Modified
Why This Debate Feels So Personal
A mortgage is not just another monthly bill. For most households, it is the biggest debt they have. Paying it off can feel like taking back control. On the other hand, watching money grow in the stock market over time can make extra mortgage payments feel like a missed chance.
What The Math Seems To Say At First
If your mortgage rate is 3% and you think your investments can earn 8% over time, investing can look like the obvious winner. Over very long periods, large U.S. stocks have historically returned about 10% a year before inflation, based on widely used market data and long-run studies. But averages can be misleading. Your real results depend on when you invest and when you need the money.
Mortgage Paydown Offers A Guaranteed Return
When you make an extra payment on a fixed-rate mortgage, the return is basically your mortgage interest rate. Every extra dollar cuts your principal and reduces future interest costs. Unlike stocks, that benefit is locked in as long as you keep the loan.
Stocks Offer Higher Potential, Not A Promise
The case for investing is based on odds, not certainty. The Securities and Exchange Commission has long warned that past performance does not guarantee future results, and market returns can swing hard over short and even medium stretches of time. That makes this more than a simple math problem.
Sequence Risk Is The Plot Twist Many Couples Miss
Sequence risk means the order of returns matters. If you put extra money into stocks and then need that money during a downturn, your result can be much worse than the nice long-term average suggests. Paying down a mortgage is quieter and less exciting, but the savings keep showing up no matter what Wall Street does.
 Vodafone x Rankin everyone.connected, Pexels
Today’s Mortgage Rate Changes Everything
Your mortgage rate matters a lot in this debate. Freddie Mac’s long-running Primary Mortgage Market Survey shows just how much average 30-year fixed rates have moved over time, from very low levels in 2021 to much higher levels in 2023 and 2024. Someone with a 2.75% mortgage is making a very different decision than someone with a 7% loan.
A Low-Rate Mortgage Tilts The Case Toward Investing
If your mortgage rate is very low, sending every spare dollar to the loan may not be the best move. A household with a fixed rate under 4% may reasonably decide that broad stock index funds have better long-term upside. But the key word there is expected.
A High-Rate Mortgage Makes Payoff More Attractive
Once mortgage rates get higher, the guaranteed return from paying extra gets a lot harder to ignore. Paying down a 6.5% or 7% mortgage is like earning that rate without market swings and without taxes on the savings. For many households, that is tough for stocks to beat on a risk-adjusted basis.
Tax Benefits Are Not What They Used To Be
For years, many homeowners defended keeping a mortgage because of the mortgage interest deduction. But after the Tax Cuts and Jobs Act of 2017 sharply raised the standard deduction, far fewer households itemize. The Tax Policy Center has reported that this greatly reduced the number of taxpayers who benefit from deducting mortgage interest.
That Means Your Real Mortgage Cost May Be Higher Than You Think
If you do not itemize, your mortgage interest is not giving you a tax break. In real life, that means a 6% mortgage may simply cost you 6%. That weakens one of the old arguments for dragging a mortgage out longer than needed.
Liquidity Is The Strongest Argument Against Going All In On Payoff
Home equity has value, but it is not easy to spend. Once extra cash goes into the house, getting it back usually means selling, doing a cash-out refinance, or taking a home equity loan. The Consumer Financial Protection Bureau warns borrowers to understand the costs and risks of tapping home equity, especially when rates are high.
 https://kaboompics.com/, Pexels
An Emergency Fund Comes Before Either Goal
Before you get aggressive about investing or paying down the mortgage, build a solid cash cushion. Most financial planners suggest keeping several months of essential expenses in emergency savings. Without that buffer, a job loss or surprise bill can push you into credit card debt, which is usually much more expensive than a mortgage.
Do Not Ignore Employer Match Money
If one of you gets a 401(k) match at work, that should usually be the first place extra cash goes. An employer match is immediate upside that is hard to beat anywhere else. Skipping it to make extra mortgage payments often means turning down free money.
 Rodrigo Rodrigues | WOLF A R T, Unsplash
High-Interest Debt Should Usually Be The Real First Target
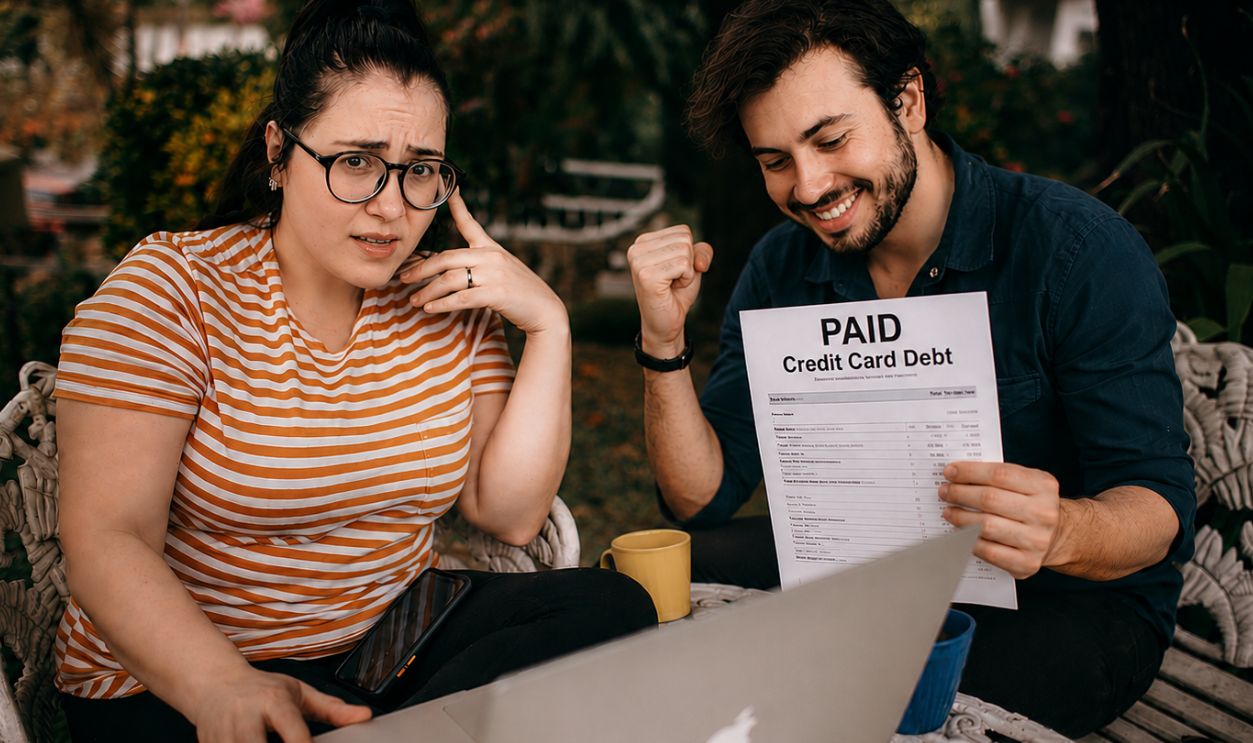
Credit card debt changes the whole discussion. Federal Reserve consumer credit data and lender disclosures show that credit card rates are usually far higher than mortgage rates. If you are carrying revolving debt at double-digit rates, paying extra on the mortgage or investing heavily is often the wrong first step.
 Helena Lopes, Pexels, Modified
Your Time Horizon Matters More Than Most People Realize
If retirement is decades away, investing has more time to recover from market drops. If retirement is close, the certainty of lowering housing costs can be extremely valuable. A paid-off or nearly paid-off home can make retirement income planning much less stressful.
Behavior Can Beat Math
Personal finance is not just about the highest expected return on paper. Some people sleep better when they are cutting debt and lowering their monthly bills. Others are steady investors who can handle market swings without panic-selling, which makes an investing-first strategy more realistic for them.
Being Debt-Free Has A Psychological Return Too
That emotional payoff is real, even if it does not fit neatly into a calculator. Research from the CFPB and experts in behavioral finance has repeatedly shown that financial stress affects well-being and decision-making. If paying down the mortgage meaningfully lowers your stress, that matters.
But Investing Builds Flexibility And Wealth
Money in a taxable brokerage account can be used for all kinds of goals before the mortgage is gone. It can help pay for college, cover an early retirement, or cushion a major life change. Extra principal locked inside a house is less flexible, even if it is doing useful work.
There Is A Middle Path That Often Works Best
This does not have to be an all-or-nothing fight. Many couples split extra cash between investing and making additional mortgage payments. That way, you get some market upside while also cutting debt and keeping the peace at home.
Run The Numbers With Your Actual Mortgage
Use your real loan balance, fixed rate, and monthly payment to estimate how much extra payments would save you. Then compare that with realistic investing assumptions, not dream numbers. The gap between a 3% mortgage and a 7% mortgage can completely change the answer.
Use Conservative Return Assumptions
Do not assume the market will hand you 10% every year just because long-run averages exist. Vanguard and other major firms regularly publish forward-looking market assumptions that are often lower than historical U.S. stock returns. Building around more cautious expectations can keep you from taking on too much risk.
Watch Out For Concentrated Bets
If your husband says every spare dollar should go into stocks, the next question is which stocks. Broad, low-cost index funds are very different from piling into a few trendy companies. Concentrated bets raise the odds that the investing plan goes badly and leaves you wishing you had paid down the mortgage instead.
Retirement Accounts And Taxable Accounts Are Not The Same
Where you invest matters almost as much as whether you invest. Tax-advantaged retirement accounts can improve long-term results through tax deferral or tax-free growth, while taxable accounts may create yearly tax drag. To compare investing with mortgage prepayment fairly, you need to account for that.
Couples Should Also Talk About Job Stability
A household with steady dual incomes can usually take more investment risk than one with uneven earnings or commission-based pay. If your income feels shaky, lowering required monthly expenses can be especially valuable. A smaller mortgage balance gives you more room to breathe when life gets messy.
What A Sensible Priority Order Often Looks Like
For many households, the best order is straightforward. First, build an emergency fund and grab any employer retirement match. Next, pay off high-interest debt. After that, decide whether extra cash should lean more toward investing or mortgage prepayment based on your interest rate, goals, and risk tolerance.
So, Is Investing Always Better Than Becoming Debt-Free
No. Investing often has the higher expected return over long stretches, but extra mortgage payments offer a guaranteed return, lower financial stress, and a smaller required monthly budget. If your mortgage rate is low and your timeline is long, stocks may deserve more of your extra cash. If your rate is high or peace of mind matters most, becoming debt-free can be a very smart move.
The Best Answer Is The One You Can Stick With
The flashiest plan is not always the best one. The right strategy fits both your numbers and your nerves, and it is one both spouses can stick with through bull markets, bear markets, and real life. If you want a practical compromise with less regret, splitting spare dollars between broad index investing and faster mortgage payoff may be the best move of all.