Your Spouse’s Credit Can Matter More Than He Thinks
If your husband says his bad credit doesn't matter because your score is great, he is only half right. Credit scores belong to individuals, not married couples, so marriage does not automatically combine your credit histories. But the second you apply together for a loan, credit card, or mortgage, his lower score can affect what you qualify for and how much you pay.
Marriage Does Not Create a Joint Credit Score
One of the biggest money myths is that married couples share one credit report. They do not. The Consumer Financial Protection Bureau says there is no joint credit report or joint credit score just because two people got married.
Your Reports Stay Separate Until You Borrow Together
Your credit report stays in your name, and his stays in his. That means his missed payments, high balances, or collections do not land on your report just because you said “I do.” The real risk starts when you open joint accounts or co-sign debt, because those accounts can show up on both reports.
Joint Accounts Are Where the Risk Starts
If both your names are on a credit card or loan, both of you are legally on the hook for the debt. The CFPB says that if one spouse misses payments on a joint account, that late payment can be reported on both spouses’ credit reports. One person’s mistake can quickly become both people’s problem.
Authorized Users Are Different, but Not Risk-Free
There is a big difference between a joint account holder and an authorized user. An authorized user can use the card but usually is not legally responsible for the bill. Still, many card issuers report authorized user accounts to the credit bureaus, so late payments or high balances can still affect that user’s credit profile.
Lenders Often Focus on the Lower Score
This is where your great credit can lose some of its edge. When couples apply together for major credit, lenders may look at both credit profiles and price the loan based on the riskier borrower. With mortgages, that can get expensive fast.
Mortgage Rules Can Be Tough on Couples
Fannie Mae says that when there are multiple borrowers, the lender uses a representative credit score for each borrower and then typically uses the lower score for underwriting. Freddie Mac says that for loans with more than one borrower, the lender generally uses the lowest middle credit score. In plain English, one spouse’s low score can mean a higher mortgage rate or even a denial.
A Lower Score Can Raise Your Monthly Payment
This is not just a technical issue. A weaker borrower profile can mean a higher interest rate, tougher loan terms, or a smaller approved amount. Over a 15-year or 30-year mortgage, that can add up to thousands, or even tens of thousands, in extra costs.

Credit Card Applications Can Get Complicated
Joint credit card accounts are not as common as they used to be, but some issuers still offer them. If you apply together, the lender can review both credit files and both incomes. A spouse with weak credit can lower your approval odds or leave you with a lower credit limit and worse terms.
Auto Loans Can Work the Same Way
Many couples apply together for a car loan to improve their chances of approval or to borrow more. That can help if one person has limited income, but it can backfire if the second borrower has poor credit. You may still get approved, but at a higher rate than the stronger borrower might have gotten alone.
Your Good Credit Does Not Cancel Out His Bad Credit
This is the part that catches a lot of married couples off guard. One spouse’s excellent score does not wipe away the other spouse’s late payments, charge-offs, or high credit use. Lenders do not blend your scores into one nice marital average.
Co-Signing Is One of the Fastest Ways to Share the Damage
If you co-sign for your husband, you are telling the lender you will pay if he does not. That account can appear on your credit reports, and missed payments can hurt your score. The Federal Trade Commission has long warned that co-signing is not just a favor. It is a serious legal commitment.
Even One Missed Payment Can Hurt
Payment history is the biggest factor in most credit scoring models. FICO says it is the most important part of its scoring formula. So if a joint or co-signed account goes late, the hit can be sharp and can stick around for years.
High Balances on Shared Cards Can Drag You Down Too
Credit utilization, or how much revolving credit you use compared with your limits, is another major factor. If your husband runs up a balance on a joint card, that higher utilization can appear on your report too. Even when payments are on time, a maxed-out card can still weaken a strong score.
 Srdjan Randjelovic, Shutterstock
Debt Does Not Always Transfer, but Liability Can
In most cases, one spouse is not automatically responsible for the other spouse’s individual debt just because they are married. But there are exceptions, especially when both spouses signed for the debt or when state law applies. That is where things can get costly in a hurry.
Community Property States Add Another Twist
According to the CFPB, community property states may treat debts taken on during marriage differently. The rules vary by state, but marital debts and obligations can affect both spouses more directly in places like California, Texas, Arizona, and others. That does not mean your spouse’s credit report becomes yours, but it can make debt responsibility more complicated.
Lenders Look Beyond the Score
Credit scores get most of the attention, but lenders also look at income, debt-to-income ratio, cash reserves, and recent payment history. A spouse with bad credit may also have more debt, which can weaken your joint application. Sometimes the score is only part of the problem.
You Might Be Better Off Applying Alone
If you can qualify using only your own income and assets, applying alone may help you avoid being pulled down by a spouse’s bad credit. This is common with credit cards and sometimes with auto loans or mortgages. But it only works if the lender does not need the second spouse’s income to approve the application.
 Marcos Mesa Sam Wordley, Shutterstock
Mortgage Rules Can Limit That Strategy
Applying alone for a mortgage can protect you from a spouse’s lower score, but there are limits. You may qualify for less based on one income, and lenders still review debts that affect your ability to repay. In community property states, some debts of a non-borrowing spouse may still have to be counted in underwriting.
You Should Check All Three Credit Reports
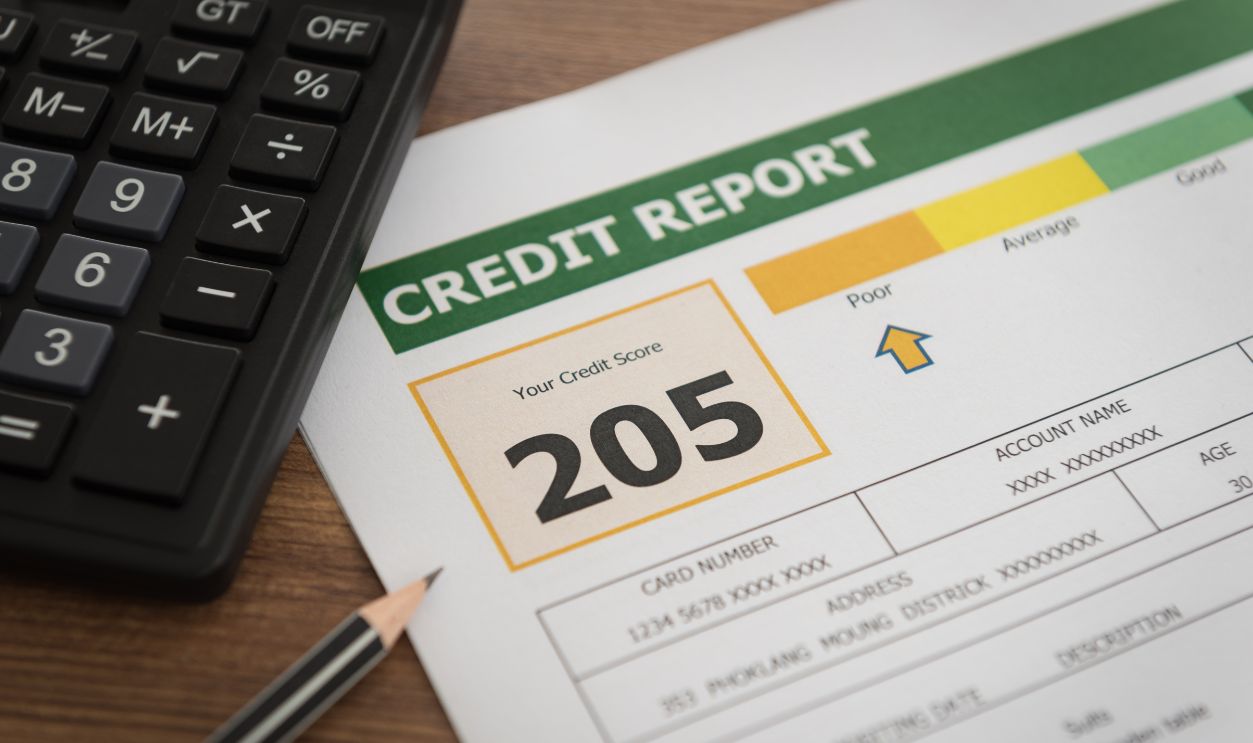
If you want to know how much risk your spouse’s credit really creates, start with the facts. Federal law lets consumers get free weekly credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com. Looking at all three can uncover missed payments, collections, or errors that are quietly wrecking your plans.
Errors Are More Common Than People Realize
The FTC reported in a 2012 study that one in five consumers had an error on at least one credit report. Not every mistake changes a score, but some absolutely do. If your husband’s score seems lower than it should be, disputing an error could make a real difference before you apply together.
Repair Starts With the Basics
There is no magic fix, no matter what flashy ads say. The most dependable ways to improve credit are simple: pay bills on time, lower credit card balances, avoid taking on debt you do not need, and correct reporting errors. Guidance from FICO and the CFPB keeps coming back to those same basics.
Closing Old Accounts Can Backfire
Some people think the fastest way to clean up credit is to close old cards. That can actually hurt. Closing accounts may cut your total available credit and push your utilization higher. Over time, it can also reduce the average age of active accounts, which may work against someone trying to rebuild credit.
Do Not Ignore the Emotional Side of the Money Fight
Behind the numbers, there is often a relationship problem sitting right there in the open. One spouse may see credit as a boring technical detail, while the other sees it as the key to buying a house, getting a car, or sleeping better at night. A direct talk before you apply for anything together can head off resentment and expensive surprises.
Set Rules Before You Mix Debt
Couples usually do better when they set a few ground rules early. Decide whether either of you can open joint accounts, how balances will be paid, and how often you will review statements and credit reports. A simple system can stop one person’s bad habits from turning into a household mess.
A Bad Score Can Affect More Than Borrowing
Depending on the situation, poor credit can create problems beyond loans. Insurers in many states use credit-based insurance scores, and landlords may check credit when screening renters. So even if your strong score protects you in one area, your spouse’s weak credit can still complicate big household decisions.
The Bottom Line Is Pretty Simple
Your husband is right that marriage alone does not fuse your credit into one number. But he is wrong if he thinks his score cannot affect both of you. The moment you borrow together, co-sign, or depend on his profile in a major money decision, bad credit can become a shared and expensive problem.
The Smart Move Is to Plan Before You Apply
If you are thinking about a home purchase, car loan, or new credit card, pull both credit reports first and compare scores, debts, and errors. Then decide whether to apply jointly or individually based on income, state law, and the lender’s rules. A little planning now can save you a lot of money later.