The Argument A Lot Of Families Are Having
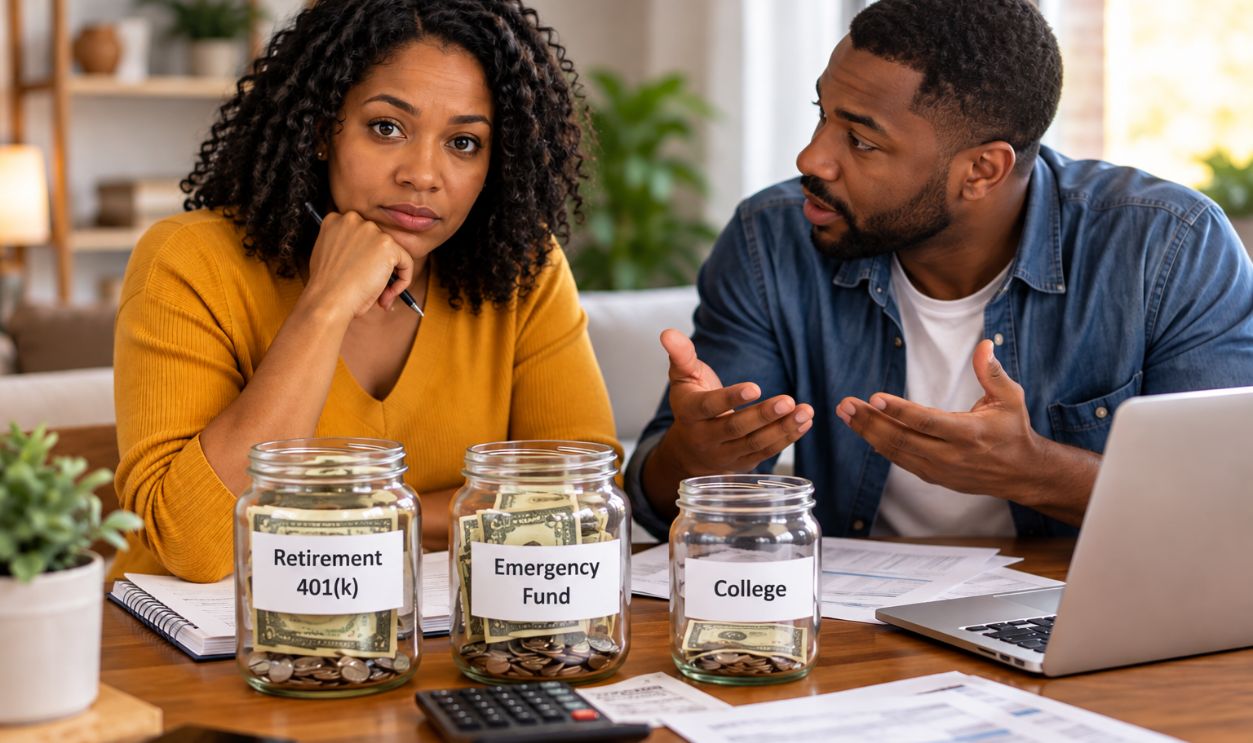
“They can just borrow for college” can sound practical when tuition keeps rising and retirement savings still need attention. But for a lot of families, that idea turns into a real fight. The question is whether pushing the cost onto student loans is a smart trade or just an expensive shortcut.
Why This Debate Feels So Urgent Right Now
College is still expensive, even after years of complaints about tuition. The College Board reported that average published tuition and fees for 2024–25 were $11,610 at in-state public four-year schools and $43,350 at private nonprofit four-year schools. Those price tags help explain why many parents wonder whether saving for college is even worth it.
The Price Tag Is Bigger Than Tuition Alone
Tuition is only part of the bill. Room and board, books, transportation, and other costs can drive the total price much higher. So when families borrow, they are often borrowing for far more than classes, and that can make debt grow faster than expected.
Borrowing For College Is Common, But That Does Not Make It Cheap
Federal student loans are a normal part of paying for college in the United States. According to the College Board, bachelor’s degree recipients who borrowed in 2022–23 graduated with average debt of about $29,300. That is a heavy monthly bill for someone just starting adult life.
What Students Can Actually Borrow On Their Own
There is one key detail many parents miss. Dependent undergraduate students have federal borrowing limits of $5,500 for the first year, $6,500 for the second year, and $7,500 for the third year and beyond, with a typical total limit of $31,000. Those limits come straight from the U.S. Department of Education, and in many cases they do not come close to covering four years of college.
That Means Parents Often End Up In The Loan Story Anyway
If college costs are higher than what a student can borrow through regular federal loans, the gap does not magically go away. Families often turn to Parent PLUS loans, private loans, payment plans, or savings. So “the kids can borrow” often just delays the moment when parents realize they may still be part of the bill.
 cottonbro studio, Pexels, Modified
Parent PLUS Loans Can Be A Costly Back Door
Parent PLUS loans let parents borrow for a child’s education, but they come with federal loan fees and interest charges. For loans first disbursed on or after July 1, 2024 and before July 1, 2025, the interest rate is 9.08%, according to the Department of Education. At that rate, helping with college can turn into years of expensive repayment.
 Jelena Stanojkovic, Shutterstock
Private Loans Raise The Stakes Even More
When federal loans are not enough, some families look to private lenders. The Consumer Financial Protection Bureau has warned that private student loans usually offer fewer protections than federal loans. That can mean less flexible repayment and fewer safety nets if a graduate runs into financial trouble.
The Monthly Payment Can Shape A Young Adult’s Life
Student debt does not stay in the background. The CFPB has noted that student loan burdens can affect cash flow and big money choices. In real life, that can mean putting off moving out, buying a home later, or saving less for retirement during the years when compounding matters most.
 https://kaboompics.com/, Pexels
Research Has Linked Student Debt To Delayed Milestones
The Federal Reserve has published research showing that student debt can affect homeownership and household finances more broadly. The exact effect depends on the borrower and the economy, but the broad point is clear. Loan balances can shape when and how young adults build wealth.
There Is Also A Risk In Not Saving Anything
If parents save nothing, they give up one of the few flexible tools they control before college begins. Savings can cut down on borrowing, cover gaps that show up later, or be used elsewhere if plans change. Having no savings at all can leave a family with fewer choices right when they need them most.
But Your Husband Is Not Completely Wrong Either
There is an uncomfortable truth here. Students can borrow for school in ways parents cannot borrow for retirement. Financial planners and firms like Fidelity often stress that retirement should usually come before college savings if a family truly cannot do both.
Retirement Comes First For A Reason
Students may have access to federal loans, grants, scholarships, work-study, and lower-cost schools. Older adults do not get a similar menu of help for retirement. If parents stretch too far to pay for college, they may end up needing support from the same children they were trying to help.
The Better Question Is How Much To Save
This debate is often framed like an all-or-nothing choice, but that is rarely the best approach. Families do not need to cover every semester for saving to matter. Even a modest amount can reduce borrowing, lower stress, and give students more breathing room after graduation.
Why A 529 Plan Usually Enters The Conversation
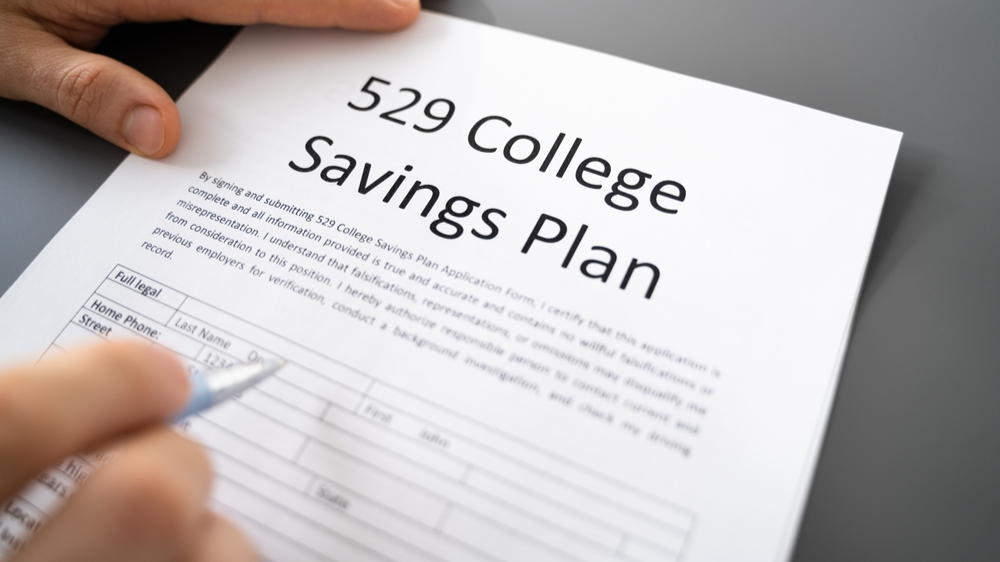
For many families, the main college savings tool is a 529 plan. These state-sponsored education savings plans let earnings grow tax-free, and withdrawals stay tax-free when used for qualified education expenses. The SEC and other official sources have long described them as a core option for college savers.
Recent Rule Changes Made 529 Plans More Flexible
One reason some parents hesitate to save is the fear that the money will be stuck if a child does not need it for college. The SECURE 2.0 Act, signed in December 2022, created a new option that starting in 2024 can allow certain unused 529 funds to be rolled into a Roth IRA for the beneficiary, subject to limits and conditions. That makes the fear of over-saving a little less intimidating.
 Hadayeva Sviatlana, Shutterstock
There Are Important Fine Print Rules On Those Rollovers
The rollover option helps, but it is not unlimited. IRS guidance says there is a lifetime maximum of $35,000, and annual Roth IRA contribution limits still apply. The 529 account also has to have been open for at least 15 years, so this is a backup option, not a free-for-all.
Saving Something Can Also Help With School Choice
Families with at least some money set aside usually have more room to compare schools based on fit instead of panic. They may also be more willing to walk away from the highest-cost option if the debt math does not work. Cash on hand gives a family options, and options matter.
The FAFSA Rules Matter Here Too
Many parents worry that saving will crush financial aid eligibility. In practice, parent-owned 529 plans are treated as parental assets on the FAFSA, and parental assets are usually assessed at a much lower rate than student assets. So saving in a parent-owned account is often less damaging to aid than families fear.
Grandparent 529 Plans Used To Be Trickier
For years, distributions from grandparent-owned 529 plans could complicate aid calculations. But FAFSA simplification changed several rules, and recent guidance has eased that concern for many families. That is one more reason to check current rules instead of relying on old advice.
Scholarships Are Great, But They Are Not A Full Strategy
It is tempting to assume merit aid will solve everything. Sometimes it does, but scholarships are uncertain and often highly competitive. Building a plan around money a student has not won yet is a risky bet.
Community College And In-State Schools Can Change The Math
Your husband’s argument gets less risky if the family is aiming for lower-cost schools from the start. Beginning at community college or choosing an in-state public university can sharply reduce borrowing needs. In that situation, a smaller college fund may make perfect sense.
 Harrison Keely, Wikimedia Commons
A Sensible Plan Balances Three Goals At Once
The strongest college funding plans usually balance retirement, current cash flow, and future education costs all at once. That might mean getting the full employer retirement match first, paying down high-interest debt, and then putting some money into a 529. It is not flashy, but it is practical.
What If You Truly Cannot Save Much Right Now
If money is tight, this is not a character test. Even a small automatic contribution can build the habit and create at least a little cushion over time. The goal is not perfection. The goal is to reduce future borrowing where you can.
 https://kaboompics.com/, Pexels
What Parents Should Avoid
One of the biggest mistakes is draining retirement accounts or taking on large Parent PLUS balances without a clear repayment plan. Another is assuming a teenager can easily handle five figures of debt just because a lot of people do it. Common does not always mean safe.
 Vodafone x Rankin everyone.connected, Pexels
So, Is He Right
Not entirely. Kids can borrow, but only up to a point, and that debt can affect their finances for years. A better answer is usually to save what you reasonably can for college while protecting retirement first.
The Practical Middle Ground Most Families Need
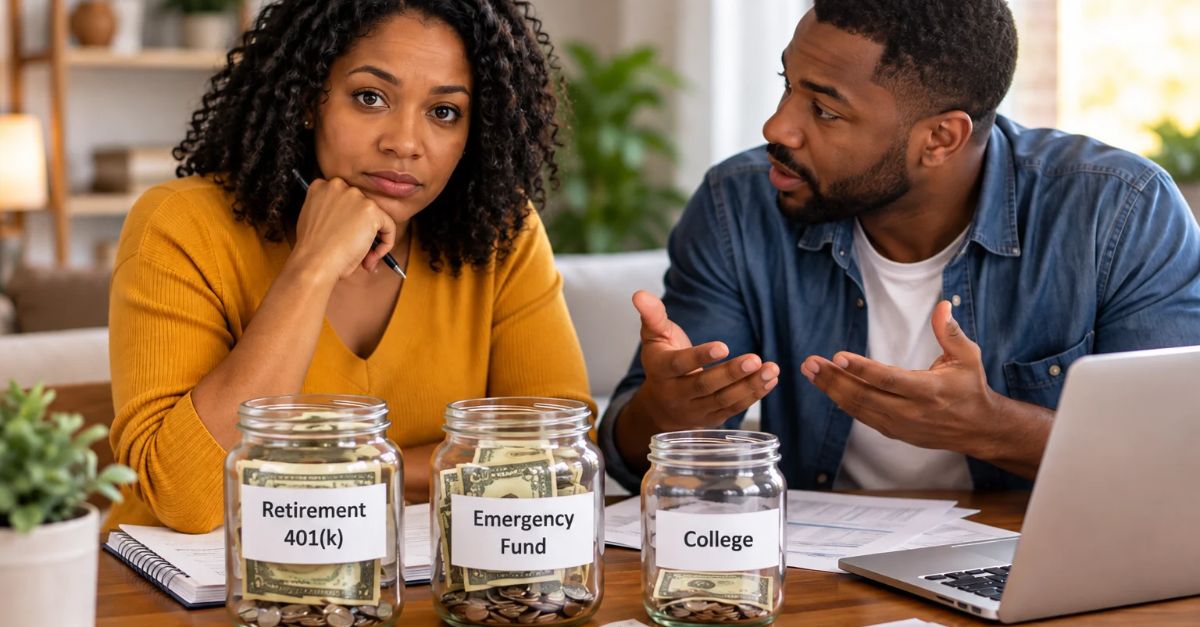
If you and your husband are stuck, try this rule of thumb. Put retirement contributions first at least up to any employer match, keep an emergency fund, and then save something for college, even if it is modest. That approach respects the reality of high tuition without casually passing a long debt burden to your kids.