The Family Home Can Come With Strings Attached
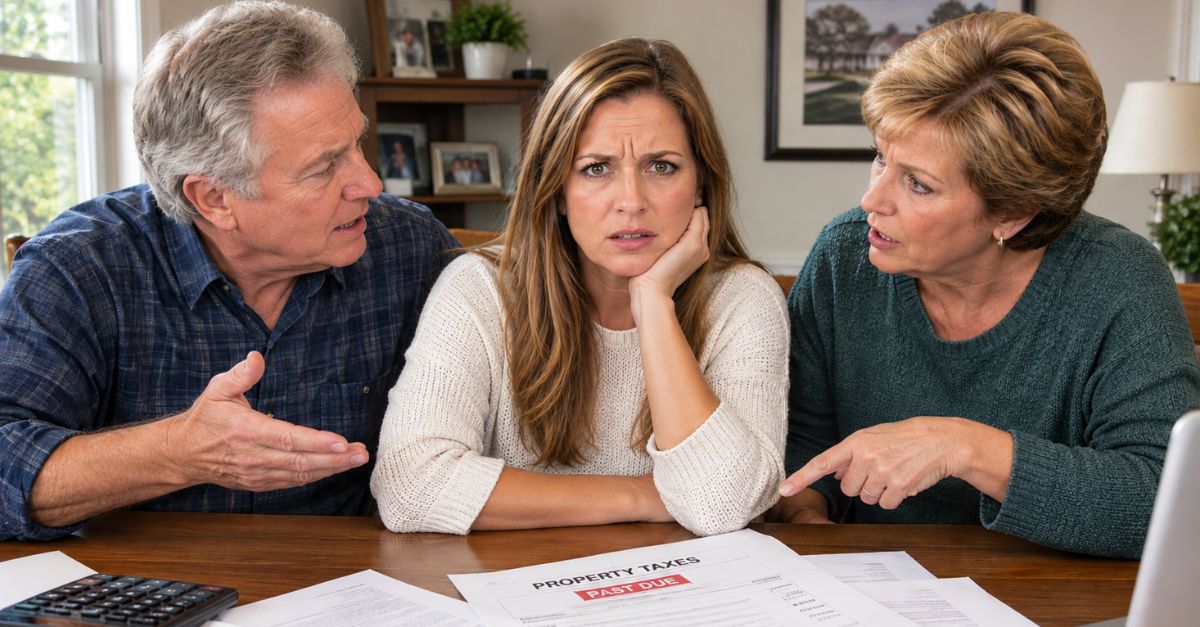
If your parents want you to pay their property taxes now because you might inherit the house later, it may not feel much like a gift. It can feel like a bill tied to a promise. That raises a basic question: are you helping family, or paying to protect an asset you do not actually own yet?
An Inheritance Is Not A Done Deal
A future inheritance can sound certain in family talks, but legally it often is not. Parents can change their wills, spend their savings, refinance the house, or face medical and long-term care costs that shrink the estate. Until the home is actually transferred, your tax payments may rest more on trust than on any real legal right.
Property Taxes Are A Serious Expense
Property taxes are often one of the biggest ongoing costs of owning a home, especially in expensive areas. The Tax Foundation reported that in fiscal year 2022, local property tax collections in the United States totaled $768 billion, or about 2.9% of personal income. So this is not some small favor. Paying that bill for years could put real pressure on your own finances.
Some Places Hit Harder Than Others
The Tax Foundation’s review of Census Bureau data found that some states lean much more heavily on property taxes than others. New Jersey, New Hampshire, Connecticut, Vermont, and Illinois ranked among the highest in property taxes as a share of owner-occupied housing value. If your parents live in a high-tax area, “just helping with taxes” can turn into a major yearly burden.
The House May Come Later, But The Money Leaves Now
This is the heart of the issue. You would be paying real cash today for a possible asset down the road. If your parents live another 10 or 20 years, the total could be huge. And that is before insurance, repairs, or emergency costs start creeping into the arrangement too.
 https://kaboompics.com/, Pexels
The IRS Has Rules On Gifts
If you pay someone else’s bills, the tax code may treat that as a gift. The IRS says the annual gift tax exclusion is indexed for inflation and rose to $18,000 per recipient for 2024 and $19,000 for 2025. That does not automatically mean you will owe gift tax, but it does mean large ongoing payments should not be handled casually.
Most Families Will Not Owe Gift Tax, But Records Still Matter
The federal lifetime gift and estate tax exemption is much higher than the annual exclusion, which is why most families never actually pay gift tax. But reporting rules can still kick in when gifts go over the yearly amount. If you are paying thousands in property taxes for your parents, it makes sense to ask a tax professional how those payments should be handled and documented.
Medicaid Is Where Things Often Get Complicated
This is the part many families do not see coming. If your parents later need Medicaid to help cover long-term care, the house and earlier transfers can become part of a much bigger financial review. Medicaid rules vary by state, and the idea that “the house will be yours anyway” can run straight into eligibility rules and estate recovery.
Estate Recovery Can Upend The Plan
Medicaid.gov explains that states must seek recovery from the estates of certain deceased Medicaid beneficiaries for benefits correctly paid, especially long-term care services for people age 55 or older. In plain terms, a house you thought would pass to you can become a target after a parent dies. That means you could pay the taxes for years and still not receive the full value you expected.
The Five-Year Look-Back Matters
Medicaid also reviews asset transfers made before someone applies for long-term care coverage. The American Council on Aging explains that in most states there is a five-year look-back period for nursing home Medicaid and many home and community-based services waivers. If the home is transferred the wrong way or too late, the family may trigger a penalty period instead of protecting the asset.
A Verbal Promise Is Not A Plan
Many adult children say yes because the request feels simple and morally clear. But whether it is fair comes down to details, and details should be written down. If your parents want you to carry the property tax bill, they should be willing to discuss a formal plan with an estate attorney, not just rely on a family promise.
There Are Ways To Make It Fairer
One option is to treat your payments as a loan and document them carefully. Another is to receive a recorded ownership interest in the property now, though that can create tax, legal, and Medicaid issues that need professional advice. A third option is to put the inheritance arrangement in writing so your contribution is at least reflected in the estate plan.
Adding Your Name To The Deed Is Not A Quick Fix
Putting a child on the deed can sound neat and simple, but it can create a lot of problems. It may expose the house to your creditors, change the tax picture later, and complicate Medicaid planning. It can also stir up family tension fast, especially if siblings are involved or your parents later want to sell or refinance.
Capital Gains Can Sneak Up On You
Inherited property often gets a stepped-up basis, which can reduce taxable capital gains when heirs sell. The IRS explains that the basis of property inherited from a decedent is generally the fair market value at the date of death or the alternate valuation date if elected. If your name goes on the house too early as a gift, you may lose part of that tax break.
A Step-Up In Basis Can Save Real Money
If your parents bought the home decades ago for much less than it is worth now, that tax rule can matter a lot. If you inherit the house at death, your basis may reset closer to current market value, which can sharply reduce the gain if you sell. But if you receive part of the house as a lifetime gift, you may also receive part of the old basis, which can lead to a bigger tax bill later.
Fairness Depends On The Whole Money Picture
If your parents are house-rich but cash-poor, asking for help with taxes may be understandable. But if they also have solid savings, retirement income, or other assets, the request may not be as reasonable as it first sounds. Fairness is not just about the house. It is also about whether this setup strains your budget while protecting theirs.
 Monkey Business Images, Shutterstock
Ask How Long This Is Supposed To Last
One of the biggest details is also one of the easiest to overlook: duration. Helping for one year is very different from signing up for an open-ended bill that could last a decade or more. Before you agree, ask exactly how much the taxes are, how often they tend to rise, and what happens if you need to stop paying.
 Parinya.Maneenate, Shutterstock
Be Clear About What Else You Are Paying For
Property taxes rarely stay in their own lane. Once a child starts helping, the talks often spread to insurance, utilities, roof work, accessibility upgrades, or surprise plumbing repairs. If you are considering this arrangement, be clear about whether you are paying only the taxes or stepping into a bigger role in supporting the home.
Siblings Can Turn This Into A Mess
Few things spark estate fights faster than unequal help during a parent’s lifetime. If one child pays property taxes for years and the estate is later split evenly, resentment is almost built in. A fair setup should spell out whether your payments will be reimbursed, credited, or balanced against what other heirs receive.
Your Own Financial Goals Count
Helping parents may feel like the right thing to do, but it should not wreck your emergency fund, retirement savings, or plans to buy a home. Property taxes are recurring, which makes them especially risky if your own finances are already stretched. An arrangement is not fair if it protects one generation by throwing the other off course.
There May Be Better Ways To Lower The Bill
Before you start writing checks, find out whether your parents qualify for relief programs. Many states and local governments offer exemptions, abatements, deferrals, or circuit breaker programs for older adults, veterans, or lower-income homeowners. The National Council on Aging notes that benefits screening can help older adults find programs that reduce housing and tax costs.
A Reverse Mortgage Might Come Up
For some families, a reverse mortgage is another way to tap home equity instead of asking a child to cover property taxes. But this is not a casual move. It comes with costs, duties, and risks. It may ease cash flow now while cutting into a future inheritance, so it needs careful review before anyone treats it like an easy answer.
If You Help, Keep A Paper Trail
Save records of every payment, each tax bill, and any written agreement with your parents. That paperwork can matter if siblings question the arrangement later or if the estate needs to sort out reimbursements and credits. It also gives your lawyer or tax preparer something stronger than memory to work with.
A Written Agreement Can Prevent Bigger Fights Later
This does not have to feel harsh. A simple written agreement can say what you are paying, whether it is a gift or a loan, whether you get any ownership interest, and what happens if the home is sold before your parents die. Clear terms now can head off painful family disputes later.
When This Arrangement Might Be Fair
It may be fair if you can easily afford it, the amount is clear, siblings know about it, and there is solid legal planning behind the promise. It also helps if your parents have limited cash flow and the house is likely to pass to you under a documented estate plan. In that situation, paying the taxes may be more like preserving an asset you are reasonably likely to receive.
When It Probably Is Not Fair
It is probably not fair if the promise is vague, your parents could cover the taxes themselves, or the arrangement puts your own finances at risk. It is also dangerous if Medicaid, debt, remarriage, sibling conflict, or a possible sale could derail the inheritance. A maybe in the future is a weak trade for a real bill right now.
The Bottom Line
If your parents expect you to pay their property taxes because you may someday inherit the house, do not answer with guilt alone. Answer with math, legal paperwork, and a clear look at tax and Medicaid issues. Family loyalty matters, but when a house is involved, fairness usually starts on paper.