The Budget May Be Hiding Better Options
When money gets tight, families often cut groceries, skip prescriptions, or postpone medical care because those expenses seem easier to control. Before making choices that could harm your health, take a closer look at your bills. Some may be negotiable, incorrect, unnecessary, or eligible for assistance.
Here's what to look for.
Streaming Services Can Multiply
A few inexpensive streaming subscriptions can quietly turn into a cable-sized monthly bill. Review every service, including those billed through app stores, smart televisions, internet providers, and retailers, because forgotten free trials and duplicate subscriptions are remarkably good at hiding.
Rotate Instead Of Collecting
Cancel services that are rarely used, rotate subscriptions instead of keeping them all year, and downgrade premium plans. Streaming companies may also offer cheaper ad-supported tiers, bundles, student discounts, or temporary retention offers when customers attempt to cancel.
 LinkedIn Sales Navigator, Pexels
Examine The Cable Bill
Cable and satellite bills often contain equipment rentals, regional sports charges, broadcast fees, and premium channels that customers stopped watching years ago. Asking for an itemized explanation can expose costs that were barely noticeable when the original promotional price was advertised.
 https://kaboompics.com/, Pexels
Ask For A Smaller Package
Call the provider’s retention department and ask about current promotions, smaller packages, returned equipment, or a service without premium channels. Compare the final price after taxes and fees, since an impressive introductory offer can become much less impressive at checkout.
Review Every Cellphone Line
Many households remain on outdated cellphone plans long after cheaper options become available. Review the number of lines, device payments, insurance, hotspot allowances, international features, and data usage before assuming the existing plan is still competitive.
Lifeline May Reduce The Cost
Lower-cost carriers may use major wireless networks, although coverage and customer service should be checked locally. Eligible low-income households may also qualify for the federal Lifeline program, which can reduce the cost of phone or qualifying internet service.
Check The Real Internet Price
Internet providers may raise prices when introductory promotions expire, leaving longtime customers paying more than new subscribers. Ask for the current nonpromotional price, review equipment rental charges, and check whether the household is paying for speeds it rarely needs.
 https://kaboompics.com/, Pexels
The ACP Has Ended
The federal Affordable Connectivity Program ended in 2024, so advertisements suggesting it remains available should be treated cautiously. However, Lifeline continues, and some providers, cities, schools, and nonprofit organizations offer separate low-cost internet programs for qualifying households.
Recheck Security Monitoring
Professional monitoring can be valuable, but the bill may include financed equipment, camera storage, maintenance plans, or features nobody uses. Read the original agreement before canceling because some systems come with minimum terms, early termination charges, or equipment balances.
A Cheaper Security Tier May Exist
Ask whether the provider offers a lower monitoring tier, loyalty rate, temporary hardship arrangement, or self-monitoring option. Homeowners should also check whether changing the service affects an insurance discount before shutting everything off.
Find The Forgotten Gym Charges
Gym memberships are famous for surviving long after the workouts stop. Check bank and credit-card statements for annual maintenance fees, personal training charges, family add-ons, locker rentals, and memberships that were supposedly frozen but quietly resumed.
Cancel The Membership Properly
Request cancellation instructions in writing and follow the contract’s required process. Some facilities may offer a cheaper plan, hardship freeze, senior rate, employer discount, or community membership, but saving money only works if the old charge actually disappears.
Storage Can Cost More Than The Stuff
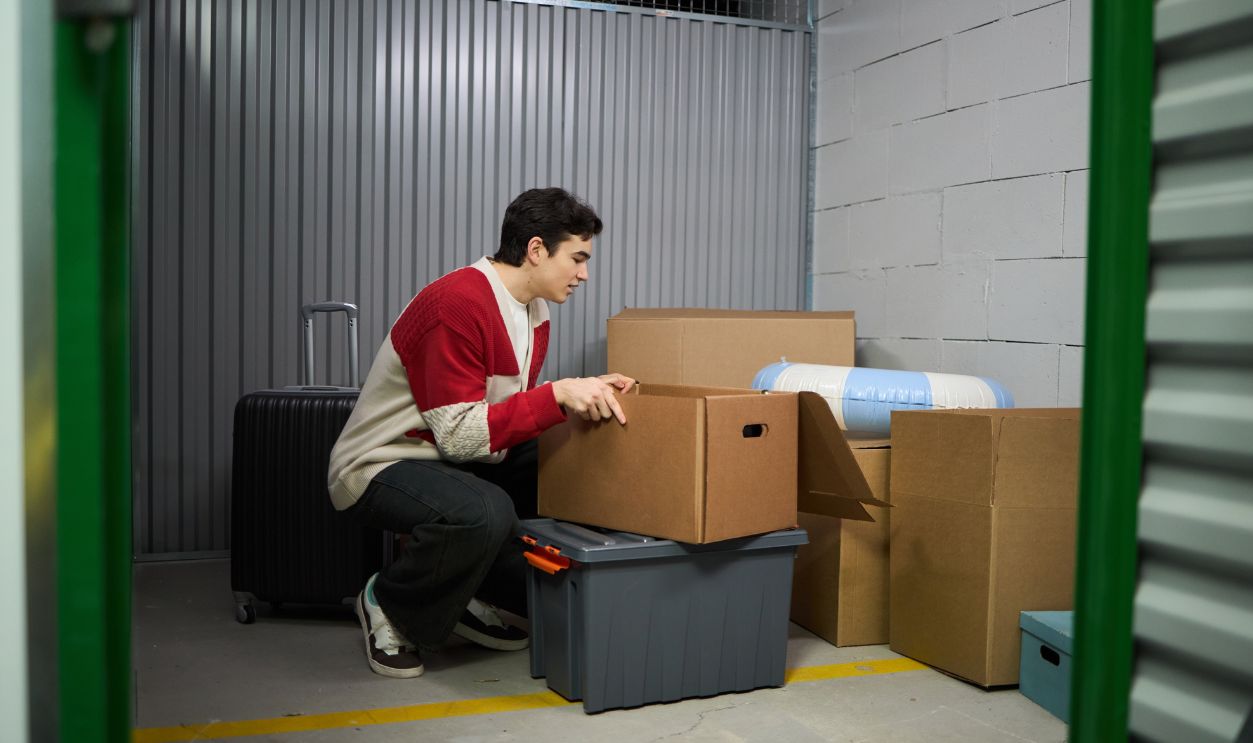
A storage unit can gradually cost more than the belongings inside it, especially after repeated rent increases. Review the monthly rate, insurance charge, administrative fee, unit size, and total amount spent over the previous year before automatically renewing.
Ask About A Smaller Unit
Ask about a smaller unit, a transfer to a less expensive location, or a promotional rate for existing customers. Selling, donating, or relocating stored items may eliminate the bill entirely, although customers should carefully follow move-out rules to avoid another month’s charge.
Do Not Cancel Life Insurance Hastily
Life insurance should not be canceled impulsively, particularly when someone depends on the policyholder’s income. However, households should confirm that the coverage still matches their needs and that they understand whether the policy is term, whole, universal, or another permanent product.
 StockPhotoDirectors, Shutterstock
Understand The Replacement Risks
An independent insurance professional can help review premiums, beneficiaries, cash values, surrender charges, and replacement risks. Never cancel an existing policy until any replacement is approved and active, since age or health changes could make new coverage more expensive or unavailable.
Compare Auto Insurance Quotes
Auto insurance prices can vary significantly among companies even when the coverage appears similar. Review annual mileage, listed drivers, vehicle use, deductibles, optional coverage, discounts, and whether an old accident or ticket is still affecting the quoted rate.
Compare Identical Coverage
Request comparable quotes using the same liability limits and deductibles, because the cheapest advertisement may provide weaker protection. State insurance departments may offer consumer guidance, and some states operate assistance programs or alternative coverage options for eligible drivers.
Review Homeowners Or Renters Insurance
Insurance policies should be reviewed before a household simply accepts another renewal increase. Check rebuilding limits, personal-property coverage, deductibles, riders, discounts, and whether the insurer has accurate information about the home, security devices, roof, and claims history.
Cheaper Should Not Mean Unprotected
Bundling policies or increasing a deductible may lower premiums, but higher deductibles require more emergency savings. Renters should not assume a landlord’s policy covers their belongings, while homeowners should avoid reducing coverage below what their mortgage or genuine rebuilding needs require.
Property Assessments Can Be Wrong
Homeowners may be paying more property tax because the assessment contains incorrect square footage, the wrong classification, or improvements that do not exist. Local governments commonly have formal appeal deadlines, so placing the notice in a drawer can mean losing the chance to challenge it.
Look For Property Tax Relief
Many jurisdictions also offer homestead exemptions, senior or disability relief, veteran benefits, deferrals, or income-based programs. Rules are local, and some assistance must be renewed, making the assessor’s office or official government website the safest place to check.
Childcare Assistance May Be Available
Childcare is often one of a working family’s largest bills, yet assistance may be overlooked because eligibility rules vary by state. State childcare subsidy programs can help qualifying families pay for care while parents work, attend school, or participate in approved training.
Employers May Offer Help
Families should also ask employers about dependent-care benefits, flexible spending arrangements, negotiated daycare rates, or backup-care programs. Tax credits and employer benefits have separate eligibility rules, so a tax professional can help prevent accidental double counting.
Contact The Auto Lender Early
Borrowers struggling with a car payment should contact the lender or servicer before missing it. Some lenders may offer a due-date change, payment extension, temporary hardship arrangement, refinancing, or another modification, but approval is never automatic.
Extensions Can Cost More
An extension can increase the loan’s total interest or add payments at the end, so the new terms should be obtained in writing. Voluntary surrender is not a clean escape because borrowers may still owe a deficiency after the vehicle is sold.
Credit Cards May Have Hardship Programs
Credit-card issuers may have hardship programs that temporarily reduce interest, waive certain fees, or adjust minimum payments. The Consumer Financial Protection Bureau recommends contacting the card company immediately and explaining why the payment is unaffordable.
Make A Specific Request
Tell the card company how much can be paid and when normal payments might resume. Having specific numbers can make the conversation more productive than simply saying the bill is unaffordable.
Be Careful With Debt Settlement
Households should be cautious with debt-settlement companies that promise to erase balances or tell customers to stop communicating with creditors. Nonprofit credit counseling may be helpful, but fees, services, and organizational credentials should be checked first.
Federal Student Loan Options Differ
Federal student loan borrowers may have access to income-driven repayment, deferment, forbearance, consolidation, or forgiveness programs depending on their loans and circumstances. Available options have changed repeatedly, so borrowers should rely on Federal Student Aid and their official servicer rather than old online advice.
Compare The Long-Term Cost
Reducing or suspending a payment can affect interest and the total amount repaid. Borrowers should compare the long-term cost, confirm how an option affects forgiveness progress, and avoid companies charging for applications that can be completed through federal channels.
Do Not Ignore Federal Tax Debt
Ignoring an IRS bill can allow penalties and interest to continue while collection problems grow. The IRS offers short-term and long-term payment plans for eligible taxpayers, and certain people experiencing hardship may have additional collection alternatives.
Offers In Compromise Are Not Guaranteed
An offer in compromise can settle qualifying tax debt for less than the full amount, but acceptance is not guaranteed. The IRS warns about companies that aggressively promote these arrangements to people who do not qualify, so taxpayers should start with official tools.
Investigate A Rising Water Bill
A suddenly higher water bill may signal a leaking toilet, broken irrigation line, faulty meter, or incorrect reading. Compare usage with the same period in previous years and ask the utility whether it offers a leak adjustment after a qualifying repair.
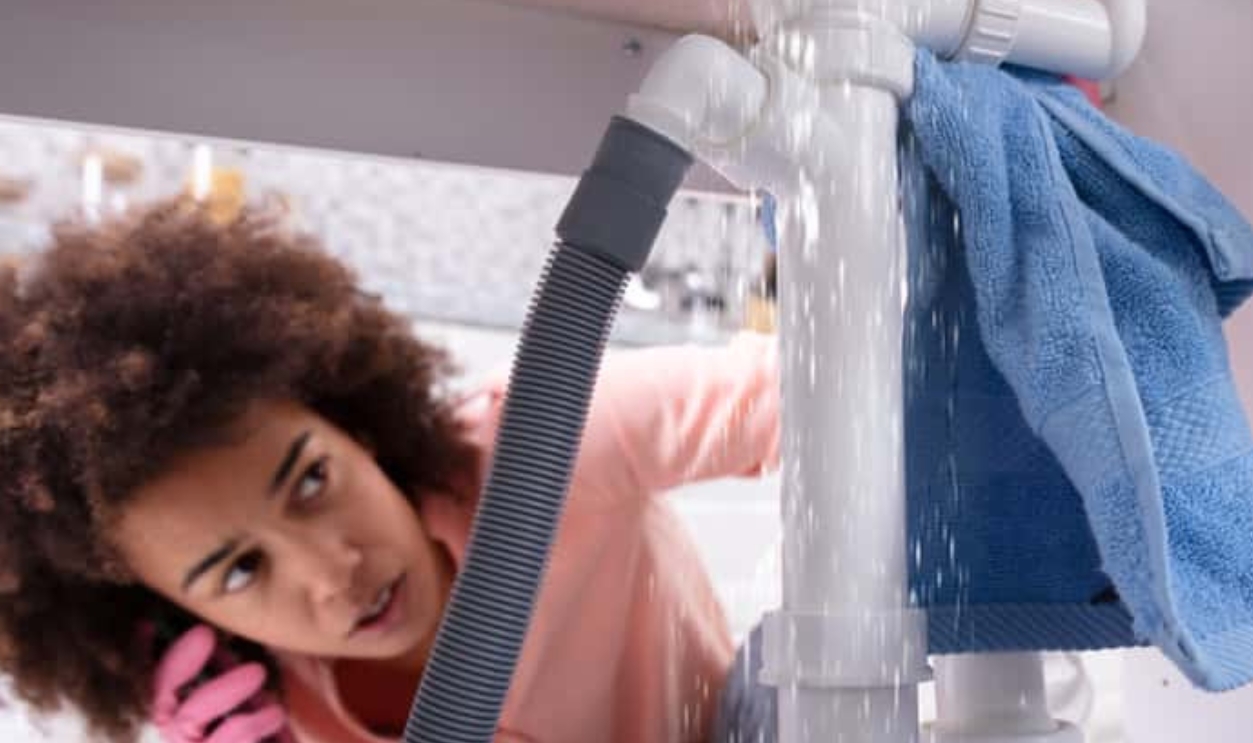
Ask About Water Assistance
Municipal utilities may provide payment plans, reduced rates, senior discounts, or hardship funds, but programs vary widely. Households facing shutoff should contact the utility quickly because waiting can add late fees, reconnection charges, or damage from an unresolved leak.
Examine The Electricity Charges
Electric bills should be checked for estimated readings, incorrect rate plans, old balances, unnecessary add-ons, and unusual usage. Customers may be eligible for budget billing, extended payment arrangements, energy audits, weatherization assistance, or reduced-income rates, depending on the utility and state.
LIHEAP Can Help With Energy
The Low Income Home Energy Assistance Program, known as LIHEAP, helps eligible households with energy costs, energy crises, weatherization, and certain minor energy-related repairs. Funds and eligibility rules are administered locally, and assistance is not guaranteed.
Recheck Heating Expenses
Households using natural gas, heating oil, propane, or another delivered fuel should ask about budget plans, hardship protection, payment extensions, and seasonal assistance. Comparing delivery charges and usage patterns may reveal a rate change, estimated reading, or inefficient equipment.
Do Not Wait Until The Tank Is Empty
LIHEAP may also assist with qualifying heating expenses, while the Weatherization Assistance Program can help eligible households improve energy efficiency. Customers should contact the fuel provider before the tank is empty or service is disconnected, when fewer options may remain.
Update Health Insurance Information
A household paying the full price for health insurance should recheck its eligibility whenever income, family size, employment, or address changes. Marketplace premium tax credits are based partly on expected annual household income and may reduce the monthly premium for qualifying applicants.
Medicaid Or CHIP May Be Available
Some applicants may instead qualify for Medicaid or the Children’s Health Insurance Program. Marketplace customers should promptly report income changes because using more advance premium tax credit than ultimately allowed can affect the household’s federal tax return.
Medicare Savings Programs Can Help
People with limited income and resources may qualify for a Medicare Savings Program administered through their state. Depending on the program, assistance may pay Medicare Part A or Part B premiums and, in some cases, deductibles, coinsurance, and copayments.
Extra Help Can Reduce Drug Costs
Qualifying for certain Medicare Savings Programs can also provide automatic eligibility for Extra Help with Part D drug costs. Medicare advises people to apply even if they think they are slightly above published limits because state counting rules can differ.
Ask About Cheaper Prescriptions
Before skipping medication or splitting pills without medical guidance, ask the prescriber or pharmacist whether a lower-cost generic, therapeutic alternative, different quantity, or preferred pharmacy is available under the insurance plan.
 Monkey Business Images, Shutterstock
Never Change Treatment Alone
Never change a dose or stop treatment without consulting an appropriate healthcare professional. A lower price is only helpful when the alternative remains medically appropriate.
Compare Prescription Assistance Options
Patients may also qualify for Medicare Extra Help, Medicaid, manufacturer assistance, pharmacy discount programs, or nonprofit support. Discount cards are not insurance, and their price should be compared with the insurance copay rather than assumed to be cheaper.
Ask For An Itemized Medical Bill
Medical bills should be reviewed for duplicate charges, services never received, incorrect insurance processing, and confusing coding. Ask the provider for an itemized bill and the insurer for an explanation of benefits, then question discrepancies before placing the balance on a high-interest credit card.
Hospitals May Offer Financial Assistance
Tax-exempt hospitals must maintain written financial-assistance policies covering eligible emergency and medically necessary care. Patients can request the application even after receiving a bill, although the hospital’s income rules, deadlines, covered providers, and required documents must be checked.
Contact The Landlord Before Rent Is Due
Renters facing a shortfall should contact the landlord or property manager before the due date and request any agreement in writing. A payment plan, altered due date, fee waiver, or temporary partial payment may be possible, although landlords are not required to approve every request.
Look For Eviction-Prevention Assistance
Local governments and nonprofit organizations may offer emergency rental assistance, legal aid, or eviction-prevention services. Rules change frequently, so HUD-approved housing counselors and official local agencies are safer starting points than businesses demanding upfront fees.
Contact The Mortgage Servicer Immediately
A homeowner worried about missing a mortgage payment should contact the mortgage servicer immediately. Depending on the loan and circumstances, possible loss-mitigation options may include forbearance, a repayment plan, loan modification, refinance, short sale, or deed in lieu of foreclosure.
Free Housing Counseling Is Available
A HUD-approved housing counselor can provide free or low-cost help reviewing the available choices. Homeowners should avoid foreclosure-rescue companies that demand upfront money, guarantee a modification, request the property title, or instruct them to stop communicating with the servicer.
Protect Food And Medicine First
Before cutting food or medicine, households should also check whether they qualify for SNAP, WIC, Medicaid, food banks, prescription assistance, or local benefits. These programs exist because nutrition and healthcare are necessities, not luxury categories that should automatically be sacrificed first.
You May Also Like:
Workplace Habits Americans Think Are Normal—But The Rest Of The World Finds Bizarre
Financial Rights Most Americans Don’t Know They Have—And It’s Costing Them Money
These Strange Financial Rules Are Affecting Your Money—And You Don’t Even Know It