The Family Loan That Suddenly Became A Gift
For years, I watched my brother borrow money from our parents, always assuming those amounts would eventually be repaid. Now that the estate is being settled, I've learned that the money is being classified as a gift instead of a debt. That distinction could affect how much money remains for everyone else to inherit. But can I actually challenge the decision, or does my brother get to keep everything he received? Factinate Ltd
The Answer Is Yes, But There Is A Catch
A beneficiary may be able to challenge how an estate classifies money transferred to a family member. However, questioning the classification is different from proving that the money was legally owed back. The outcome depends on the evidence, the parents' intentions, and the inheritance laws of the relevant jurisdiction. Courts can consider objections to estate accounts, but unsupported allegations may not succeed.
 https://kaboompics.com/, Pexels
A Loan And A Gift Are Not The Same Thing
The central question is whether the parents expected their son to repay the money. A genuine loan creates a repayment obligation, while an outright gift generally does not. Federal tax law even recognizes arrangements involving below-market family loans, showing that favorable lending terms do not automatically eliminate the underlying debt. Determining what actually happened requires examining the original arrangement rather than relying solely on what relatives call it today.
Why The Original Agreement Matters So Much
A written agreement can help establish whether the money was advanced as a loan and what repayment terms applied. Relevant details include the amount borrowed, any interest requirements, and when repayment was expected. If those details were recorded, they may help distinguish an outstanding debt from a completed gift. Without clear documentation, the dispute may depend more heavily on other evidence of the parents' intentions.
The Missing Paperwork Problem
Not every family financial arrangement comes with a formal contract. Parents sometimes transfer money to adult children without recording the terms in a conventional loan document. That creates an evidentiary problem when the parents are no longer available to explain what they intended. A missing agreement does not, by itself, establish that the money was a gift, but it can make a repayment claim harder to prove.
Bank Transfers Could Tell Part Of The Story
Bank statements may establish when money moved from the parents' accounts to their son's account. They can also help reconstruct the total amount transferred over several years. However, the transfer itself does not necessarily establish whether repayment was expected. Financial records become more persuasive when they can be connected to written promises, repayment activity, or other evidence explaining the transaction.
Repayments Could Change Everything
Suppose the brother occasionally returned money to his parents after receiving substantial transfers. Those payments might support an argument that at least some of the transactions were loans rather than gifts. Their significance would depend on the amounts, timing, and circumstances of each payment. A detailed transaction history could therefore become important when evaluating whether any balance remained unpaid.
Old Messages May Be More Important Than Expected
Emails, letters, and text messages may reveal how the parents and their son described the financial arrangement. A message acknowledging an outstanding balance could support the position that repayment was expected. Correspondence showing that the parents deliberately forgave an obligation could point in the opposite direction. The important issue is whether the communications provide reliable evidence of the arrangement and any later changes.
The Executor Cannot Simply Ignore The Estate's Interests
An executor or personal representative has legal responsibilities that extend beyond keeping the family comfortable. Massachusetts law, for example, requires a personal representative to administer and distribute an estate according to the applicable will and law while acting in the estate's best interests. If a genuine, collectible loan belongs to the estate, its treatment deserves proper consideration. The executor's decision should be grounded in the available evidence and applicable legal obligations.
What If My Brother Is Also The Executor?
The situation becomes especially sensitive when the person who received the money also controls the estate administration. That creates a potential conflict between the individual's financial interests and their fiduciary responsibilities. Fiduciary duties do not disappear simply because the representative is a family member or beneficiary. A disputed classification involving the executor's own transactions may warrant particularly careful scrutiny.
A Gift Does Not Automatically Reduce An Inheritance
One important distinction is that a lifetime gift does not necessarily count against the recipient's eventual inheritance. Arizona's advancement statute, for example, generally requires qualifying written evidence before a lifetime gift can be charged against an heir's intestate share. Similar provisions appear in Hawaii and Utah. This means that even proving a substantial gift occurred may not establish that the recipient's inheritance must be reduced.
The Legal Term You Should Know Is Advancement
An advancement is a lifetime transfer treated as an advance against an heir's share of an intestate estate. Under Maine's probate statute, the treatment generally requires a contemporaneous written declaration by the deceased person or a qualifying written acknowledgment by the heir. The law also provides rules for valuing qualifying advancements. Whether this concept applies to a particular family depends on the governing state's law and the circumstances of the estate.
What If My Parents Never Called It An Advancement?
A family may believe that earlier financial help should be deducted from a child's inheritance even when the parents never documented that intention. In states following the written-evidence approach, that belief alone may not satisfy the statutory requirements for an advancement. Arizona expressly requires qualifying written evidence for this treatment of lifetime gifts in intestate succession. Consequently, an argument based entirely on what seems fair to the other siblings may face a significant legal obstacle.
The Will Could Change The Entire Discussion
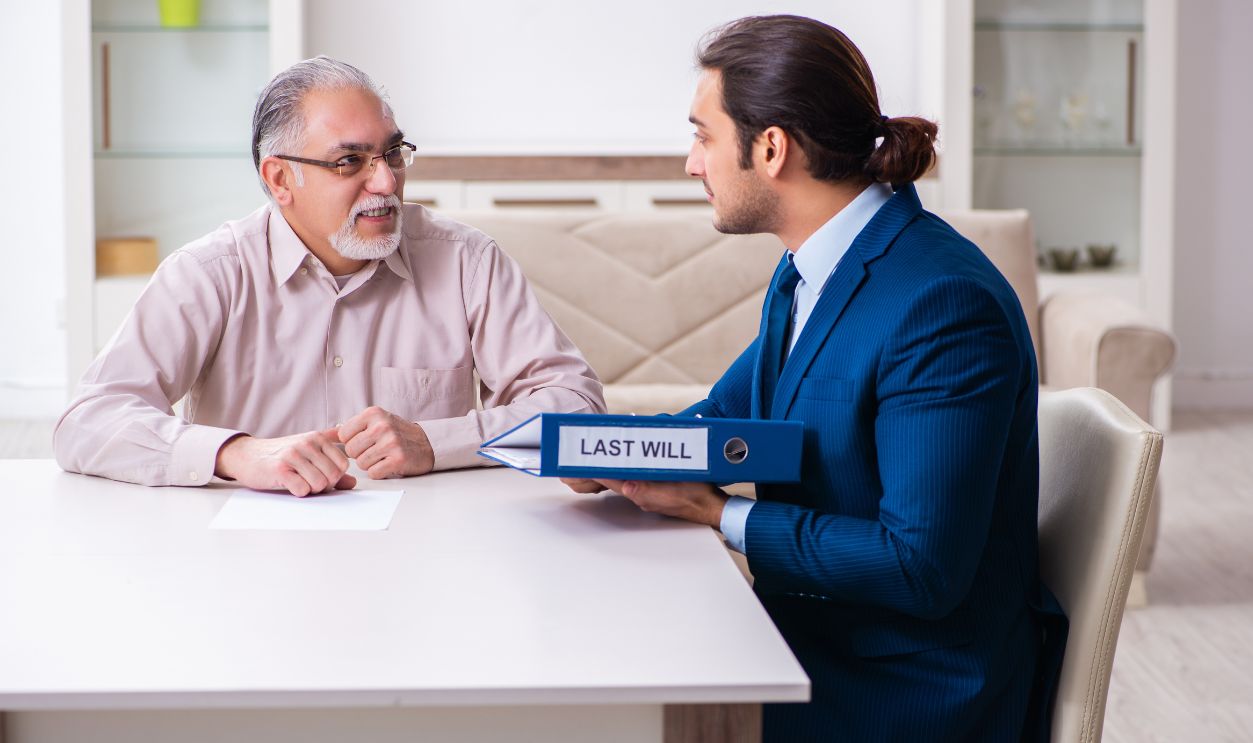
Before arguing about equal treatment, it is essential to examine the actual estate-planning documents. A valid will may contain instructions about distributions or the treatment of earlier financial assistance. The executor must administer the estate according to the effective will and applicable law. That makes the estate documents a logical starting point before deciding whether the disputed transfers should affect anyone's inheritance.
Can The Estate Really Collect An Old Family Debt?
A legitimate unpaid loan may represent a claim belonging to the deceased lender's estate. Massachusetts law gives a personal representative, subject to certain exceptions, standing to bring legal proceedings that the deceased person could have brought. That does not guarantee that an old family loan is still enforceable or collectible. The original agreement, available evidence, and applicable legal time limits all matter.
What If My Parents Forgave The Loan?
The possibility of forgiveness introduces another important question. A loan may have been genuine when the money was transferred, but the parents could later have decided to release their son from repayment. Evidence of that decision would need to be evaluated separately from evidence establishing the original loan. A dispute over whether forgiveness occurred can therefore be just as important as a dispute over whether the money was borrowed in the first place.
The Tax Records Might Offer Another Clue
Tax documents may provide useful context when investigating how substantial family transfers were treated. Federal law contains specific provisions for below-market loans, including arrangements where favorable interest terms have a gift component. However, a tax classification does not necessarily settle whether the principal was legally repayable under state law. Tax records should be considered alongside the underlying agreement and other financial evidence.
Asking For An Accounting Is A Logical Step
An estate accounting can provide a formal picture of the assets and transactions being reported during administration. In New York, courts have recognized that executors and trustees have obligations to account for their actions. A beneficiary with appropriate legal standing may be able to question an accounting that appears incomplete or inaccurate. That process can provide a more structured way to address disputed estate assets than relying on informal family explanations.
But An Accounting Objection Needs Evidence
A court will not necessarily accept a challenge simply because a beneficiary believes something is unfair. In the 2023 New York case Matter of Holterbosch, the court upheld the dismissal of objections that lacked sufficient factual support. The decision explained that an objecting party must come forward with evidence indicating that an accounting is inaccurate or incomplete. That makes specific financial records and documented discrepancies much more useful than generalized suspicions.
The Courts Have Seen Family Disputes Like This Before
Estate disagreements involving siblings are not unusual in probate litigation. In the 2024 New York case Matter of Clifford, one brother challenged numerous aspects of an accounting submitted by another brother serving as trustee. The court allowed some objections to proceed while dismissing others. Although the case involved trust administration rather than this exact loan scenario, it illustrates how courts can examine individual objections instead of treating every family disagreement as one claim.
There May Be A Deadline To Speak Up
Timing can be just as important as evidence. In the 2026 New York decision Matter of Delaney, a court upheld the dismissal of estate-accounting objections filed after the relevant proceedings had already concluded. The court emphasized the binding effect of a final accounting decree in the circumstances presented. Anyone considering a challenge should therefore identify applicable deadlines before assuming there will be another opportunity to object.
Being A Sibling Does Not Automatically Guarantee Standing
A family relationship alone does not establish an unlimited right to challenge estate administration. Courts may examine whether the person objecting has a legally recognized interest affected by the accounting. In Matter of Biondo, a New York appellate court addressed the consequences of a party losing standing to object to an estate accounting. Before filing a challenge, it is important to establish both the person's legal interest and the particular decision being disputed.
A Lawyer Can Help Separate Two Different Claims
There are two possible disputes hiding inside this situation. The first is whether the brother still owes money that should be treated as an estate asset. The second is whether money that was genuinely gifted should nevertheless reduce his inheritance under the will or applicable advancement rules. These questions require different legal analyses, and winning one argument does not automatically establish the other. An estate-litigation lawyer can evaluate which claim, if either, the documents and governing law support.
Going To Court Is Not The Only Possible Outcome
Not every disputed estate accounting ends with a full trial. In Matter of Clifford, the court evaluated the legal sufficiency of individual objections before deciding which could continue. This demonstrates that estate litigation can involve narrower questions about particular transactions and accounting entries. A focused request for records or an explanation may help identify the real disagreement before a beneficiary decides whether further legal action is justified.
Fairness And Legal Entitlement Are Different Questions
It may feel deeply unfair when one child received years of financial assistance while another received none. However, inheritance law does not necessarily require every lifetime gift to be equalized. Arizona and Hawaii, for example, impose specific written-evidence requirements before certain lifetime gifts count as advancements against intestate inheritance. A compelling emotional argument is therefore not always enough to establish a legal entitlement to a larger share.
What I Would Do Before Signing Anything
Before accepting the estate's treatment of the transfers, I would want to understand exactly what documents support the gift classification. I would also want to know whether the estate has already filed an accounting, whether any objection period is running, and whether I am being asked to approve or release any claims. Those details could affect my available options. Given the consequences of a final accounting decree illustrated in Matter of Delaney, obtaining legal advice before signing a release or allowing a deadline to pass would be a sensible precaution.
The Bottom Line Is That A Gift Label Is Not The Final Word
The estate's decision to call years of financial assistance a gift does not automatically make the classification unchallengeable. A beneficiary with standing may have grounds to question whether the money was a repayable loan, whether any debt was forgiven, or whether a documented advancement should affect inheritance shares. But the evidence, estate documents, state law, and procedural deadlines will determine whether a challenge has merit. The strongest starting point is not an accusation against the brother, but a careful examination of the records and the legal basis for the estate's decision.
You May Also Like: