The Name on the Form Can Change Everything
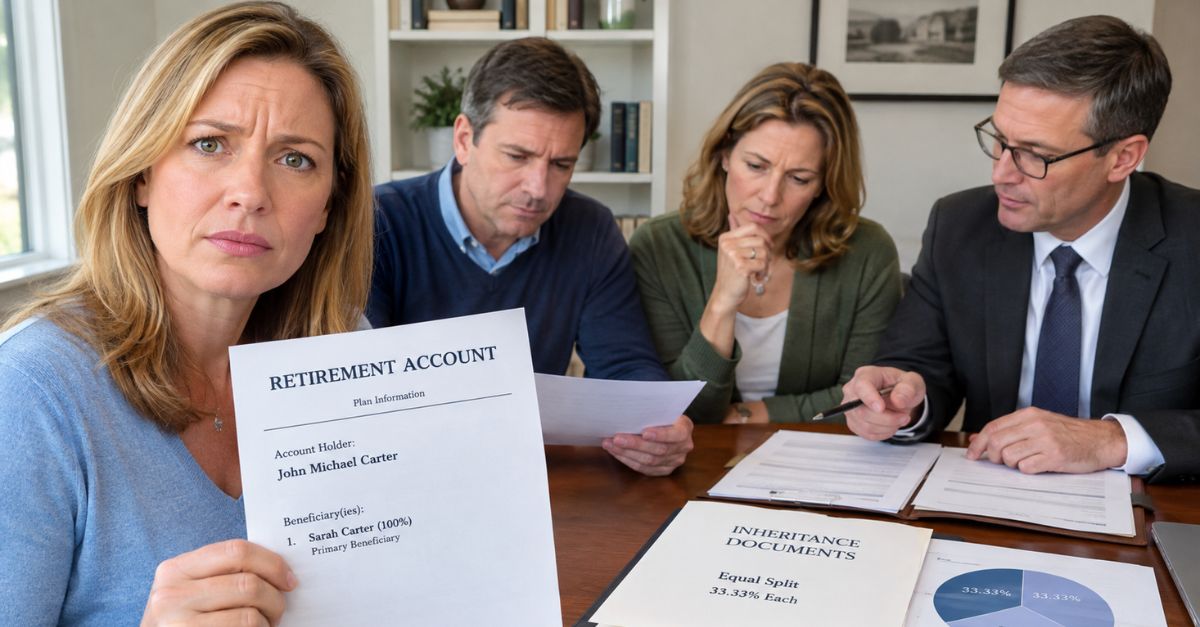
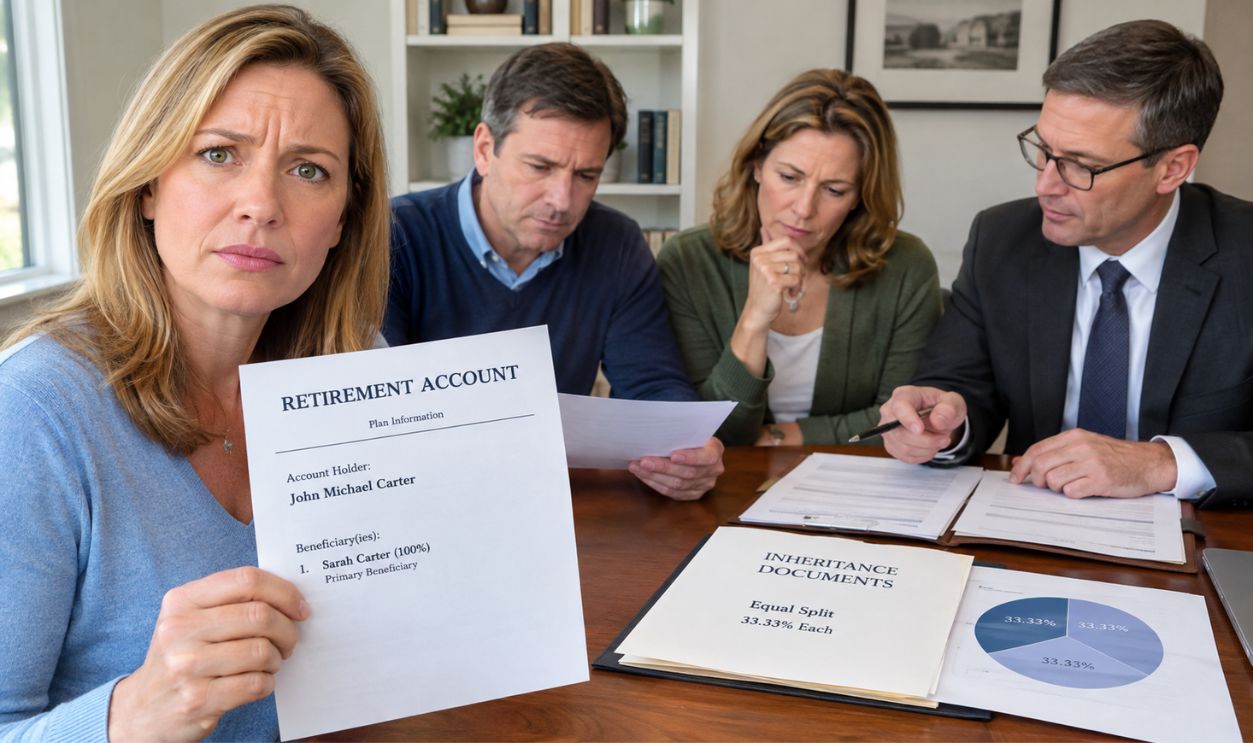
If your dad named you as the beneficiary on his retirement account, that choice will usually decide who gets the money. That is true even if his will says everything should be split equally among the children. It is one of the most common and surprising estate fights families run into.
Why This Trips Up So Many Families
Most people think a will controls everything a person owns. It does not. Many valuable assets pass outside the will. Retirement accounts, life insurance policies, and payable-on-death accounts usually go to the person listed on the beneficiary form.
The Core Rule in Plain English
A retirement account beneficiary designation usually beats anything in a will that says something different. That rule applies to accounts like IRAs and many 401(k) plans. If the account paperwork says you inherit it, the financial company will usually follow that form, not the will.
The Supreme Court Backed This Rule
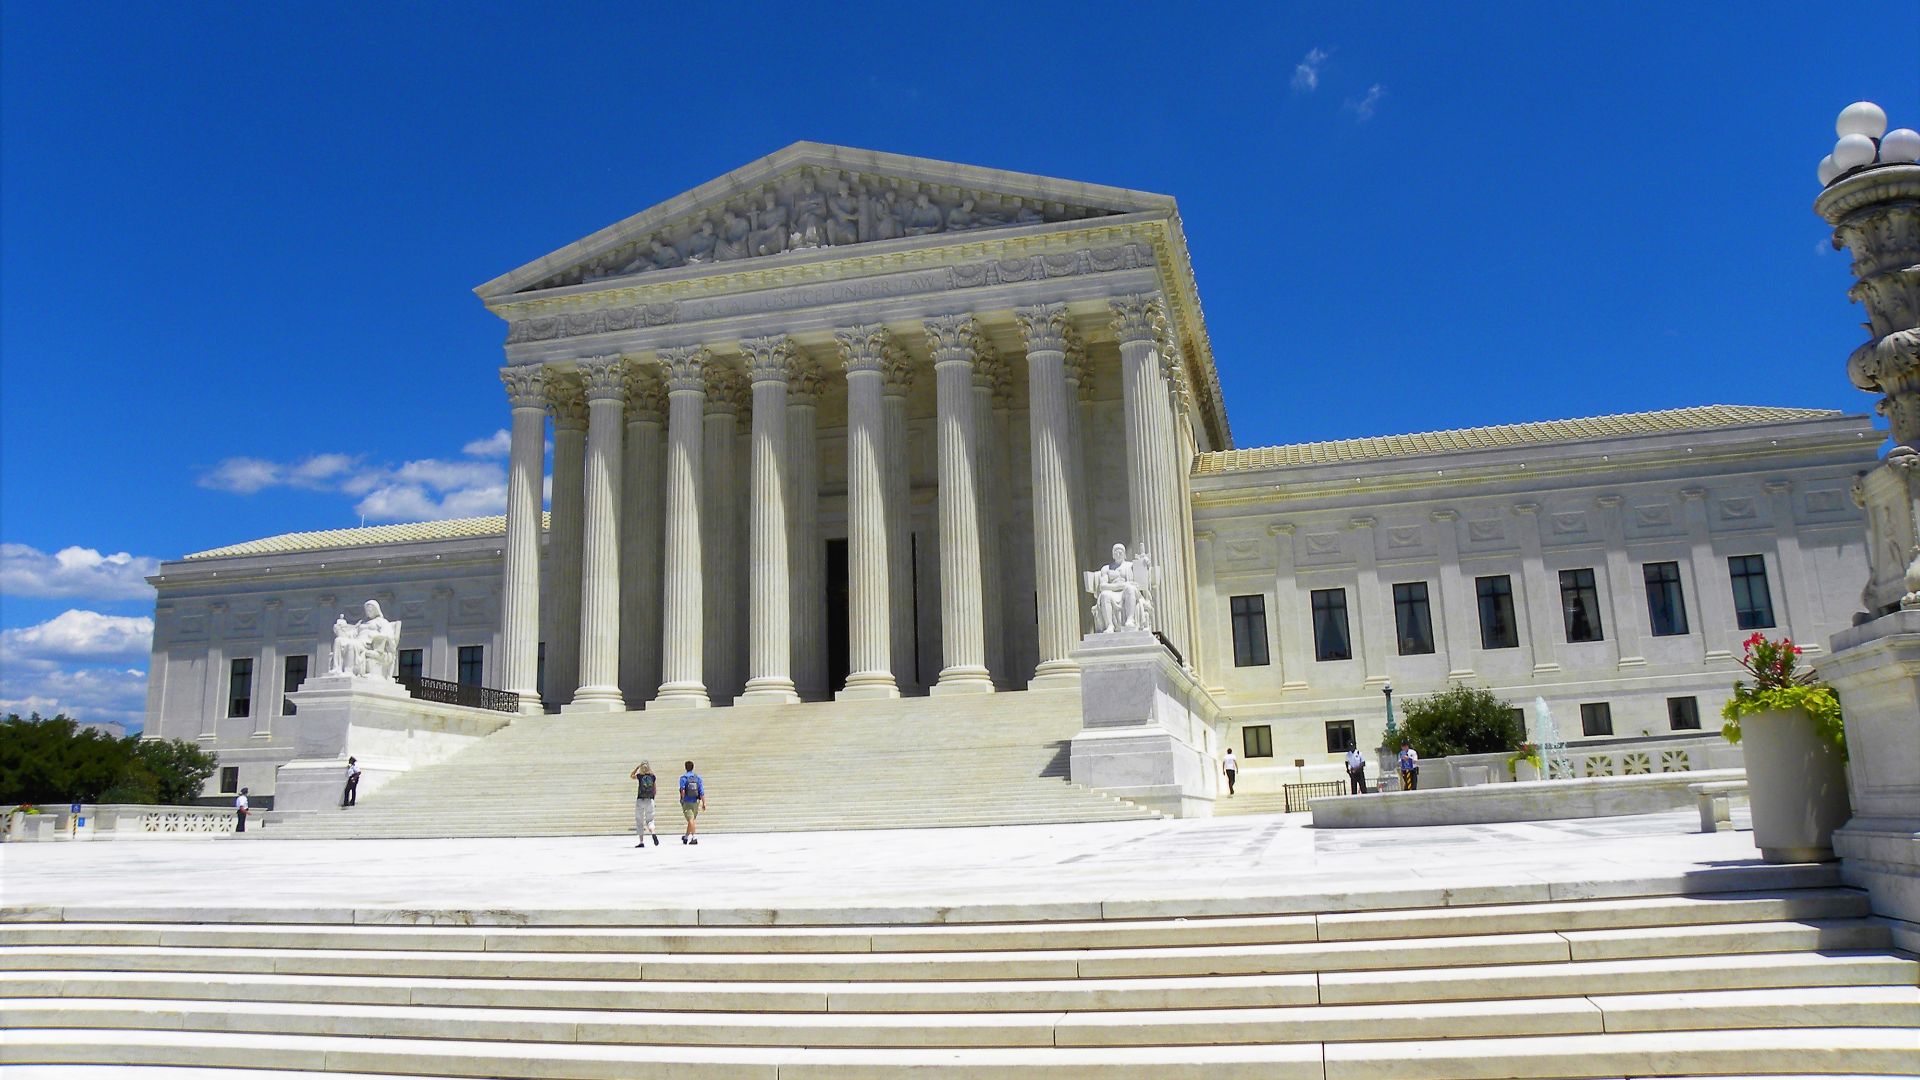
One of the clearest examples came from the U.S. Supreme Court in 2001 in Egelhoff v. Egelhoff. The Court held that a Washington state law was overridden by federal law for an ERISA-covered employee benefit plan. In practical terms, the plan administrator paid the named beneficiary because the plan documents controlled.
 Mathieu Landretti, Wikimedia Commons
What Happened in Egelhoff
David Egelhoff had named his wife Donna as beneficiary of his life insurance policy and pension plan. They later divorced, and he died just two months after the divorce without changing those designations. His children argued that a Washington law automatically canceled the ex-spouse's beneficiary status, but the Supreme Court said ERISA required administrators to follow the plan documents.
Another Big Case Drove the Point Home
The Supreme Court reinforced the same idea in 2009 in Kennedy v. Plan Administrator for DuPont Savings and Investment Plan. In that case, the Court said the plan administrator properly paid benefits to the ex-wife who was still the named beneficiary. That happened even though she had waived her rights in a divorce decree.
What Kennedy Means for Real Families
The lesson from Kennedy is simple. If someone wants to change who gets a retirement account, they usually need to update the beneficiary form itself. Side agreements, divorce paperwork, and even carefully written estate documents may not be enough if the account paperwork still names someone else.
Wills and Beneficiary Forms Run on Different Tracks
A will controls probate assets, which are assets titled in your dad's name alone without a beneficiary designation. A retirement account with a named beneficiary is usually a non-probate asset. That means it passes by contract directly to the named person after death.
Probate Assets vs. Non-Probate Assets
This split matters more than many families realize. A house owned only by your dad might pass under the will unless it has another transfer setup. But an IRA or 401(k) with a current beneficiary form usually skips probate and goes straight to the listed beneficiary.
Federal Law Can Matter a Lot
Many workplace retirement plans, including most 401(k) plans, are governed by the federal Employee Retirement Income Security Act, better known as ERISA. ERISA puts a lot of weight on following plan documents. That is one reason courts keep coming back to the same point: the beneficiary form is the key document.
IRAs Usually Follow the Same Practical Rule
IRAs are not usually governed by ERISA in the same way employer plans are, but beneficiary designations still usually control them. Financial institutions rely on those forms to pay out the account after death. If the will says equal shares but the IRA form names only one child, the institution will normally pay that named child.
There Is One Big Spousal Exception
If the retirement account is a 401(k) or another ERISA-covered defined contribution plan, a spouse often has special rights. The U.S. Department of Labor says a married participant's spouse is usually the default beneficiary unless the spouse agrees in writing to name someone else. That means a parent cannot always freely name one child and leave out a current spouse on that kind of plan.
Why Marriage Changes the Analysis
If your dad was married when he filled out the beneficiary form, the account type matters. For many employer plans, a spousal waiver has to meet specific rules to be valid. If that waiver was never signed, the spouse may have a strong claim no matter what the will says or what the form seems to show.
If the Account Is an IRA, the Rules Can Differ
IRAs do not have the same automatic federal spousal consent setup that applies to many ERISA plans. Even so, state law and the IRA agreement can affect the outcome in unusual cases. For most families, though, the named IRA beneficiary is still the first place to look.
What If the Beneficiary Form Is Missing
If no valid beneficiary is on file, the plan or IRA custodial agreement usually has default rules. Sometimes the account goes to the surviving spouse, then children, or to the estate. If the estate becomes the recipient, the will may finally matter because the asset is pulled back into the estate.
What If the Beneficiary Died First
That can change everything. Some forms name contingent beneficiaries who inherit if the primary beneficiary dies before the account owner. If no backup is listed, the account agreement may send the money to the estate or to heirs under its default rules.
The Estate Only Gets a Say Sometimes
Your dad's will becomes relevant if the retirement account names the estate as beneficiary, if no beneficiary designation is valid, or if the account agreement defaults to the estate. Outside those situations, the will often cannot redirect the money. That may feel unfair, but it is a standard legal result.
Can Siblings Sue Anyway
Yes. These disputes happen all the time. A sibling may claim the beneficiary form was forged, the account owner lacked capacity, or someone used undue influence. But those claims are very fact-specific, and they do not change the starting rule that a valid beneficiary designation usually controls.
Forgery and Undue Influence Are Different Fights
If someone can prove the beneficiary change was fraudulent or signed when your dad did not understand what he was doing, a court may step in. These cases usually need documents, witness testimony, medical records, and a tight timeline. They are not easy claims, but they are one of the few ways a designation can be overturned.
Timing Can Be the Whole Story
The date your dad signed the beneficiary form matters. So do the dates of any divorce, remarriage, diagnosis, guardianship, or will update. In many inheritance fights, the person who can build the clearest timeline has the strongest case.
The Financial Firm Will Start With Its Own Records
The bank, brokerage, or plan administrator will usually review the latest beneficiary form on file. It will not start by comparing the account to the will. That is why families are often stunned when they learn the institution has already decided where the money goes.
What You Should Ask for Right Away
If you are involved in the estate, ask for the most recent beneficiary designation, the account agreement, and any contingent beneficiary information. If it is a workplace plan, ask whether it is subject to ERISA and whether any spousal consent forms exist. These records will usually tell you far more than the will alone.
Taxes Are a Separate Issue
Even when the beneficiary form controls who gets the account, tax rules still matter. Inherited retirement accounts can come with required distribution rules and deadlines. The IRS has detailed guidance for beneficiaries, including options that depend on whether the heir is a spouse, minor child, disabled person, chronically ill person, or another eligible designated beneficiary.
The SECURE Act Changed the Inheritance Landscape
Congress changed many inherited retirement account rules through the SECURE Act of 2019. For many non-spouse beneficiaries, the old lifetime stretch strategy was replaced by a 10-year distribution rule. So even if you clearly inherit the account, the next question is how quickly you must empty it.
Do Not Spend Anything Until You Confirm the Rules
It is smart to slow down before taking distributions. The wrong move can trigger taxes or wipe out better rollover options, especially for surviving spouses. A quick call with the plan administrator and a qualified estate or tax professional can help you avoid expensive mistakes.
 https://kaboompics.com/, Pexels
If You Are the Named Beneficiary, Here Is the Practical Answer
In the typical case, you get the retirement account even if the will says assets should be split equally. Your siblings may inherit equal shares of probate property, while you alone inherit the retirement account. That uneven result is legal if the beneficiary designation is valid.
 https://kaboompics.com/, Pexels
If You Want to Avoid a Family Blowup Later
This is why estate lawyers keep telling clients to review beneficiary forms along with their wills. A will can say one thing while account paperwork says another, and the mismatch may not show up until after death. Reviewing these documents together is one of the simplest ways to avoid a painful surprise.
The Bottom Line
For a retirement account, the beneficiary designation usually controls the money, not the will. The biggest exceptions involve missing or invalid forms, estate default rules, successful legal challenges, or spousal protections under certain employer plans. If this is happening in your family, get the account documents before assuming the will has the final word.