The Beneficiary Shock No Spouse Sees Coming
Your spouse changed the beneficiary on your life insurance to his brother without your knowledge. Putting aside the dozen other reasons this is a red flag, it's also a legal and financial mess. You might be shocked to learn that in many cases, yes, he can do that without telling you. But depending your legal and financial situation, that doesn't mean you can't fight back.
Why This Comes Up So Often
Life insurance beneficiary fights are common enough that state insurance departments and major insurers regularly explain how they work. The basic rule is simple. The person who owns the policy usually controls the beneficiary designation, and the insurer usually pays whoever is listed on the most recent valid form on file.
The First Thing To Check
The biggest question is who owns the policy. If your husband owns the life insurance policy on his life, he usually has the right to name or change the beneficiary. Guardian explains that, in general, the policyholder can change a revocable beneficiary at any time.
Revocable Versus Irrevocable Changes The Whole Story
Not all beneficiaries have the same rights. Guardian says a revocable beneficiary can usually be changed by the policy owner without notice or permission. An irrevocable beneficiary is different, because that person usually has to agree before any change can be made.
If You Were Named Irrevocably
If you were named as an irrevocable beneficiary, your husband usually could not just replace you with his brother on his own. State law and the policy terms still matter, but the main point is that irrevocable status limits the owner's power. That is one of the first things to check in the policy paperwork.
What A Lot Of Married People Get Wrong
Many spouses think marriage automatically gives them a right to life insurance money. Usually, it does not. Northwestern Mutual says the named beneficiary generally gets the death benefit, which means a current spouse can be cut out if someone else is properly listed.
Community Property States Can Change The Picture
If you live in a community property state, things can get more complicated. State Farm explains that in those states, a spouse may need to give written permission before the policy owner can name someone else as beneficiary if community funds are involved. That does not mean the spouse automatically wins, but it does mean the issue deserves a closer look.
Which States Are Usually Treated As Community Property States
The commonly recognized community property states are Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin. Alaska also allows an opt-in community property system. If premiums were paid with marital funds in one of these states, your consent may matter.
When Spousal Consent May Matter
The key question is often whether marital or community funds paid the premiums. If they did, some states may give a spouse a claim to part of the benefit, even if someone else is named. That is not automatic everywhere, but it is one of the strongest reasons to get state-specific legal advice quickly.
ERISA Plans Play By Different Rules
If the life insurance came through an employer, federal law may control what happens. The Employee Retirement Income Security Act, or ERISA, often governs workplace benefit plans. The U.S. Department of Labor says ERISA sets standards for many private-sector employee benefit plans, including rules for beneficiaries and claims.
Why Employer Coverage Can Defy Expectations
With many employer-sponsored policies, insurers and plan administrators have to follow the plan documents and the beneficiary form on file. That means the named beneficiary can still win even when the family thinks the result is unfair. In workplace life insurance cases, paperwork often matters more than promises.
A Supreme Court Case Drove The Point Home
In 2009, the U.S. Supreme Court decided Kennedy v. Plan Administrator for DuPont Savings and Investment Plan. The Court said plan administrators should follow the plan documents, even though an ex-spouse had given up her rights in a divorce decree. It is not a step-by-step guide to life insurance, but it strongly shows how powerful beneficiary forms can be in ERISA-governed plans.2
Why Divorce Decrees Do Not Always Solve It
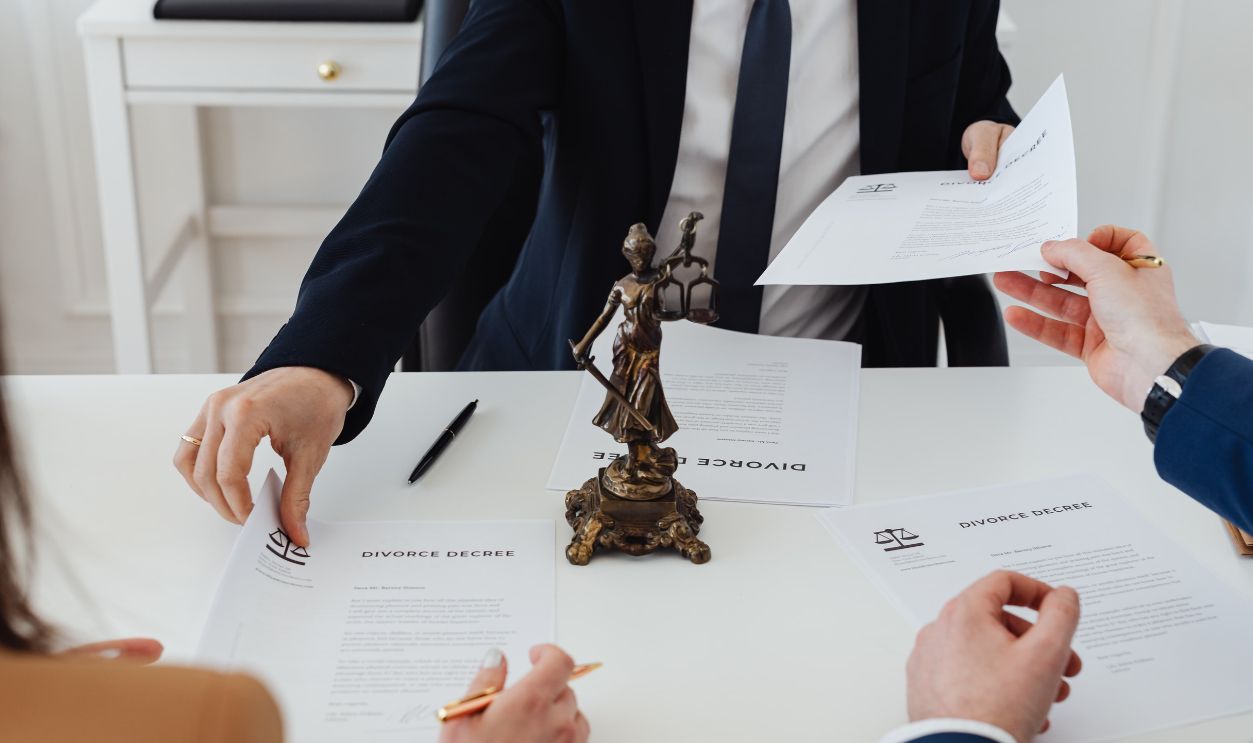
People often assume a divorce judgment automatically changes every beneficiary designation. That is not always true. The Supreme Court's 2009 ruling is a warning that if a plan is governed by ERISA, failing to update the beneficiary form can lead to major problems.
 https://kaboompics.com/, Pexels
If You Are Still Married, Timing Matters
If this change happened while the marriage was still intact, the details matter even more. Was the policy privately owned or provided through work. Were premiums paid with separate money or marital funds. Was there any written consent requirement, temporary restraining order, or pending divorce case at the time.
Can He Do It Without Telling You
In many everyday cases, yes. If he owns the policy and you are only a revocable beneficiary, he can often change it without telling you. Several insurers explain that revocable beneficiary changes usually do not require the beneficiary's approval, and insurers normally deal with the policy owner, not the person who was removed.
Why Insurers Usually Do Not Warn The Person Who Was Removed
It can feel harsh, but it is standard practice. The insurance contract is usually between the insurer and the policy owner. Because of that, companies typically process valid beneficiary changes without notifying the person who lost that status.
The Biggest Exceptions To Know
A few major exceptions can change the answer. An irrevocable beneficiary designation is one. Community property rights are another. Court orders during a divorce or obligations created in a divorce settlement can also matter a lot.
 https://kaboompics.com/, Pexels
If A Divorce Is Pending, Read The Court Orders Carefully
Some states and counties put automatic temporary restraining orders or standing orders in place once a divorce is filed. Those orders can limit changes to insurance coverage or beneficiaries. If your husband made the change after the case started, the court paperwork and filing date may be crucial.
 https://kaboompics.com/, Pexels
What If The Policy Was Supposed To Secure Child Support Or Alimony
If a court ordered your husband to keep life insurance in place for you or your children, changing the beneficiary may create a serious legal issue. Courts sometimes enforce those duties even when the form on file names someone else. This is very fact-specific, but it is worth raising with a family law attorney.
What To Do Before You Panic
Start by gathering documents. You need the policy, beneficiary forms, premium payment records, any divorce papers or court orders, and the plan documents if the coverage came through an employer. The answer is often buried in the paperwork, not in what someone remembers being said.
Questions To Ask Right Away
Was the policy term life or whole life. Who is listed as the owner. Was your beneficiary status revocable or irrevocable. Was the policy bought privately or through work. Which state's law applies, and were marital funds used to pay the premiums.
How To Confirm The Change Really Happened
Do not rely only on something said during a heated argument. Contact the insurer or the employer's plan administrator and ask what they can share with an interested party. Privacy rules may limit what they tell you before a claim is filed, but a lawyer may be able to request records or help you figure out the next move.
If He Has Already Died, Move Quickly
If the insured person has died and you think the beneficiary change was improper, time matters. Insurers may pause payment when there is a dispute, but not always for long. A probate, family law, or ERISA attorney can help you figure out whether you have a valid challenge before the money is paid out.
Can You Challenge The Beneficiary Change
Possibly, but you usually need solid legal grounds. Common arguments include lack of capacity, undue influence, fraud, violation of a court order, or spousal rights under community property law. Simply being the spouse is often not enough if the policy owner validly named someone else.
Do Verbal Promises Matter
Usually not. Courts and insurers tend to focus on signed forms, plan records, and policy documents. A statement like “I always meant for my wife to get it” is much weaker than an actual beneficiary designation on file.
The Practical Bottom Line
If your husband owns the policy and you were a revocable beneficiary, he can often name his brother without telling you. If you were irrevocable, if community property rules apply, or if a divorce or court order is involved, the answer may be very different. This is one of those disputes where a few documents and one state-specific legal opinion can change everything.
How To Protect Yourself Going Forward
If life insurance is part of your family's safety net, do not assume your status is locked in. Ask for copies of the policy and beneficiary forms, confirm who owns the policy, and review everything after major life events. If the coverage is meant to protect you or your children, talk with a lawyer about whether stronger protections, including an irrevocable designation or court order, make sense.