Man standing outdoors with arms crossed i

My Parents Were Never Able To Pay Off Their Home Equity Loan. Does The Estate Have To Pay It Before We Sell The House?


November 19, 2026 | J. Clarke

My Parents Were Never Able To Pay Off Their Home Equity Loan. Does The Estate Have To Pay It Before We Sell The House?


The House Comes With A Financial Surprise

Inheriting your parents’ home also brings complicated paperwork. Discovering an unpaid home equity loan raises a pressing question: must the family find cash before selling? In most straightforward sales, the money can come from closing instead.
Man standing outdoors with arms crossed iKrakenimages.com, Shutterstock Images

Advertisement

The Short Answer Is Usually No

In a typical U.S. sale, an outstanding home equity loan can be paid from the proceeds at closing. The estate generally doesn't need to settle the entire balance before listing the property, provided the proceeds cover the liens and necessary selling expenses.
Seeking advice. Attentive family couple clients of bank manager real estate agent broker discuss terms conditions of loan mortgage agreement life insurance policy investment options of buying businessfizkes, Shutterstock

Advertisement

The Debt Doesn't Disappear

A borrower's passing generally doesn't erase outstanding obligations. Creditors can seek repayment from estate assets according to state rules governing creditor claims. That includes debts secured by real estate, though how ownership transfers affects the estate's role.
Young couple having serious consultation with a financial or insurance agent, discussing property, loan, or investmentVukasin Ljustina, Shutterstock

Advertisement

Why The House Is Collateral

A home equity loan uses the property as security for the loan. If payments stop, the lender may have the right to foreclose. The obligation is secured by the property, not simply another unpaid bill.
buying a big house, a woman chooses a cottage, real estate servicesVictoria OM, Shutterstock

Advertisement

A Second Mortgage Still Counts

Home equity borrowing often creates a second mortgage behind the original home loan. The claim remains even if the first loan is current. Both normally need to be paid or otherwise released to give an ordinary buyer clear title.
Real estate agent using calculator to calculate house price for client, with house model, contract and money on the tablePremreuthai, Shutterstock

Advertisement

Find Out Which Loan They Had

A traditional home equity loan usually delivers one lump sum. A home equity line of credit, or HELOC, allows repeated borrowing up to a limit. Either can create a lien, so check the paperwork to identify the debt and payment terms.
mature man reading documents at his workplacetetxu, Shutterstock

Advertisement

Heirs Usually Don't Owe It Personally

Being named in a will doesn't ordinarily make you personally responsible for your parents' loan payments. The debt remains with the borrowers' estate. But the lender can still pursue its claim against the home securing the debt.
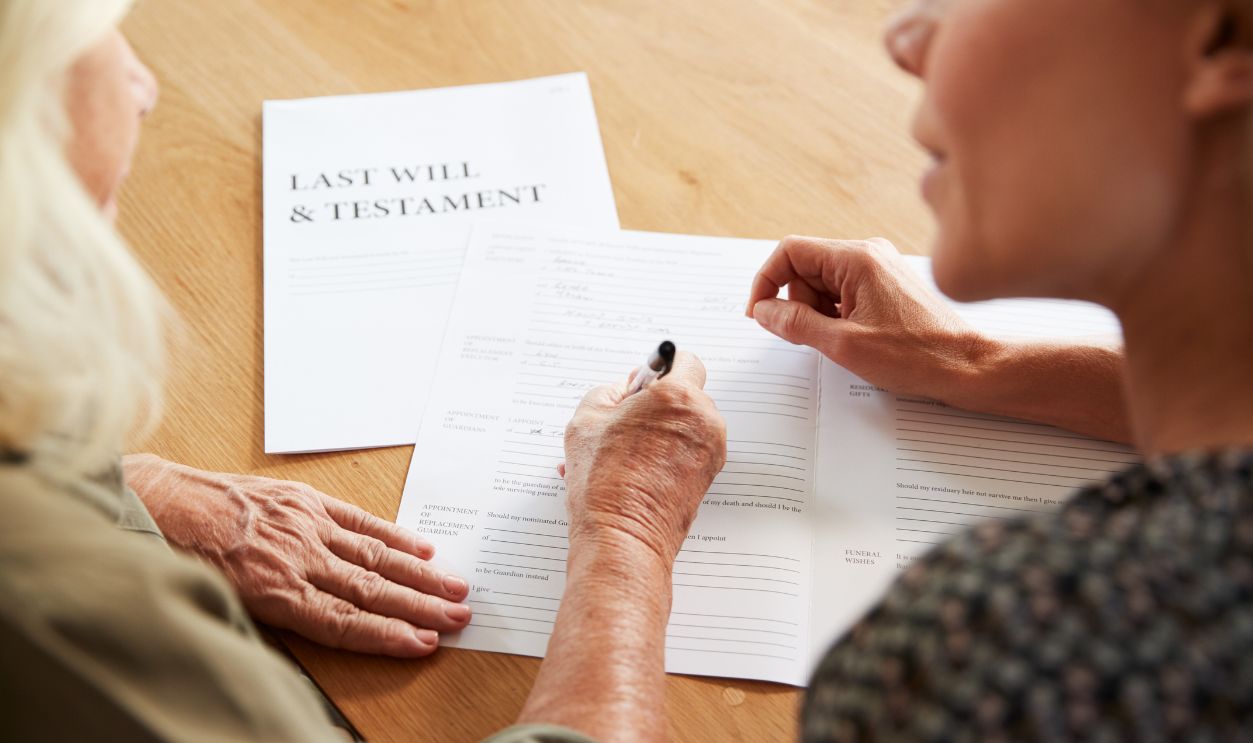
Female Friend Helping Senior Woman To Complete Last Will And Testament At HomeMonkey Business Images, Shutterstock

Advertisement

There Are Important Exceptions

A co-signer may still owe the lender. Some surviving spouses also have responsibilities under state rules, and estate representatives can face consequences for mishandling payments. Family relationships alone don't settle responsibility, so review signatures and applicable state rules.
Financial advisor talking to a senior man with an investment, savings or retirement planning. Discussion, documents and professional accountant helping an elderly male person with finance paperwork.PeopleImages, Shutterstock

Advertisement

The Executor Has A Job To Do

The executor or administrator identifies estate property, deals with creditors, and distributes what remains. An encumbered house needs careful accounting. Giving beneficiaries their shares before addressing creditors can expose the executor to claims.
Male entrepreneur wearing formal suit sitting at table in workplace and signing documents while making successful business dealAndrea Piacquadio, Pexels

Advertisement

First Confirm Who Can Sell

A will doesn't always establish who can sign sale documents. Depending on ownership and probate procedures, an executor, administrator, trustee, or current titleholder may have authority. Confirm authority before accepting an offer or scheduling a closing.
Serious mature legal advisor reading, analyzing and explaining document to female customer. Man and woman sitting at table and reading papers. Expertise and paperwork conceptMangostar, Shutterstock

Advertisement

Check The Property Records

County land records help establish ownership and liens. They may reveal both lenders or an older unresolved lien. A title professional can investigate recorded claims before the family lists the house.
Professional man in a red sweater and suit reviewing paperwork outside during the day.Vanessa Garcia, Pexels

Advertisement

Call The Mortgage Servicer

The servicer is the company handling statements and payments. Report the passing and request account details. The original bank may no longer handle the loan, making its most recent statement useful.
A young man in casual attire talks on the phone while holding a document indoors.Gustavo Fring, Pexels

Advertisement

Have The Right Documents Ready

A servicer may request a death certificate, executed will, or executor's letter before discussing the account. Requirements vary by state. Early preparation helps avoid closing delays when there is already a buyer waiting.
Crop anonymous male looking through files and folder in box placed on desk with green bankers lamp in home officeDziana Hasanbekava, Pexels

Advertisement

Request An Official Payoff Figure

Don't rely on an old statement. Request a payoff statement for the planned closing date. A closing agent can use that figure to arrange payment from sale proceeds.
Real Estate Agent explain insurance and agreement contract to client before sign contract purchase houseWorawee Meepian, Shutterstock

Advertisement

The Balance Isn't The Final Bill

A payoff amount includes interest owed through the specified payment date and unpaid charges. Some loans also carry early-payment fees. If closing shifts to another date, request an updated quote to avoid a shortage.
Senior man receiving the financial contract with retirement plan option, agreement to secure their pension and life savings for the future. Expert giving the document to his clients. Close up.DC Studio, Shutterstock

Advertisement

Closing Is Where The Money Moves

At closing, a settlement agent coordinates payments and documents. The sale proceeds can be directed to mortgage lenders as part of closing. The agent can also arrange the lien releases needed for the transfer. Remaining funds go to the seller or estate.
Professional real estate agent and client shaking hands. Finalizing a property deal or legal agreement. With a house model. Contract. And gavel symbolizing the successful transaction and legal aspects groviapoto, Shutterstock

Advertisement

Pay Attention To Lien Priority

The first mortgage normally has priority over a junior equity loan. That matters when proceeds are limited. A large first-mortgage balance can leave the home equity lender with little or nothing.
Man hands, a finger on button of calculator with financial documents in a hand and others on the tableStanislaw Mikulski, Shutterstock

Advertisement

Selling Costs Also Take A Bite

The sale price isn't the estate's take-home amount. Agent commissions, settlement charges, transfer costs, and other expenses reduce proceeds. Ask the agent for a seller's net estimate before calculating any potential inheritance.
Couple of angry tenants having dispute with real estate agent, discussing complaint with lawyer, consulting legal expert about mistakes in document, wrong mortgage agreement. Cheated clients conceptfizkes, Shutterstock

Advertisement

What If The Numbers Don't Work?

If debts and sale expenses exceed the property's price, a standard closing may not be possible. Calculate the shortfall early. An accepted offer doesn't erase lender claims or guarantee that the sale can close.
Worried and desperate entrepreneur young man calculating bills tax expenses and counting business or home finances sitting on couch at home in paying off debts banking and financial problems concept.SB Arts Media, Shutterstock

Advertisement

A Short Sale Could Be An Option

With approval, a short sale allows a sale below the mortgage debt. Multiple lienholders can complicate approval. Discuss the proposal with each lender and the closing agent before committing to a buyer.
Close-up of a 'For Sale' sign in a suburban yard, indicating a property for sale.SLEEP SLEEP, Pexels

Watch Out For A Remaining Deficiency

Releasing a lien doesn't always forgive unpaid debt. Deficiency collection rules vary. Get any waiver of a remaining balance in writing, not merely a verbal assurance.
Young couple in debt at home, top viewPixel-Shot, Shutterstock

Advertisement

Forgiven Debt Can Create Tax Questions

Canceled debt can have tax consequences, subject to exclusions. The IRS addresses Form 1099-C, probate, and short sales. Ask an estate tax professional to review the proposed settlement and reporting requirements.
Couple, discussion and lawyer with documents for real estate, property investment or loan application and listen. People, man and woman with advisor, paperwork and instructions for legal deal or will PeopleImages, Shutterstock

Advertisement

Don't Let Payments Drift

Unpaid secured loans can still trigger foreclosure. Ask the servicer about payments while selling. Missed payments and increasing interest charges can complicate the estate before the property sells.
Hands counting money, close upSergey Mironov, Shutterstock

Advertisement

Inheritance Isn't Always A Forced Payoff

Federal rules generally protect qualifying transfers to relatives from triggering due-on-sale clauses. The protection doesn't erase debt. A later sale to an outside buyer generally still requires paying off the mortgage.

Banking agent showing contract to female client in domestic interiorBearFotos, Shutterstock

Advertisement

Keeping The House Changes The Discussion

If an heir wants to keep the house, ask the servicer about continuing payments or assuming an existing loan. Eligible successors with title don't always need a new ability-to-repay review. Loan terms and who actually holds title to the property still matter.
Young real estate agent with document pointing at sum of financial expenses while consulting mature couple at meetingPressmaster, Shutterstock

Advertisement

A Sale May Have Separate Tax Effects

Inherited property generally receives a tax basis equal to its value at passing, with exceptions. Taxable gain differs from cash after loan repayment. Keep date-of-death valuation records and obtain tax advice about any gain on sale.
Real Estate sold (another success let us help you buy sell your next home) sign suburban McMansion home autumn day residential neighborhood USA blue sky clouds rSnapshotPhotos, Shutterstock

Advertisement

Settle Claims Before Sharing The Rest

Before distribution, the estate must address valid debts, costs, and taxes. Heirs typically receive only what remains. A properly documented closing and accounting can prevent disputes over what the family receives.
Real estate agents explain models of housing estates in projects to elaborate to clients, explaining and presenting information about homes and purchasing loans. Real estate trading concept. Pickadook, Shutterstock

Advertisement

You May Also Like:

My dad offered to sell me his rental property but the tenants haven't paid in months. I love that place, but is the risk too high?

I’m 62 and just learned about the “$1,000-a-month rule” for retirement. Now, I'm worried I haven't saved enough. What should I do?

Sources: 1, 2, 3, 4, 5, 6, 7, 8, 9, 10, 11, 12, 13, 14, 15


READ MORE

Neighbor Lawn Intog

I'm trying to sell my house but my neighbour never mows his lawn or cleans up his property, and it's affecting the value of my home. What can I do?

Curb appeal doesn’t stop at your property line, and unfortunately, your neighbor’s overgrown lawn or junk pile can absolutely hurt your sale price. But what can you do about it?
December 11, 2025 Jesse Singer
Credit Card

Ways to Improve Your Credit Score Fast

Stuck in a credit rut? A low credit score can feel like a roadblock but, hey, it’s not unsalvageable. There are things you can do that’ll boost your score and your confidence pronto.
April 15, 2025 Miles Brucker
Golf

11 Leisure Time Activities Of The World’s Richest People

Apart from business deals, bank accounts, and monitoring the stock market, some billionaires have hobbies that are surprisingly down-to-earth—or outright unexpected. So, what are the richest people’s favorite hobbies?
December 23, 2024 Peter Kinney
Propvalues-Int

Surprising Things That Decrease Your Property Value

If you’re trying to sell your home, there are many things that can decrease your property value—but even the experts were surprised by potential buyers’ biggest turn-off.
December 4, 2025 JK
Shared Fence Intog

I bought a house with a shared fence. My neighbor doesn't take care of his side and now he wants me to pay for his upgrades. What are my options?

Buying a house with a shared fence might seem simple—it's just a fence what could go wrong? Well, it's all fun and games until your neighbor neglects their side and suddenly wants you to pay for upgrades.
December 9, 2025 Jesse Singer
Pokemoncards-Int

Rare And Expensive Pokémon Cards Still Hiding In People's Closets

The world of Pokémon card collecting has grown from a childhood hobby into a high-stakes game for serious collectors, investors, and nostalgic fans alike. From one-of-a-kind tournament trophies to mysterious misprints and elusive promos, these cards are the crown jewels of the Pokémon Trading Card Game.
December 5, 2025 Quinn Mercer


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕