The 20% Discount That Could Cost You Much More
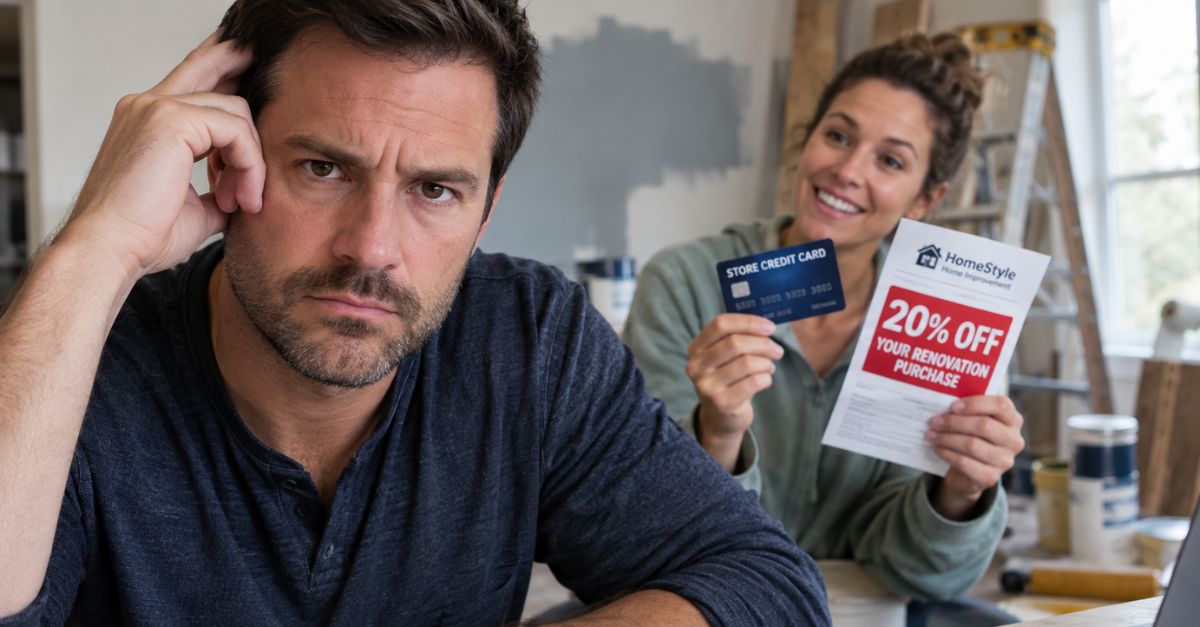
Opening a store card for a one-time renovation discount can seem harmless. But if your partner opened that account in your name without your permission, one quick decision at the checkout counter has the potential to turn into identity theft, credit damage, and a legal mess inside a marriage if you aren't careful.
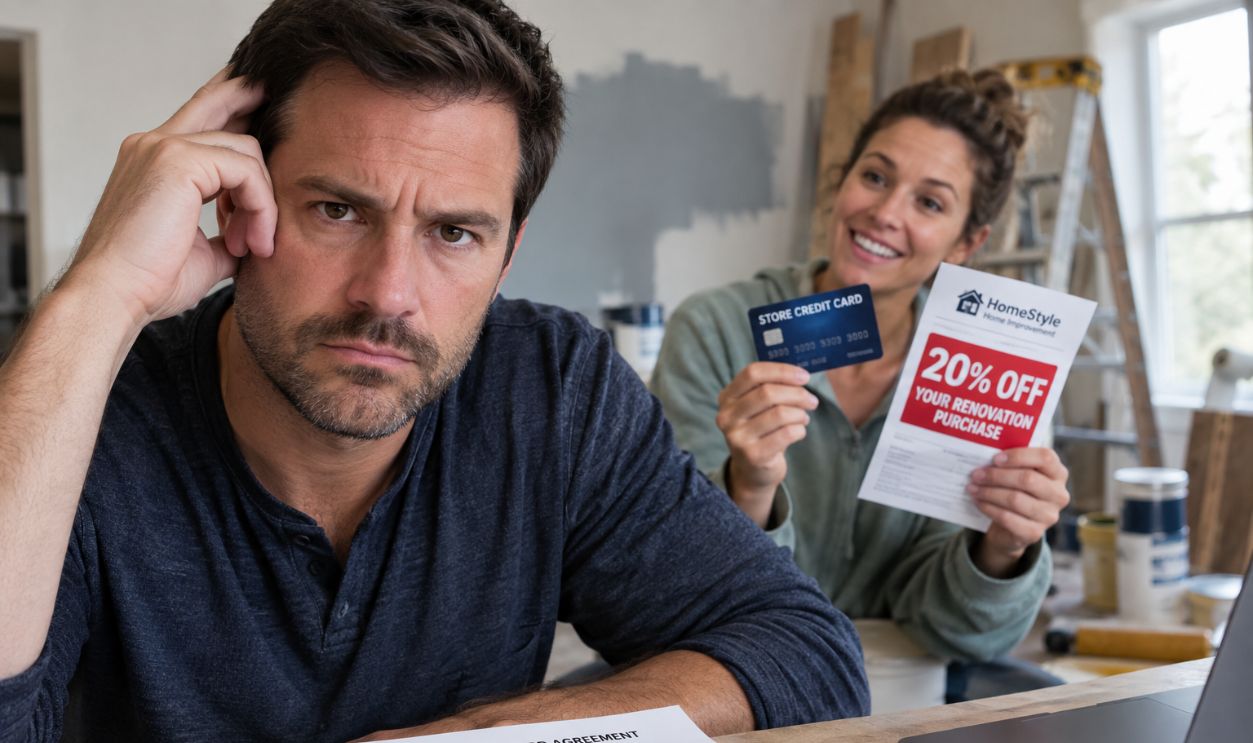
Marriage Is Not Automatic Permission
Couples often share bank accounts, mortgages, and household bills, so it is easy to assume one spouse can open credit for the other. Usually, that is not how consumer credit works. A lender generally needs the actual applicant’s consent, and if you never gave it, the account can be disputed as fraud, marriage or no.
It Can Start With A Shock
Many people find out about this kind of account after spotting a hard inquiry, getting a new card in the mail, or seeing an unfamiliar balance on a credit report. The Fair Credit Reporting Act gives you the right to review your credit files and dispute inaccurate or fraudulent information. If you found the card only after the purchase was made, acting fast can help limit the damage.
A Store Card Is Still Real Credit
Retail cards can feel less serious than a Visa or Mastercard, especially when they are pitched for cabinets, flooring, or appliances. But a store card is still a credit account. It can trigger a hard inquiry, affect your credit use, and create late-payment risk. That 20% same-day discount can look tiny next to years of credit trouble if the account goes bad.
The Fine Print Can Bite
Store credit cards often come with very high interest rates. The Consumer Financial Protection Bureau has warned consumers to pay attention to deferred-interest promotions and expensive terms on retail cards. If the renovation balance was not paid off quickly, the checkout discount may have been wiped out by interest charges.
Your Credit Score Can Drop Fast
A new account can lower the average age of your credit history and add a hard inquiry to your report. A big renovation charge can also drive up your credit utilization, which matters a lot in many scoring models. If payments are missed, the damage can get much worse and be much harder to fix.
 LIGHTFIELD STUDIOS, Adobe Stock
The Law Gives You Some Fast Options
The FTC advises identity theft victims to move quickly by reporting the fraud and creating a recovery plan through IdentityTheft.gov. You can also place a fraud alert or a credit freeze with the major credit bureaus. A fraud alert tells lenders to take extra steps to verify your identity. A freeze blocks access to your credit report entirely.
A Credit Freeze Is Often The Best First Step
The CFPB explains that a credit freeze can help stop new accounts from being opened in your name because most lenders want to review your credit report before approving an application. Since federal law changed in 2018, freezes are free at the nationwide credit bureaus. If you are worried your information could be used again, this is one of the smartest moves you can make.
You Also Need To Check All Three Credit Reports
You can get free credit reports through AnnualCreditReport.com, the site authorized by federal law. Go through each report carefully and look for unfamiliar accounts, inquiries, addresses, and phone numbers. One surprise store card can sometimes point to a bigger pattern, especially if someone has already used your personal information once.
Dispute The Account In Writing
The FTC and CFPB both recommend documenting identity theft and contacting the card issuer directly. Tell the lender the account was opened without your authorization and ask it to close the account and remove charges you did not approve. Keep copies of letters, statements, screenshots, and delivery confirmations. If the dispute drags on, that paper trail matters.
The Police Report Question Gets Messy At Home
Many fraud cases are easier to sort out when victims file an identity theft report and sometimes a police report. But when the person involved is your spouse, that choice comes with emotional and legal consequences that go far beyond credit repair.
You May Not Be On The Hook For The Debt
The FTC says identity theft victims should not assume they owe the money. If the account was truly opened without your permission, you may be able to have it treated as fraud instead of marital spending you simply did not agree with. That difference matters even more if the balance is large and the renovation was financed over time.
But State Laws Can Complicate Things
Unauthorized credit and marital debt do not always get sorted out cleanly, especially if the purchase improved the family home. In community property states and during divorce cases, questions can come up about who benefited from the purchase and how household debts should be split. That does not erase the fraud issue, but it does mean it may be worth talking to a consumer lawyer or family law attorney.
Home Improvement Financing Makes This Easier To Imagine
Retail financing is pushed hard on home projects because renovation bills are big and sticker shock is real. A cashier offering 10%, 15%, or 20% off a large purchase can lead to snap decisions. When a couple is already stressed by contractor bills and budget overruns, bad judgment at the register can quickly turn into credit fraud.
This Is A Trust Problem Too
Opening credit in someone else’s name is not just a paperwork issue. One spouse crossed a line involving legal identity and financial risk. Even if the purchase was for the household, it raises hard questions about consent, secrecy, and whether this was the first time something like this happened.
Ask The Hard Follow-Up Questions
Was this really a one-time move to get a same-day discount, or part of a larger pattern of hidden debt? Are there other cards, balance transfers, or personal loans you do not know about? One unauthorized account can be a warning sign of a much bigger financial problem inside the marriage.
Pull The Thread Carefully
Review bank statements, credit card statements, loan accounts, and your full credit reports before jumping to conclusions. Look for unfamiliar autopay withdrawals, cash advances, or promotional financing tied to the renovation. The worst mistake is focusing only on the one-time 20% discount while missing much larger hidden balances.
Call The Card Issuer Before A Payment Is Missed
If the billing cycle has already started, time matters. Reaching out to the issuer quickly may help pause collections activity while the fraud claim is reviewed. Waiting can lead to late fees, penalty APRs, and negative marks that are much harder to clean up later.
Do Not Mix Up Authorized User Status With Opening An Account
There is a big legal and practical difference between being added as an authorized user and being listed as the primary applicant. An authorized user is usually added by the real account holder. A new application in your name generally requires your consent. If your name was used as the applicant, that is much more serious than being added to an existing card.
One Retail Card Can Disrupt Bigger Plans
If you plan to refinance, buy a car, or apply for a mortgage, even one unauthorized account can create problems. Lenders may ask about new inquiries, balances, or disputed accounts. A rushed store card opened during a renovation can come back months later when you least want extra attention on your credit file.
Try To Work It Out, Set Some Guardrails
For certain couples this could be a breaking point. For others, even if one spouse is upset, it's something to work through. For cooler heads who choose the second path, put real safeguards in place. That can include frozen credit, shared account access, written budget rules, and possibly financial counseling.
If You Fight The Debt, Document Everything
Keep a dated file of every call, letter, dispute, and response from the card issuer and the credit bureaus. Save proof of when you discovered the account and what you did next. If the issue ends up in a regulatory complaint, arbitration, or court, a clear timeline can make a major difference.
Regulators Spell Out What To Do Next
The FTC’s IdentityTheft.gov process lays out recovery steps based on the kind of fraud involved. The CFPB also offers guidance on freezing credit and dealing with credit report problems. These are not vague tips. They are the practical first steps federal consumer agencies tell people to take when their identity is misused.
The Best-Case Scenario Is Still Bad
Even in the most forgiving version of this story, your spouse made a reckless decision at the register, the charges get paid, and the account is closed without lasting damage. That is the optimistic outcome. Even then, they used your identity without permission, and that deserves more attention than the discount that started it.
Were The Savings Worth It?
The 20% savings may be the smallest part of the situation compared with possible credit damage, fraud disputes, legal trouble, and the breach of trust inside your marriage. If this happened to you, treat it as both a consumer protection issue and a relationship red flag, because the receipt is only where the story starts.