The Cash-Car Temptation
Some people live by a firm "no car payment" creed. To them, paying cash for a car is neat, simple, and comes without strings. No monthly payment, no lender, no interest charges hitting every month. But if that cash has to come from selling investments that are down, the decision gets a lot more complicated.
Why This Hits A Nerve
Money fights in a marriage are rarely just about math. One spouse may see a car loan as debt to avoid at all costs. The other may see selling beaten-down investments as locking in a loss at the worst time. Both reactions make sense, which is why this choice is worth slowing down and looking at carefully.
What Borrowing Looks Like Right Now
Auto loans are not cheap right now. The Federal Reserve has kept its target federal funds rate at 4.25% to 4.5% since December 2024, after cutting rates late in 2024 following earlier hikes. When benchmark rates stay high, borrowing costs across the economy, including car loans, usually stay high too.
Car Loans Come With Real Bite
According to Experian’s State of the Automotive Finance Market report for the first quarter of 2025, the average rate on a new-car loan was 6.73%, while the average rate on a used-car loan was 11.87%. Experian also found that the average monthly payment hit $745 for new vehicles and $521 for used ones. Those numbers help explain why paying cash feels so appealing.
 Natthawadee Jana, Shutterstock
Car Prices Are Still A Major Factor
Edmunds reported in 2024 that the average transaction price for a new vehicle stayed above $47,000. On a purchase that big, even a moderate interest rate can add up fast. For many buyers, the real choice is between one painful hit now or a different painful hit spread out over time.
Selling At A Loss Has A Price
If your investments are down, selling them now turns a paper loss into a real one. That does not always mean selling is wrong. It does mean this is not really a simple cash-versus-loan decision. It is more like choosing between a certain loss today and interest costs over time.
The Tax Break Can Help
There is one thing that can make selling losing investments sting a little less. The IRS lets investors use capital losses to offset capital gains, and if losses are bigger than gains, up to $3,000 can usually be deducted against ordinary income each year. So a sale at a loss may create a tax benefit, not just a financial hit.
Tax-Loss Harvesting Helps, But Only So Much
This move is often called tax-loss harvesting, and it can be useful when done carefully. But it does not erase the loss. The value of the deduction depends on your tax situation, and in most cases it will not fully make up for selling after your investments have fallen.
The Wash Sale Rule Matters
If you sell an investment for a loss and buy back the same or a substantially identical security within 30 days before or after the sale, the IRS wash sale rule can disallow the loss. A lot of investors get tripped up here. If the plan is to sell for car cash and then rebuild the same position quickly, timing matters.
What A Loan Actually Costs
Say the car costs $30,000 and you finance it for five years at about 6.7%. The total interest could end up in the thousands over the life of the loan, depending on the exact terms and the down payment. That is real money, but it still needs to be weighed against the investment loss you would lock in by selling.
Start With The Size Of The Loss
If selling investments means taking a $1,500 loss to avoid $5,000 in loan interest, paying cash could make sense strictly on the numbers. If the loss would be $10,000 and the interest cost is much lower, the picture changes fast. In many cases, the smartest move comes down to comparing those two numbers side by side.
Then Think About Recovery
Not all losses are the same. If the investments are part of a diversified long-term portfolio, there is at least a fair chance they could recover with time. Selling them to buy a car, which will almost certainly lose value, means trading a possible rebound for an asset that usually drops the minute you drive it off the lot.
A Car Is Still Not An Investment
That point is at the center of this whole debate. A broad stock or bond fund may recover over time. A car is usually something you use while it steadily loses value. Using depressed investments to buy a depreciating asset can be awkward financially, even if it feels good emotionally.
Liquidity Has Real Value
Keeping cash or investments available can matter more than people think. Once you put a large lump sum into a car, that money gets much harder to reach without selling the car or borrowing elsewhere. In uncertain times, flexibility can be worth a lot.
Emergency Savings Come First
Before picking cash or financing, a couple should make sure the household has enough emergency savings. Financial planners often suggest keeping three to six months of expenses in a liquid emergency fund, though the right number depends on job stability and other risks. If selling investments leaves the family exposed, avoiding a car loan may not be worth it.
Other Debt Can Change Everything
If you already carry credit card debt at much higher rates, paying cash for a car can backfire. A household that drains savings or investments for a vehicle and then has to lean on 20% APR credit cards may come out worse. The full balance sheet matters, not just the car loan by itself.
Your Credit Score Counts Too
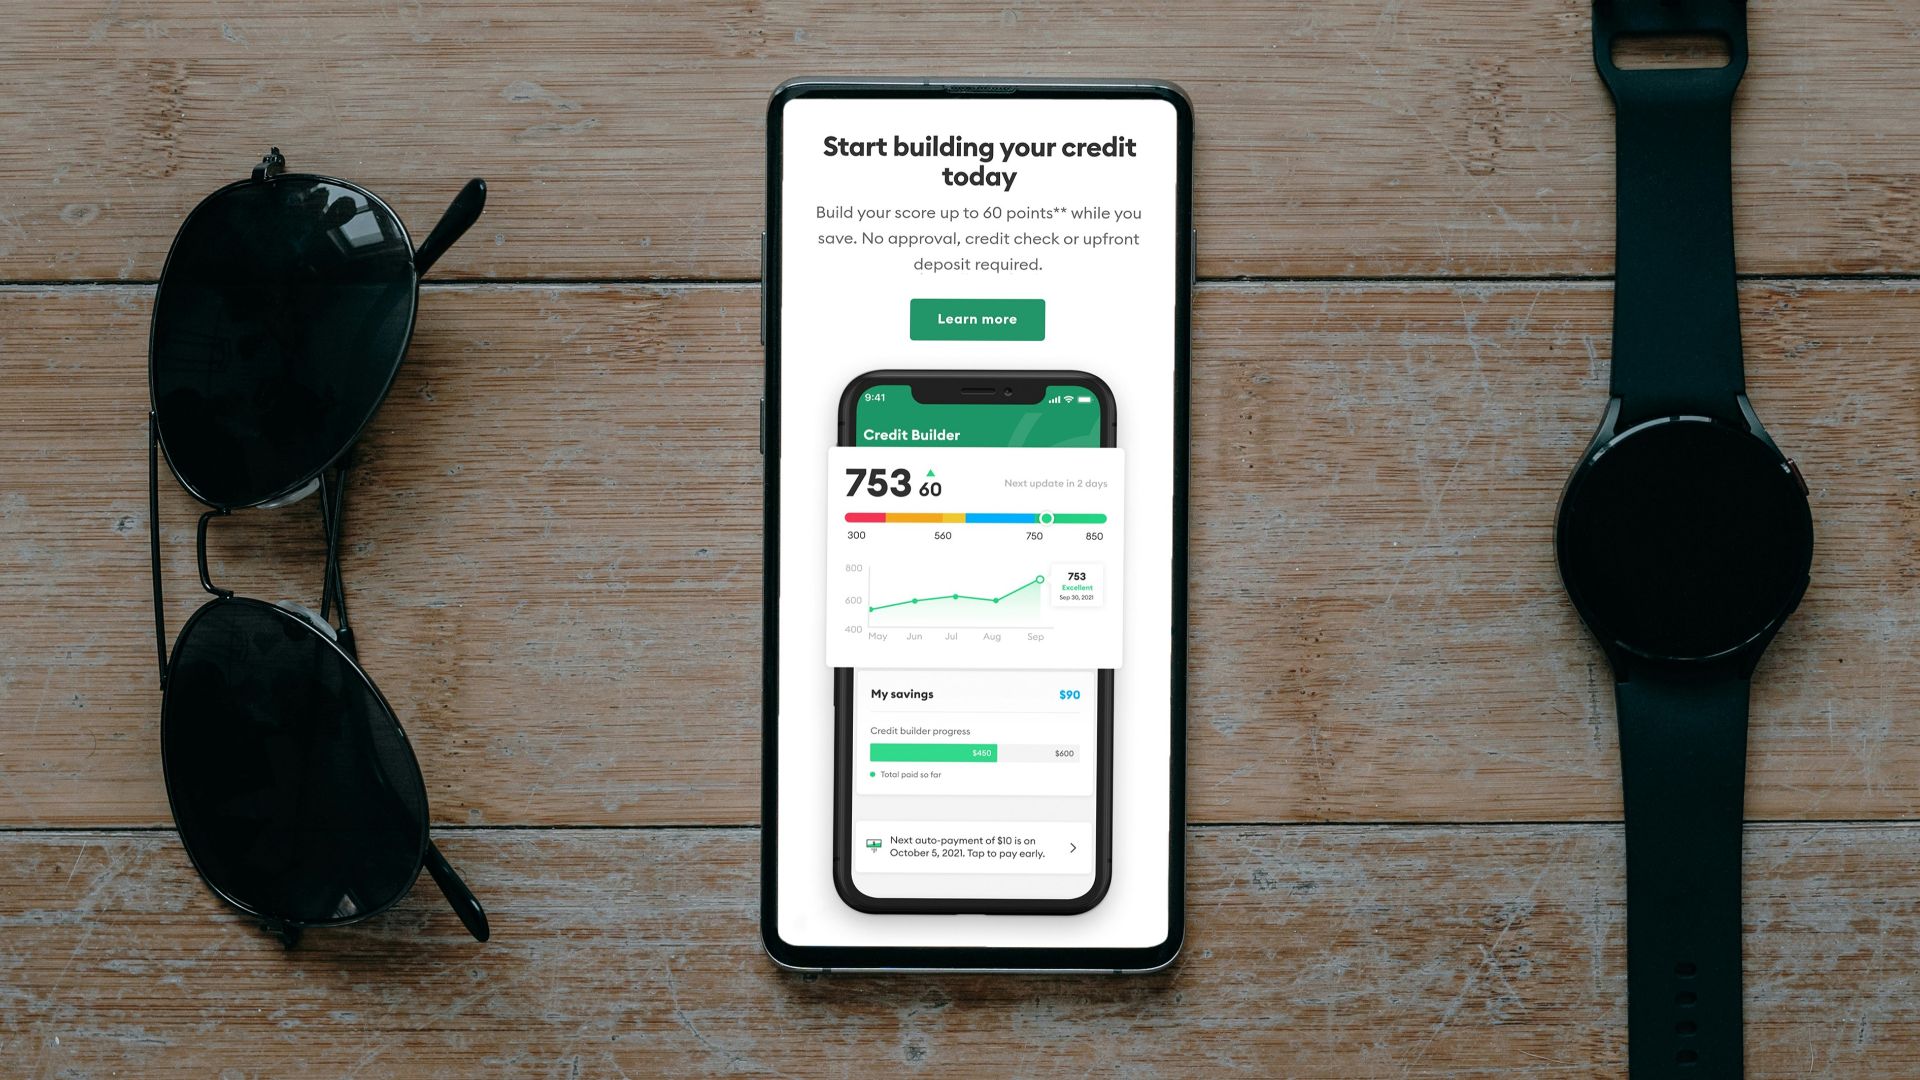
Experian noted big differences in loan terms based on credit quality. Buyers with strong credit usually get better rates than buyers with weaker credit. If your likely rate would come in well below the average used-car rate, financing starts to look a lot more reasonable.
New And Used Are Two Different Worlds
The gap between new-car and used-car loan rates is hard to ignore. Experian’s first-quarter 2025 data showed average used-car rates at 11.87%, compared with 6.73% for new cars. If you are buying used and looking at a steep rate, the case for avoiding a loan gets much stronger.
There Is A Middle Ground
This does not have to be a winner-take-all argument. A bigger down payment paired with a smaller loan can cut interest costs without forcing you to sell all your investments at a loss. Often the best answer is the one that leaves both sides with fewer regrets.
 Korawat photo shoot, Shutterstock
Shorter Loans Limit The Damage
If you do finance, the loan term matters a lot. A shorter term usually means a higher monthly payment, but less total interest. That can be a solid middle path for couples who do not like debt but also do not want to sell investments at a bad time.
Shop For The Loan As Hard As You Shop For The Car
Many buyers spend hours haggling over the car price and barely compare financing offers. That is a mistake. Banks, credit unions, and manufacturer finance arms can all offer very different terms. A low promotional rate could change the whole decision.
Do Not Let Fear Make The Call
This is where smart people often get stuck. Debt can feel dangerous, especially after years of warnings about interest and overspending. But market losses can also create a strong urge to sell and make the pain stop. Neither feeling should make the choice on its own.
Ask What The Investments Were Meant To Do
If these investments were meant for retirement or another long-term goal, cashing them out for a car can carry a hidden cost. The issue is not only the loss you lock in today. It is also the future growth you may be cutting off.
When Paying Cash Can Make Sense
Paying cash can be a strong choice if the loss is fairly small, the tax benefit helps, the loan rate would be high, and the purchase would not weaken your emergency cushion. It can also make sense if your household cares a lot about simplicity and lower monthly bills. In that setup, avoiding a loan may be worth it.
When Financing Is Probably Better
Financing often wins when selling would lock in a large loss, especially if the investments are diversified and meant for long-term growth. It also tends to make more sense when you can qualify for a decent rate and still keep enough liquidity on hand. Put simply, keeping flexibility can be more valuable than getting rid of one monthly payment.
The Best Answer Is Usually A Comparison, Not A Belief
The biggest mistake is turning this into a moral fight over debt versus cash. It is really a math and planning question. Compare the likely loan interest, the size of the investment loss you would realize, the tax benefit you might get, and the effect on your cash cushion before deciding.
 Vodafone x Rankin everyone.connected, Pexels
A Useful Rule Of Thumb
If avoiding the loan means selling assets that are deeply underwater and important to your long-term plan, slow down. If the investments are only slightly down, the loan offer is expensive, and your finances stay solid after the sale, paying cash may be the cleaner move. There is no one-size-fits-all answer, but the tradeoff is real.
The Bottom Line For Couples Having This Fight
Your wife is right to be wary of an expensive auto loan in a high-rate market. You are right to be wary of selling investments at a loss to buy something that will keep dropping in value. In many cases, the best answer is a compromise that protects liquidity, limits interest, and avoids turning a rough market stretch into a permanent loss unless the numbers clearly support it.
 AI25.Studio AI GENERATIVE, Pexels