Buyhouse2025Internal

Buying A House In 2025: Is Now A Smart Time Or A Financial Trap?


May 5, 2025 | Sammy Tran

Buying A House In 2025: Is Now A Smart Time Or A Financial Trap?


For many Americans, homeownership remains the cornerstone of financial stability and personal achievement. But in 2025, with mortgage rates still high, inventory tight, and affordability stretched, the question lingers: is now the right time to buy a house—or is it a trap that could burden buyers with years of financial strain? Understanding the forces at play is key to making a confident, informed decision.

Mortgage Rates Are Still Elevated

As of 2025, mortgage rates hover around 6.5% to 7% for a 30-year fixed loan—significantly higher than the 3% rates seen just a few years ago. These elevated rates dramatically increase monthly payments and long-term interest costs. Buyers need to consider whether locking in at these levels makes sense or whether waiting for future rate drops is the wiser move.
tkochtkoch, Pixabay

Advertisement

Home Prices Remain Stubbornly High

Despite predictions of a market correction, home prices in many regions remain high due to persistent low inventory and strong demand. In metro areas like Austin, Miami, and San Diego, prices have barely budged or even ticked upward. While price growth has slowed, many buyers are still being asked to pay top dollar for homes that may not see much appreciation in the short term.

Inventory Is Still Tight

New construction has failed to keep pace with demand, and existing homeowners are reluctant to sell because they’re locked into lower mortgage rates. The result? Fewer homes on the market and more competition among buyers. This tight inventory continues to drive bidding wars in desirable neighborhoods, putting additional pressure on already stretched budgets.

Wages Have Not Kept Up With Costs

While inflation has cooled somewhat, wage growth has not kept pace with rising housing costs. Many buyers now find themselves unable to qualify for the homes they could afford just a few years ago. This affordability gap forces difficult choices: compromise on location or space, or continue renting and hope the market shifts.

Alena DarmelAlena Darmel, Pexels

Advertisement

Renting Isn’t Always Cheaper

Though renting may offer flexibility, it isn’t always more affordable. In cities like Denver, Phoenix, and Boston, rents remain high and vacancy rates low. Over time, renters miss out on the equity-building benefits of ownership. However, in the short term, renting can provide stability without the upfront costs and long-term commitment that come with buying a home.

Some Markets Offer Opportunities

Not all housing markets are overheated. In smaller cities and rural areas, prices have cooled or even declined, offering opportunities for savvy buyers. Markets in the Midwest, parts of the South, and some Rust Belt towns now offer relative bargains, especially for remote workers or retirees looking for affordability and space.

First-Time Buyers Face Extra Challenges

First-time buyers, especially those without family support or substantial savings, are feeling squeezed the hardest. High down payments, stiff competition, and tight lending standards create significant barriers to entry. Government programs like FHA loans and first-time buyer tax incentives can help, but they may not be enough to offset the broader market pressures.
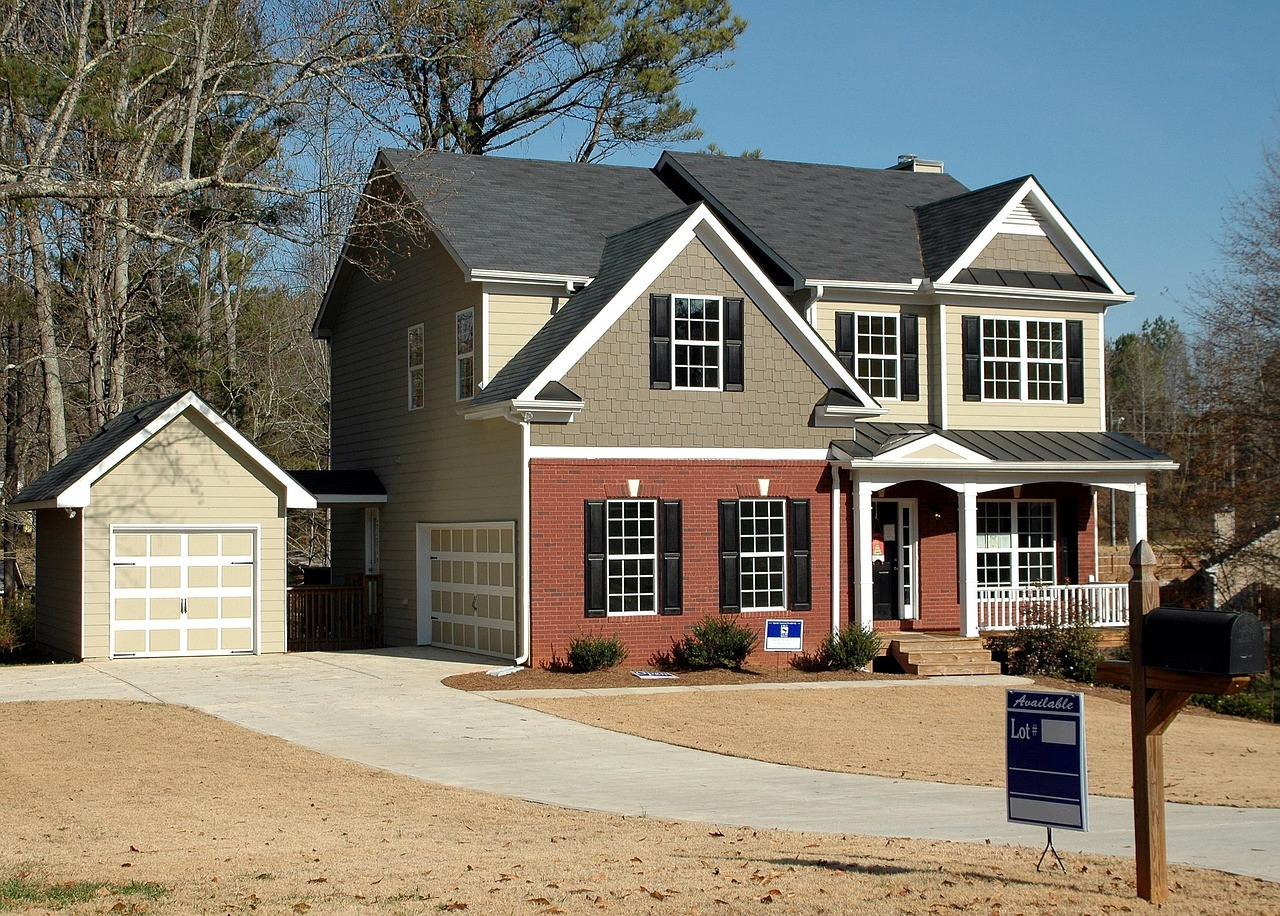
paulbr75paulbr75, Pixabay

Advertisement

Buying As A Long-Term Investment

If you're buying a home with the intention of staying for 7 to 10 years or longer, current conditions may be manageable. Even if home values plateau or dip in the short term, long-term appreciation and principal paydown can eventually build equity. But speculative buyers or short-term flippers should exercise caution—this market is not friendly to quick profits.

Consider Your Personal Financial Picture

Timing the housing market perfectly is nearly impossible. Instead, buyers should assess their own financial readiness. A stable job, manageable debt, a solid emergency fund, and a long-term outlook matter more than market timing. If you can comfortably afford the mortgage and plan to stay put, buying in 2025 can still make sense.

Final Thoughts: Trap Or Timing?

There’s no universal answer to whether 2025 is the right time to buy a home. For some, it’s a smart move grounded in long-term goals and personal stability. For others, the current market may present more risk than reward. The key is doing your homework, being realistic about your budget, and resisting the pressure to buy just because the market feels uncertain.

You May Also Like:

Surprising Things That Increase Your Property Value

Understanding Mortgage Prepayments
4 Renovations That Raise Your Home's Value

Sources: 1, 2, 3


READ MORE

AI-generated image of concerned woman in chair with arguing couple behind her

My mother named me executor, but my siblings keep demanding constant updates. How much do I legally have to tell them?

Learn how much information an executor must legally share with siblings, when beneficiaries can demand updates, and how to balance transparency, privacy, recordkeeping, and estate administration responsibilities during probate proceedings.
September 15, 2026 Peter Kinney
Rss Thumb - House Left Disagreement

My father helped one child buy a house, but never documented it as a loan. Can the estate still treat it that way?

A father helped one child buy a house without documenting the money as a loan. Learn when a U.S. estate may still collect it, what evidence matters, and how loans, gifts, and inheritance advancements differ.
September 14, 2026 Jack Hawkins
AI-generated image of an executor deciding on if a tenant has to pay the estate rent for living in an inherited house.

My brother wants to live in our inherited house while we decide what to do. Should he pay rent to the estate?

Letting one sibling stay in the family home can seem like the easiest solution while everyone decides whether to sell, rent, or keep it. Then property taxes, utilities, repairs, and questions about fairness start piling up.
September 15, 2026 Peter Kinney
The $9,000 Family Shock

My adult son used my credit card for a $9,000 purchase without asking and says he'll pay me back eventually. Do I dispute the charge or treat it as family debt?

You check your credit card statement and there it is. A $9,000 purchase you did not approve, made by your adult son without asking. The emotional sting is real, but the financial decision you make next can affect your rights, your credit, and possibly even your relationship.
September 15, 2026 Miles Brucker
woman holding folders and calculator, with a man in the background doing financial calculations

My fiance earns twice what I do but wants every household expense split exactly 50/50. Is equal actually fair when incomes are wildly different?

Money arguments rarely begin with a dramatic blowup. More often, they start with one stubborn idea, like splitting every bill exactly down the middle even when one partner earns far more. If your fiance makes twice your income and still wants a strict 50 50 household budget, the real question is not whether it is equal, but whether it is fair.
September 15, 2026 Miles Brucker


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team