The Hidden Side Of Retirement Planning: Healthcare
You’ve worked hard, saved smart, and now you’re sitting on a solid nest egg. But as the retirement horizon comes into focus, one big, uncomfortable question keeps popping up: What about healthcare? The truth is, even with close to a million saved, medical costs can sneak up and take a bite out of your golden years. The good news? You’ve got options, and with some smart planning, you can make your money last and your health coverage solid. Let’s dive into how to actually plan for the medical side of retirement without losing your cool (or your savings).
The Not-So-Fun Fact About Healthcare In Retirement
Healthcare is one of those things we all know is expensive, but few of us realize how expensive until we start doing the math. According to Fidelity’s 2024 estimate, the average 65-year-old couple retiring today will need about $315,000 (after taxes) to cover healthcare expenses in retirement, and that’s assuming you’re eligible for Medicare. For single retirees, it’s about $157,000. And if you retire before age 65, when Medicare kicks in? Expect to pay much more out of pocket until then.
Medicare Isn’t Free (Surprise!)
A lot of people think Medicare is this magical, free government plan that covers everything. Spoiler: it doesn’t. You’ll still pay monthly premiums, deductibles, copays, and potentially prescription costs. Part B (doctor visits and outpatient care) costs about $175 a month for most retirees in 2025. Add in Part D (prescriptions), Medigap or Advantage premiums, and it’s easy to see $400–$600 per person per month. Multiply that by 12 months and several years; it adds up fast.
The “Gap Years” Problem
If you’re planning to retire before age 65, you’ll need to bridge the gap before Medicare starts. This is where many retirees get blindsided. Marketplace insurance (through Healthcare.gov) or COBRA from your old employer can cost thousands per month for a couple, especially if you want decent coverage. That means you might need to plan for two to five years of expensive private coverage, or consider part-time work that comes with health benefits.
How Much Should You Budget?
Think of healthcare as a line item in your retirement budget, not an afterthought. A general rule of thumb is to allocate 15–20% of your retirement spending toward healthcare. So if you expect to spend $80,000 per year in retirement, plan for about $12,000–$16,000 annually for medical costs (including premiums, prescriptions, and out-of-pocket expenses).
Health Savings Accounts (HSAs): Your Secret Weapon
If you’re still a few years away from retirement and have access to a Health Savings Account, use it! HSAs are the only account that gives you a triple tax advantage: contributions are tax-deductible, growth is tax-free, and withdrawals for medical expenses are also tax-free. If you’re 60 now, you can contribute up to $8,300 per year (for families in 2025) and let it grow until you need it. Even if you retire soon, that money can help offset Medicare premiums, long-term care, or other medical costs later.
Don’t Forget Long-Term Care
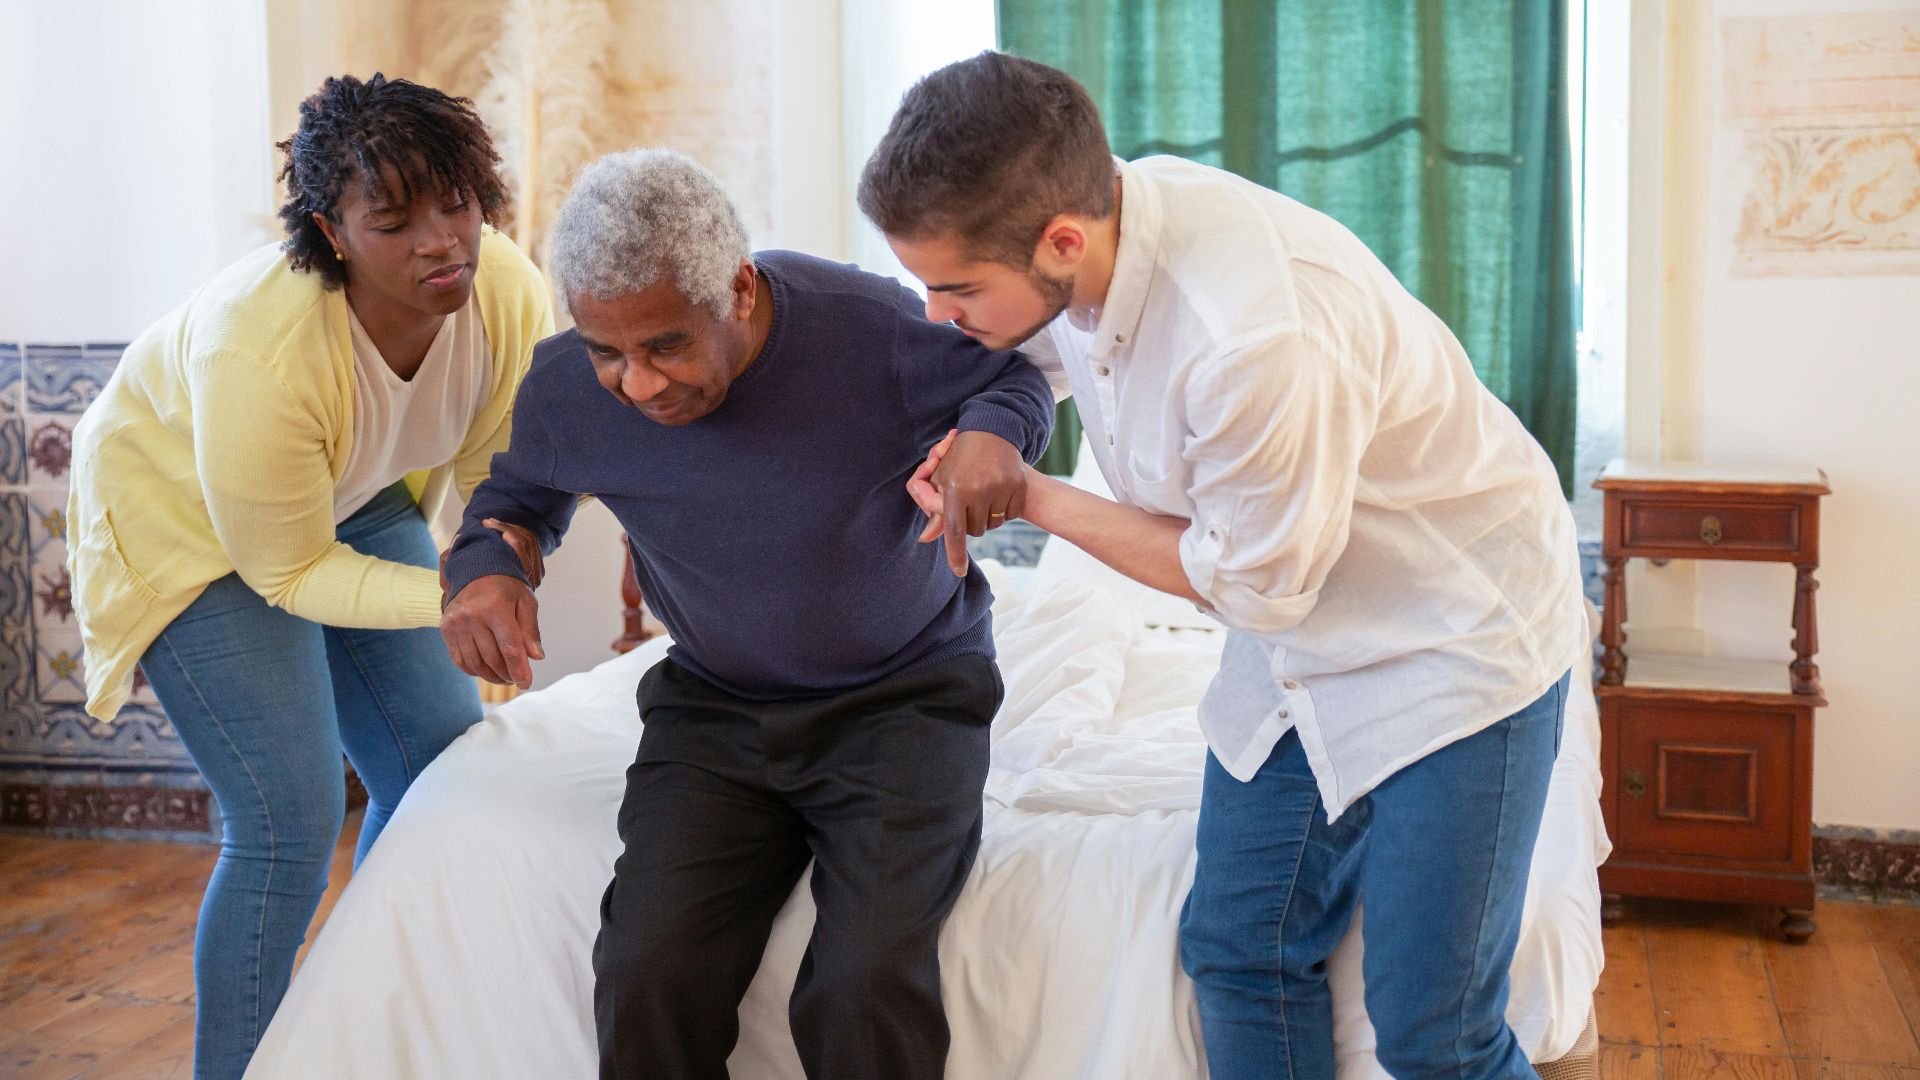
The average cost of a private room in a nursing home is over $100,000 per year, and even part-time home care can run $60,000 annually. Medicare generally doesn’t cover long-term custodial care, that’s on you. Long-term care insurance (LTCI) can help, but it’s pricey. Another option is a hybrid life insurance policy that includes a long-term care benefit. It’s worth running the numbers early while you’re still insurable.
Consider Delaying Retirement (Just A Bit)
Retiring at 62 sounds nice, but waiting until 65 or later can make a huge difference. You’ll be Medicare-eligible, potentially qualify for lower premiums, and give your savings a few more years to grow. Even part-time consulting or freelancing can provide enough income (and sometimes benefits) to keep your healthcare affordable until then.
Optimize Your Medicare Choices
Once you’re eligible for Medicare, you’ll face a maze of options: Original Medicare, Medicare Advantage, Medigap plans, and Part D drug coverage. The right combination depends on your health, travel plans, and budget. Original Medicare + Medigap offers predictability but can cost more upfront. Advantage plans are cheaper monthly but can have higher out-of-pocket costs later. Working with a licensed Medicare advisor can help you avoid costly mistakes.

Plan For Inflation (Yes, Healthcare Has That Too)
Healthcare costs rise faster than general inflation, typically about 5–6% per year. That means the $12,000 you budget today could easily become $20,000 in a decade. Make sure your retirement projections assume rising healthcare costs so you’re not blindsided later.
Taxes Still Matter After You Retire
How you withdraw money affects how much you keep. Pulling from a traditional IRA or 401(k) means paying income tax on those withdrawals, which also affects how much you’ll pay for Medicare premiums (the dreaded IRMAA surcharge). To manage this, spread withdrawals between taxable, tax-deferred, and Roth accounts to keep your taxable income in a lower bracket.
The Power Of Roth Accounts
If you have a Roth IRA or Roth 401(k), withdrawals are tax-free, which can help you avoid Medicare surcharges and preserve more of your cash flow for healthcare costs. Even partial Roth conversions before retirement can pay off in the long run.
 Photo By: Kaboompics.com, Pexels
Don’t Skip Preventive Care
It sounds obvious, but staying healthy is the cheapest form of healthcare. Regular checkups, exercise, balanced diet, and preventive screenings can help you avoid major costs later. Medicare covers most preventive services, but you can start good habits long before 65 to make a real difference.

Explore State And Community Programs
Depending on your income, some states offer help with Medicare premiums or prescription costs. There are also nonprofit and community programs that help retirees afford medications or care. It’s worth researching your state’s SHIP (State Health Insurance Assistance Program) to see what resources are available.

Work A Little, Gain A Lot
Even part-time work in retirement can give you access to affordable employer healthcare. Some companies offer retiree-friendly jobs with benefits; think retail management, universities, or government contracts. Plus, staying engaged and earning a little extra helps stretch your savings.
Think About Where You Live
Healthcare costs vary wildly by location. Retiring in Florida might sound great, but insurance premiums and medical expenses can be higher than in, say, North Carolina or Texas. Before choosing a retirement destination, research local healthcare costs and access to hospitals or specialists.

Consider A Healthcare-Specific Fund
If you like structure, you can set aside a specific investment account just for healthcare. For example, dedicate $200,000 of your $900K portfolio to a conservative mix of bonds and cash that’s earmarked solely for medical expenses. That way, you’re mentally (and financially) prepared for those inevitable bills.
Get Professional Help, It’s Worth It
Healthcare planning is complicated, and it’s okay to ask for help. A fee-only financial planner or retirement specialist can build a strategy that fits your specific situation. They can model different healthcare cost scenarios, help optimize withdrawals, and find tax-efficient ways to fund care.
Don’t Panic. Adjust
If you’re behind on healthcare planning, you’re not doomed. You can delay retirement, pick up part-time work, move somewhere cheaper, or adjust spending. The goal isn’t perfection, it’s flexibility. Even with $900K, your peace of mind depends more on how you plan than how much you have.
Final Thoughts
You’ve done an amazing job saving so far. The key now is making that money work for you, especially when it comes to healthcare. Whether you invest in an HSA, delay retirement, buy long-term care coverage, or simply budget smartly, the goal is the same: stay healthy, stay covered, and enjoy your retirement without worrying that one hospital bill could derail your future. You’ve earned this stage of life, now it’s just about keeping it sustainable (and maybe a little fun).
You May Also Like:
Social Security Facts That Seniors Should Know About In 2025
If You Have $500K In Retirement Savings, This Is How Far It'll Go In Each State