When Your Neighbor Said They Were Branching Out, You Didn't Think They Meant Literally
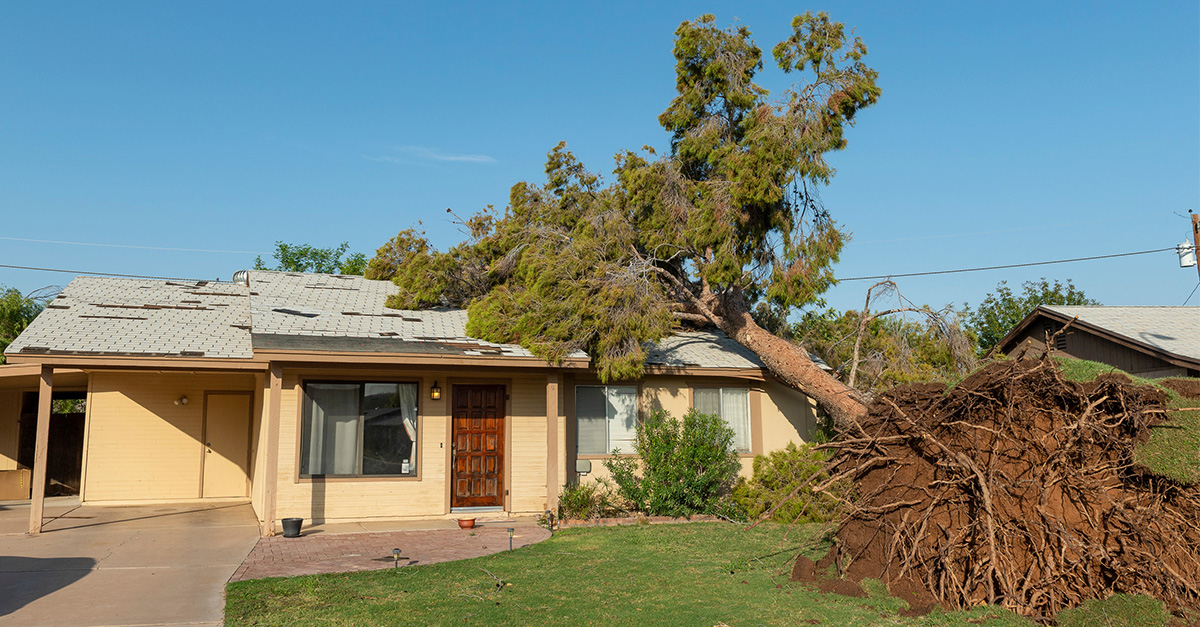
A storm blows through, and suddenly your neighbor’s oak tree is lying across your roof. The damage looks costly, but when you call your neighbor’s insurance company, they refuse to pay. Now you’re left wondering: am I stuck with the bill? The answer depends on fault, insurance rules, and how you handle the claim. This article breaks it all down, so you know your options.
Understanding Standard Homeowners Insurance
Homeowners insurance typically covers damage to your home from “perils” such as wind, fire, or hail. Falling objects—including trees—are usually included. But here’s the catch: unless negligence is proven, your own insurance usually pays first, even if the tree wasn’t on your property.
When Your Insurance Steps In
If a storm, heavy snow, or lightning caused the tree to fall, most insurers consider that an “act of God.” In those cases, your homeowners insurance will cover repairs under your dwelling protection, minus your deductible.

Why Your Neighbor’s Insurance Denied the Claim
Your neighbor’s insurer is not responsible simply because the tree came from their yard. Liability coverage only applies if the neighbor was negligent—say, they ignored a dead, rotting tree. If it was healthy and storm damage brought it down, they aren’t at fault in the eyes of insurance law.
Defining Negligence In Tree Cases
Negligence means your neighbor knew—or reasonably should have known—that the tree was hazardous and failed to take action. For example, ignoring visible rot, leaning trunks, or warnings from an arborist could establish liability.

How To Prove Negligence
Evidence is key. You might use photos of a diseased tree, testimony from neighbors who noticed the risk, or even arborist reports. Without proof, insurers will assume nature—not negligence—caused the damage.
When You Can Recoup From Your Neighbor
If negligence is proven, your neighbor’s liability coverage may reimburse you for repairs. In this case, you would usually file a liability claim against their policy. But remember: the burden of proof rests on you, not the insurance companies.
Small Claims Court As An Option
If the damage is less than your state’s small claims limit (often $5,000–$10,000), you could sue your neighbor directly. A judge may order them to reimburse you if evidence of neglect is convincing.

Filing A Claim With Your Own Insurer
Most homeowners start with their own insurance. File a claim promptly, provide photos, and get repair estimates. Even if your insurer pays, they may later pursue “subrogation” against your neighbor if negligence evidence surfaces.
What Subrogation Means For You
Subrogation is when your insurer sues the at-fault party (your neighbor) to recover the money they paid you. If successful, you may even get your deductible reimbursed. It shifts the legal battle from your shoulders to your insurance company’s.
 Photo By: Kaboompics.com, Pexels
Know Your Deductible
Unfortunately, if the damage is less than your deductible, you’re out of luck unless you prove negligence. For example, if repairs cost $1,800 and your deductible is $2,000, insurance won’t cut a check.
Trees On The Property Line
If the tree straddles the property line, things get trickier. Often, both homeowners are considered co-owners of the tree. Responsibility may be split, or it may depend on whose portion of the trunk fell. State law matters here.
Preventative Measures Matter
Courts often look at whether the tree owner acted responsibly. Regular trimming, addressing visible disease, and hiring arborists when issues arise demonstrate due diligence. Neglect, on the other hand, can lead to liability.
Dealing With Downed Tree Cleanup
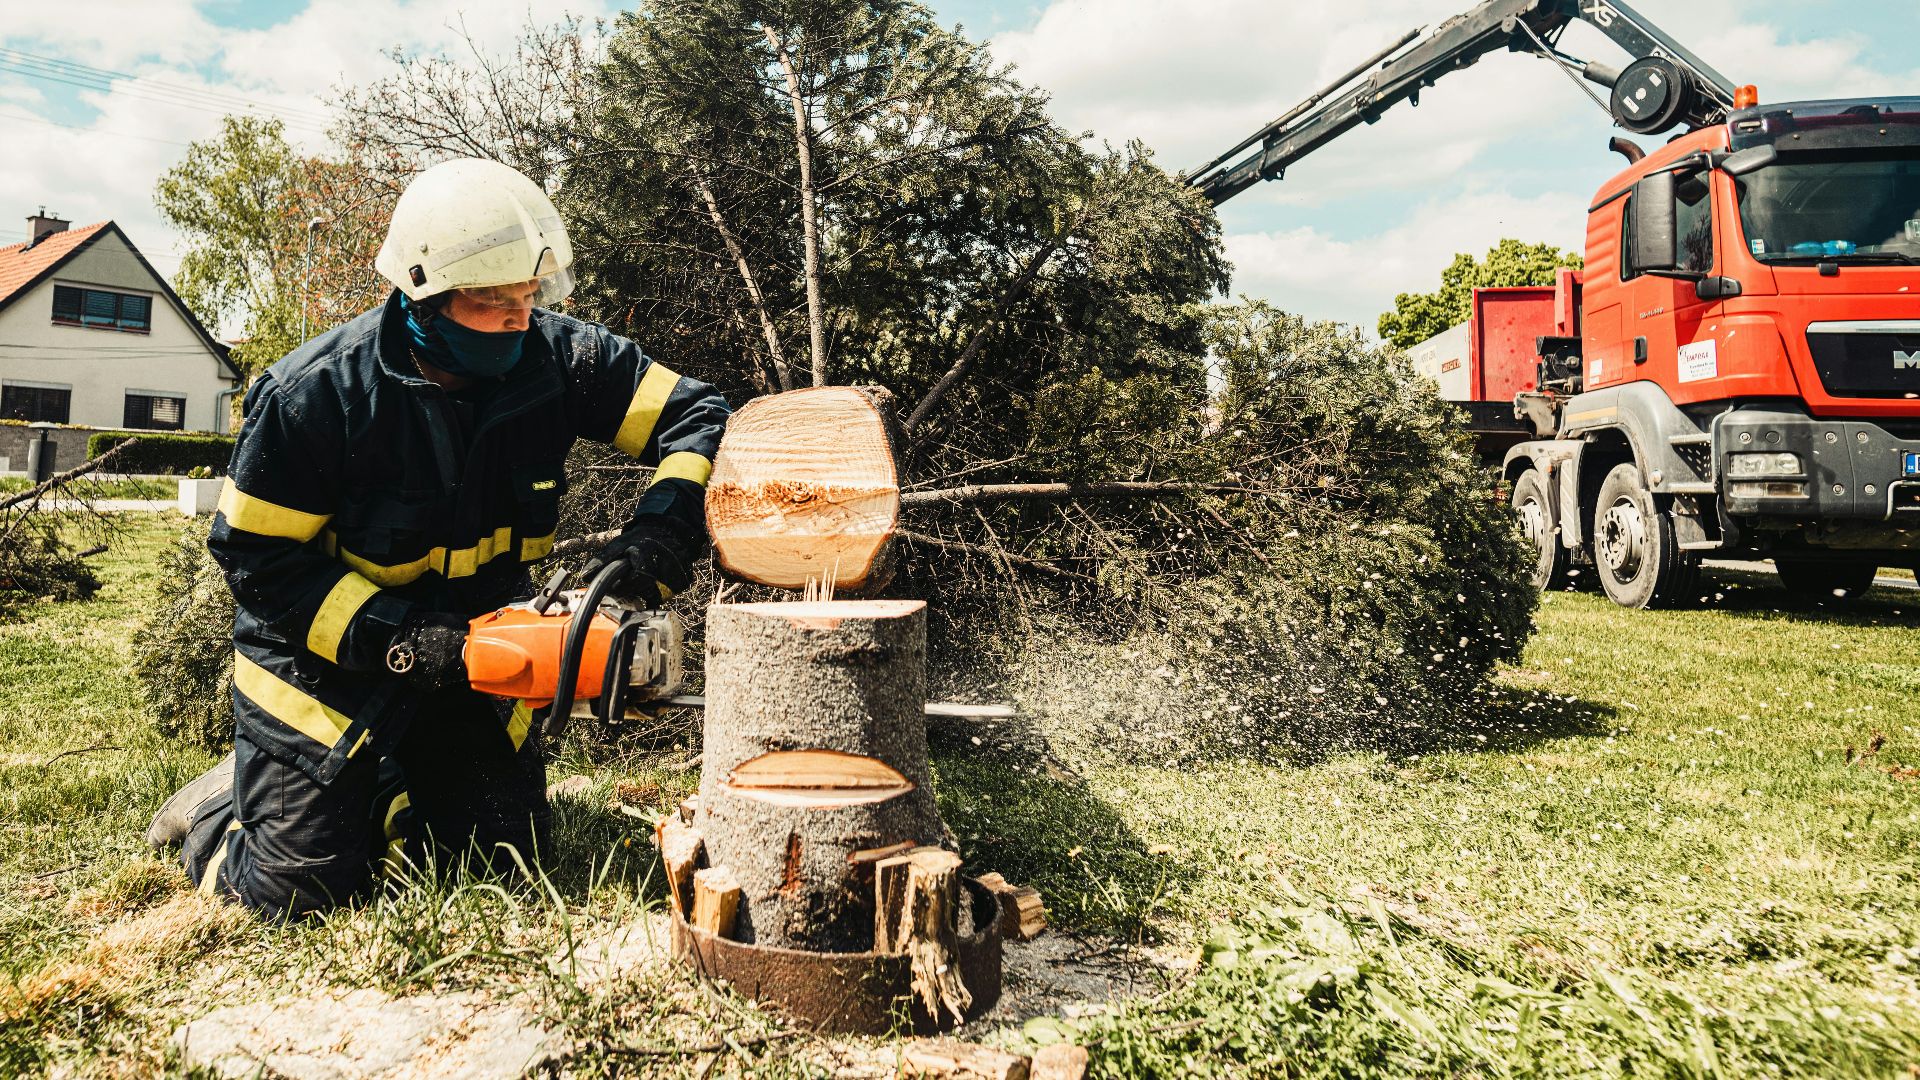
Another gray area: cleanup. Typically, each homeowner handles debris removal from their own yard, regardless of where the tree started. Your policy may cover this, but often with a limit of around $500–$1,000.
 Helena Jankovičová Kováčová, Pexels
Document Everything Immediately
Take photos of the tree before cleanup, the damage to your home, and any signs of rot. Save receipts for temporary repairs. Insurers want evidence, and courts require it if negligence is argued later.

Communicating With Your Neighbor
Keep things civil. Notify your neighbor quickly, and share insurance contact information. An adversarial approach can escalate the situation unnecessarily. Many neighbors cooperate once they understand the rules.
Working With Insurance Adjusters
Be thorough and professional with adjusters. Provide evidence, estimates, and witness statements if applicable. If you believe negligence is clear but your claim is denied, you can appeal within the insurance company.
Mediation Before Lawsuits
Some states encourage or even require mediation between neighbors before lawsuits. A neutral mediator can help resolve disputes about fault, costs, or future tree maintenance.
Preventing Future Incidents
If your neighbor’s property has questionable trees, put your concerns in writing. A polite letter or certified mail notice can establish a paper trail that shows you warned them. If the tree later falls, that letter strengthens a negligence claim.
Knowing Your State’s Laws
Laws differ across states. Some follow the “Massachusetts rule” (only negligence counts), while others follow the “Hawaii rule” (strict liability in some tree cases). Researching your state’s case law or speaking to an attorney can clarify your rights.
When To Consult An Attorney
If damages are large, your deductible is high, or negligence is obvious, consult a property damage attorney. A lawyer can guide you through insurance appeals, subrogation, or lawsuits.
You’re Not Always Stuck
While it may feel unfair that your insurance pays when your neighbor’s tree falls, the law is structured around negligence, not ownership. If your neighbor acted responsibly, you’ll likely use your own coverage. But if they ignored obvious risks, you may recoup costs through insurance, small claims court, or legal action. Document carefully, communicate openly, and know that you have multiple avenues to protect your finances.
You May Also Like:
I launched a cat yoga studio but didn't budget for cat food or cleaning. Now I'm deep in debt.
The Weirdest Shark Tank Products