The Down Payment Nobody Talked About
When my parents helped one of my siblings buy a house, nobody thought much about the paperwork. Years later, as we began sorting out their estate, that money suddenly became a major source of tension. Was it a generous gift, a loan that should be repaid, or an advance on an inheritance? The answer could affect how much every sibling receives, and it may depend on evidence nobody thought to preserve.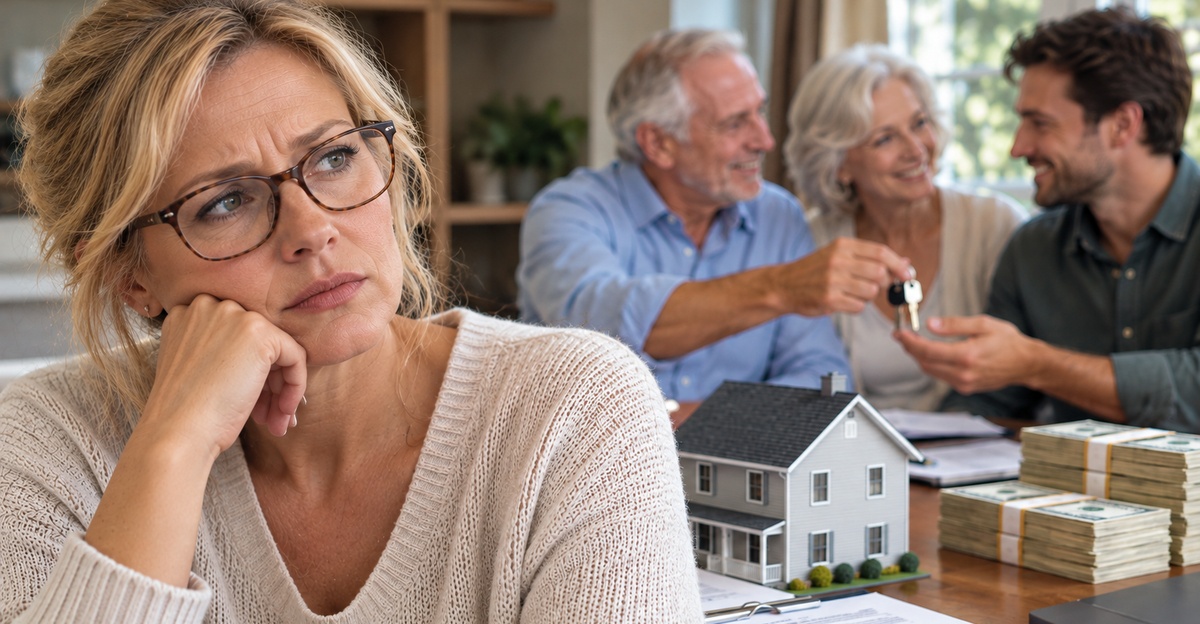 Factinate Ltd
A Family Favor Becomes An Estate Dispute
Helping an adult child buy a home can seem like a straightforward act of generosity. Problems arise when parents die without explaining whether they expected repayment or intended to adjust future inheritances. What one sibling remembers as a gift might look like an unpaid debt to another. The estate cannot resolve that disagreement simply by choosing whichever interpretation seems fairest.
The Difference Between A Gift And A Loan Matters
A genuine gift generally transfers money without an obligation to repay it. A loan creates an obligation to repay, even if the parties agreed on unusually favorable terms. An advance on an inheritance is different because it may be intended to reduce what the recipient receives from the estate later. These distinctions can lead to very different outcomes when the estate is distributed.
The Missing Paperwork Changes Everything
A signed agreement can help establish whether parents intended a payment to be repaid. Without one, the estate may need to examine bank records, correspondence, repayment history, and statements made around the transfer. An undocumented payment is not automatically a gift, but it is not automatically a loan either. The applicable law and available evidence determine which interpretation can be supported.
 Anastassia Anufrieva, Unsplash
Start With What The Parents Actually Intended
The central question is what the parents intended when they transferred the money. Did they expect their child to repay it, or were they simply helping with a home purchase? A later disagreement among siblings cannot establish an obligation that never existed. Understanding the original arrangement is therefore more important than deciding what seems fair after the parents have died.
A Bank Transfer Proves Only Part Of The Story
Bank statements may establish when the money moved, how much was transferred, and who received it. However, a transfer record alone usually does not explain whether the money was a gift or a loan. The same transaction could fit either arrangement depending on the surrounding circumstances. That makes supporting records particularly valuable when the parents can no longer explain their intentions.
The Mortgage File Could Hold A Surprise
One of the first places worth checking is the paperwork associated with the child's home purchase. The Consumer Financial Protection Bureau explains that some mortgage programs permit family-funded down payments when borrowers provide a signed statement confirming that the money is a gift rather than a third-party loan. If such a statement exists, it could be important evidence of how the payment was represented at the time.
A Gift Letter Is More Than A Formality
Mortgage lenders need accurate information about borrowers' debts and the sources of their down payments. A gift letter can help establish that the buyer was not expected to repay the contributed funds. However, the estate should examine the actual document and circumstances rather than assume every family contribution was documented the same way. The lender's file may provide a clearer picture than years of conflicting family memories.
What If The Parents Expected Repayment?
Suppose the parents transferred $60,000 with an understanding that their child would repay them over time. If that obligation remained legally enforceable when the parents died, the outstanding amount could be an asset belonging to the estate. The executor would need to investigate the debt rather than simply disregard it because the borrower is a beneficiary. Whether the estate can recover the money depends on the agreement, evidence, and applicable limitation rules.
An Interest-Free Loan Can Still Be A Loan
Parents sometimes help their children without charging interest, especially when the goal is homeownership rather than earning income. That arrangement does not necessarily eliminate the obligation to repay the principal. In the United States, however, certain below-market family loans can trigger special federal tax rules involving interest that was not charged. The IRS explains these rules in its guidance on below-market loans.
The Repayment History Might Tell The Story
Regular transfers from the child back to the parents could support the existence of a repayment arrangement. Payment descriptions, correspondence, and the timing of transfers may help explain what the parties understood. On the other hand, a complete absence of repayments does not conclusively prove that the money was a gift. The estate needs to consider the entire history rather than rely on one convenient detail.
An Inheritance Advance Is A Third Possibility
A payment can be intended as an advance on a future inheritance without creating an ordinary repayable loan. In American inheritance law, this concept is often called an advancement. Cornell Law School explains that an advancement can reduce what an heir receives when an estate is distributed under intestacy rules. Whether a particular transfer qualifies depends on the jurisdiction and its legal requirements.
 https://kaboompics.com/, Pexels
An Advance Does Not Always Mean Repayment
Consider parents who give one child $50,000 toward a home while intending to account for that payment in their eventual estate distribution. They might expect the child to receive less from the estate rather than repay the original amount. That is fundamentally different from a debt owed to the parents. The legal distinction matters because the estate may be calculating inheritance shares instead of collecting money.
A Will Could Change The Answer
The next step is to read the parents' wills and any relevant trust documents carefully. A will may explain whether lifetime gifts should reduce a beneficiary's eventual share or whether particular obligations should be forgiven. In American law, the related concept of ademption by satisfaction can apply when a lifetime transfer was intended to fulfill a testamentary gift. Cornell notes that the rules and presumptions differ among states.
Equal Shares Do Not Erase Earlier Gifts
Suppose a will leaves the remaining estate equally to three children, but one received substantial help years earlier. It may feel natural to subtract that earlier assistance before dividing the inheritance. However, equal distribution language does not necessarily authorize the executor to revisit every gift the parents made during their lives. Whether an adjustment is permitted depends on the will, applicable inheritance law, and evidence of the parents' intentions.
The Law Changes Across State Lines
There is no single inheritance rule governing every American family. Cornell explains that states have adopted different portions of the Uniform Probate Code, while other states maintain their own succession frameworks. Consequently, a lifetime transfer might receive different treatment depending on where the estate is administered and which law governs. Families should avoid applying a rule from another state simply because it appears reasonable.
Dying Without A Will Adds Another Complication
If the parents left no valid will, the estate generally follows the jurisdiction's intestate succession laws. Those rules determine which relatives inherit and how the available property is divided. The legal treatment of an earlier payment may then depend on statutory rules concerning advancements. Cornell emphasizes that intestate inheritance rules vary among states.
The Executor Cannot Simply Pick A Side
An executor or estate administrator has responsibilities extending beyond the wishes of whichever sibling is most persuasive. The administrator must identify estate property, address relevant obligations, and complete required estate administration procedures. A disputed family transfer deserves careful investigation, particularly when it could materially affect the beneficiaries. The IRS outlines the responsibilities of estate administrators in its guidance for representatives of deceased taxpayers.
What If The Executor Received The Money?
The situation becomes especially sensitive when the person administering the estate is also the child who received the down payment. That person has a personal interest in whether the transfer is characterized as a gift or an outstanding debt. A conflict of interest may require additional safeguards, independent advice, or court involvement under applicable law. Keeping the decision-making process transparent can help protect both the estate and the executor.
Old Tax Returns May Provide Clues
Tax records can sometimes help reconstruct how a substantial family transfer was treated. The IRS explains that gifts exceeding the applicable annual exclusion may require gift tax reporting, although filing a return does not necessarily mean gift tax must be paid. If the parents filed a gift tax return reporting the transfer, that could be meaningful evidence of their understanding. It would not necessarily resolve every inheritance-law question, but it would be difficult to ignore.
Gift Tax Rules Do Not Decide Inheritance Rights
A transfer's federal tax treatment and its treatment under state inheritance law are separate questions. A payment reported as a gift for tax purposes does not automatically establish whether it should reduce an inheritance. Likewise, a family loan may raise tax issues even when its repayment terms are informal. The IRS addresses gift reporting and below-market loans separately, reflecting the different rules involved.
The Passage Of Time Can Matter
An alleged loan may be affected by a legal deadline for bringing a claim. These deadlines vary by jurisdiction and can depend on when repayment became due or when a claim accrued. An old family arrangement therefore needs more than evidence that money changed hands. The executor should have a local estate lawyer assess whether any claimed debt remains enforceable before attempting collection.
 Yuganov Konstantin, Shutterstock
A Sibling's Memory Is Not A Contract
One sibling may remember the parents saying the money would eventually be repaid, while another recalls them calling it a wedding or housewarming gift. Those recollections can be relevant, but they may not carry the same weight as contemporaneous documents. Courts may also apply special evidentiary rules to claims involving deceased individuals. The safest approach is to gather independent evidence before treating anyone's recollection as conclusive.
The Numbers Can Make The Dispute Worse
Imagine an estate worth $300,000 that is supposed to be divided equally among three children. If a previous $60,000 payment was an outright gift, each child might receive $100,000 from the remaining estate, assuming no other adjustments. If it was a valid inheritance advancement, the calculation could produce different shares. These examples illustrate why the legal classification matters, not what any particular state's law necessarily requires.
A Family Agreement Might Avoid A Court Battle
If all affected beneficiaries agree on how to resolve the disputed payment, a negotiated settlement may be possible. The parties should first understand their legal entitlements and whether anyone else, such as a creditor or additional beneficiary, could be affected. An agreement should be properly documented and reviewed under the law governing the estate. A compromise may preserve more of the inheritance than prolonged litigation.
Sometimes Independent Advice Is Worth The Cost
An estate lawyer can review the will, transfer records, mortgage documents, and applicable succession laws before the family makes an irreversible decision. An accountant may also be useful if the payment raises gift tax or loan-interest questions. The IRS recommends considering professional assistance when transfers are large or complicated. Spending money on targeted advice may be preferable to distributing the estate incorrectly and facing a dispute later.
The Estate Should Follow Evidence, Not Resentment
A sibling receiving financial help during a parent's lifetime does not automatically mean that sibling received an unfair inheritance advantage. Parents may have made different financial decisions for different children, and those choices do not necessarily create legal obligations. The executor's responsibility is to administer the estate according to the governing documents and law. Family resentment, however understandable, cannot replace proof.
So Should The Estate Call It A Gift Or A Loan?
The estate should not automatically choose either label simply because the parents failed to document the transfer. A genuine, enforceable loan may be collectible, an outright gift may require no adjustment, and a documented inheritance advance may affect distribution without requiring repayment. The strongest starting points are the mortgage file, bank records, tax documents, estate plan, and any evidence of repayment expectations. When those materials do not establish a clear answer, the appropriate next step is a jurisdiction-specific legal review rather than an arbitrary deduction from one child's inheritance.
You May Also Like: