Concerned older man looking at the camera

My wife handled all our taxes, and after she died I found out we owed the IRS thousands. Is there nothing I can do?


June 16, 2026 | Allison Robertson

My wife handled all our taxes, and after she died I found out we owed the IRS thousands. Is there nothing I can do?


She Handled the Taxes...Or So You Thought

Your wife took care of everything—filing taxes, handling paperwork, keeping things organized. Then after she passed, you discovered something shocking: you owe the IRS thousands.  Are you in trouble?
Concerned older man looking at the cameraFactinate Ltd.

Advertisement

Why This Happens More Often Than People Realize

In many households, one person manages finances. When that person is gone, the other partner is left trying to untangle years of decisions, filings, and possible mistakes—often with very little context.
Elderly man with eyeglasses focused on paperwork at home, using laptop.SHVETS production, Pexels

Advertisement

What “Owing the IRS” Actually Means

If taxes were underpaid, not filed correctly, or missed entirely, the IRS can assess penalties, interest, and back taxes. And unfortunately, those obligations don’t disappear just because one spouse has passed away.
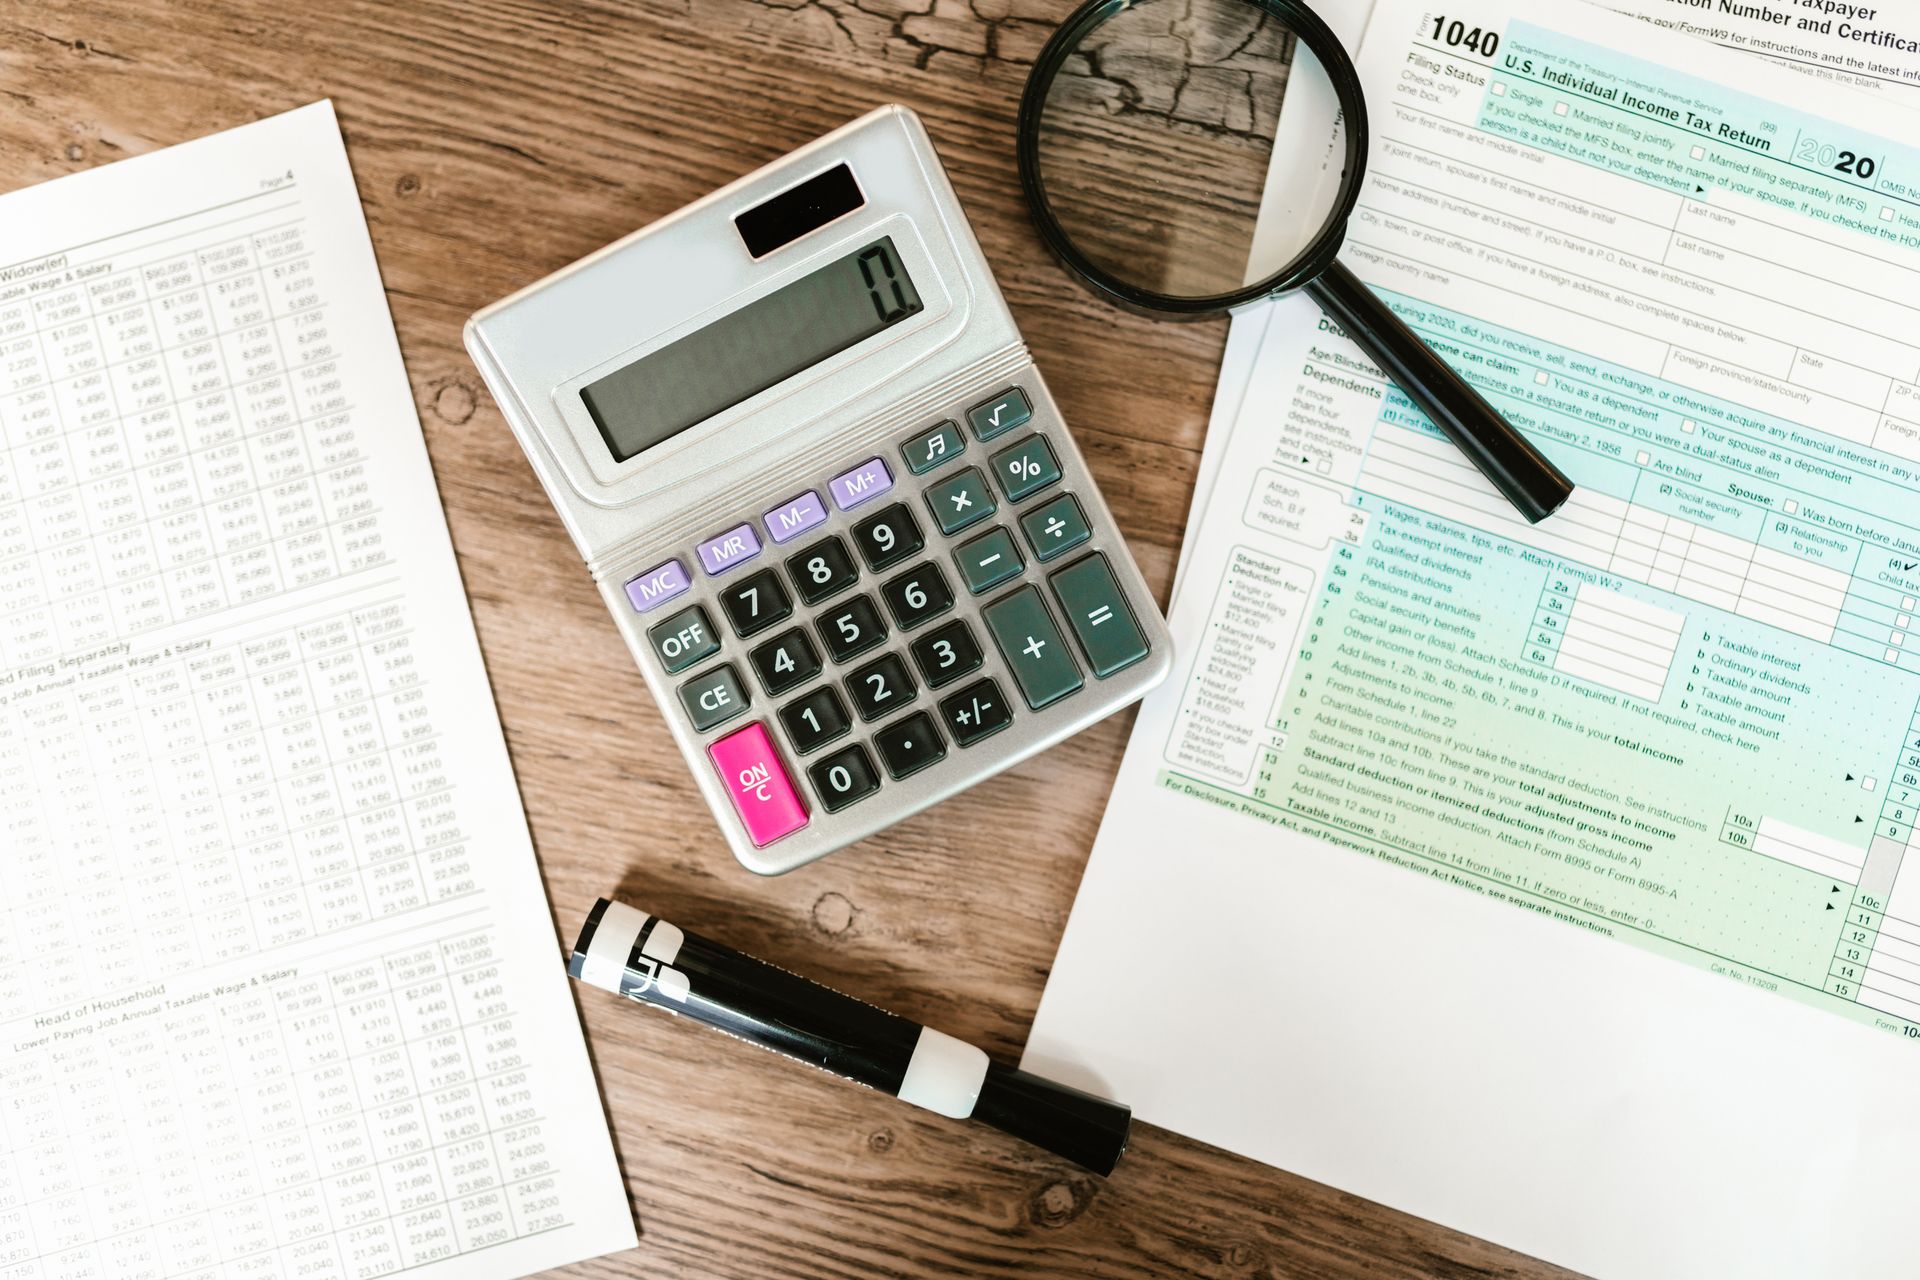
Top view of tax forms, a calculator, and a magnifying glass on a wooden surface, ideal for accounting themes.RDNE Stock project, Pexels

Advertisement

The Big Question—Are You Responsible?

If you filed jointly, the IRS generally holds both spouses responsible for the full tax liability. That means yes—legally, the debt can fall to you, even if you didn’t handle the finances.
Senior couple reviewing documents and managing finances together at home, showing collaboration and care.Kampus Production, Pexels

Advertisement

Why Joint Filing Matters So Much

A joint return isn’t just shared—it’s fully binding on both parties. The IRS treats it as a combined responsibility, which is why situations like this can feel especially unfair.
Pexels-Yankrukov-6818110Yan Krukau, Pexels

Advertisement

But Here’s Where It Gets Important

Just because you’re technically responsible doesn’t mean you’re out of options. There are protections in place for situations exactly like this.
Pexels-Vlada-Karpovich-7433862Vlada Karpovich, Pexels

Advertisement

Innocent Spouse Relief—What It Is

This is one of the biggest lifelines. Innocent Spouse Relief allows you to request relief from tax debt if you didn’t know—and had no reason to know—there were errors or underpayments.
Happy senior couple sitting at the table making plansGround Picture, Shutterstock

Advertisement

When You Might Qualify

If your spouse made mistakes, hid income, or filed inaccurately without your knowledge, you may qualify. The IRS looks at what you knew, what you should have known, and your overall situation.
T LeishT Leish, Pexels

Advertisement

There’s Also “Separation of Liability” Relief

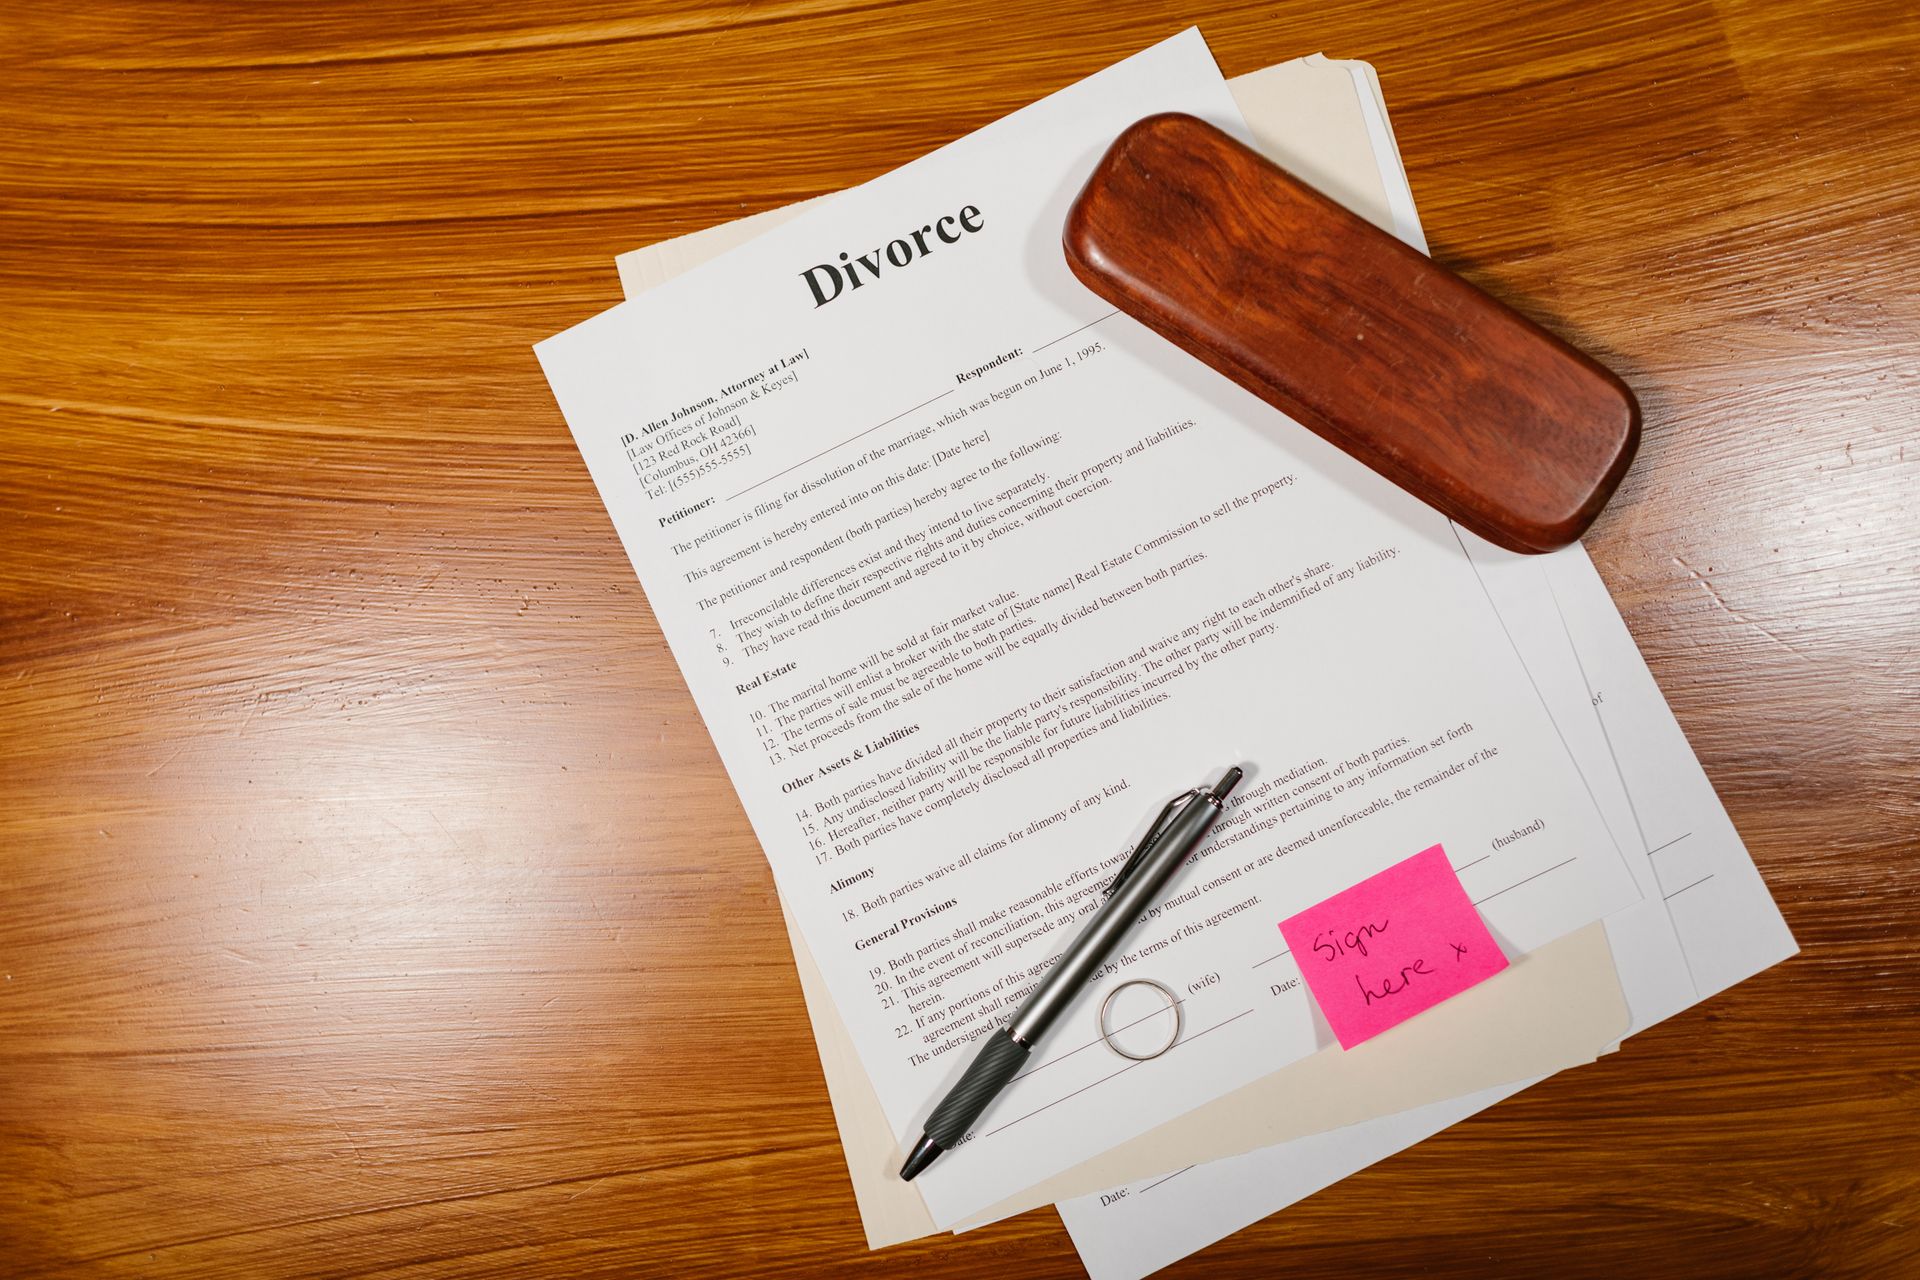
This option divides the tax debt between spouses. It’s typically used in divorce situations, but in some cases, it may apply after a spouse’s death as well.
Pexels-Rdne-7841417RDNE Stock project, Pexels

Advertisement

Another Option—Equitable Relief

If you don’t qualify for other programs, equitable relief may still be available. This considers fairness—your financial situation, involvement, and whether it would be unjust to hold you responsible.
Three adults having a business meeting indoors, discussing ideas around a laptop.Kampus Production, Pexels

Advertisement

What the IRS Will Look At

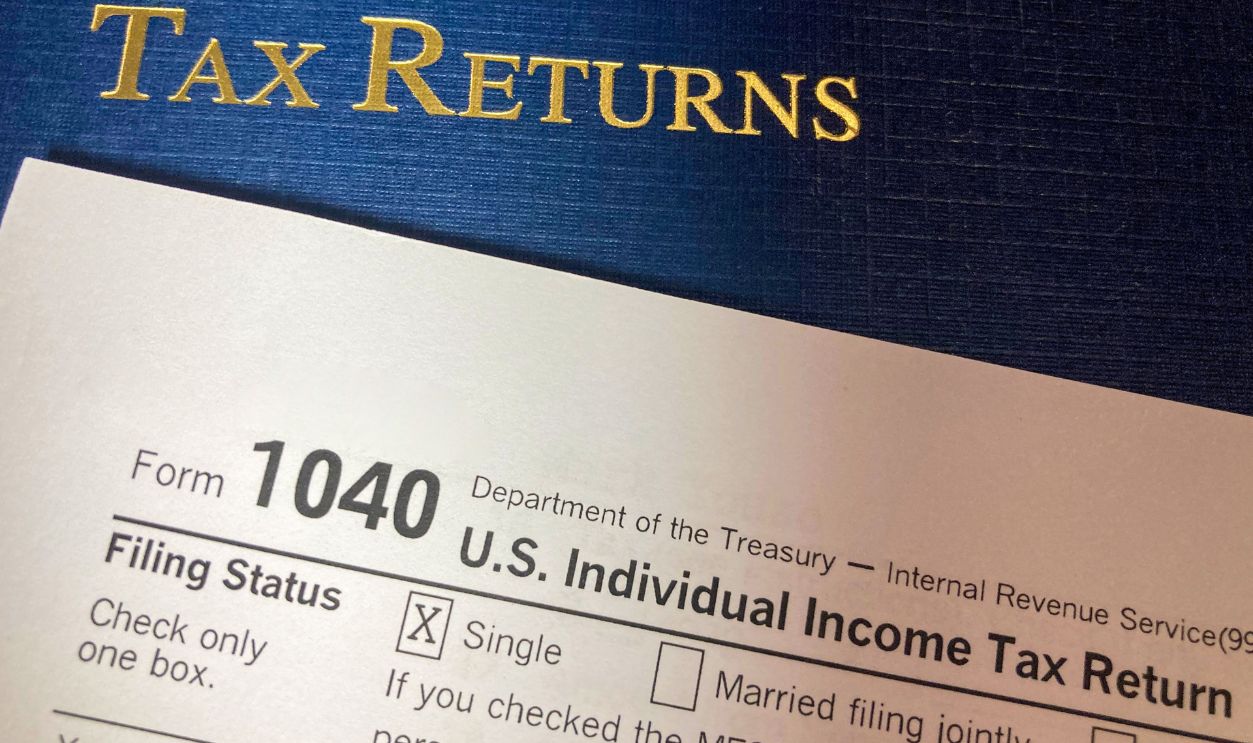
They’ll review your role in the finances, your knowledge of the situation, and whether you benefited from the unpaid taxes. It’s not automatic—but it’s not impossible either.
Gallery 1253  743 - 2026-06-12T143001.686Mark Youso, Pexels

Advertisement

What If You Truly Had No Idea?

That actually strengthens your case. If you can show you reasonably relied on your spouse and had no involvement, you may have a strong argument for relief.
Bald man with glasses sitting in office looking worried at document.www.kaboompics.com, Pexels

Advertisement

The Role of Documentation

Bank statements, tax returns, emails—anything that shows how finances were handled can help support your case. The more evidence you have, the better.
Close-up of tax forms, receipts, and coins symbolizing financial accounting and taxes.Nataliya Vaitkevich, Pexels

Advertisement

What About Penalties and Interest?

Even if you still owe some tax, penalties and interest may be reduced or removed, especially if you qualify for relief programs or demonstrate hardship.
Top view of a woman managing finances with a calculator, cash, and bills in a home setting.www.kaboompics.com, Pexels

Advertisement

Can You Set Up a Payment Plan?

Yes. If relief isn’t fully granted, the IRS offers installment agreements so you can pay over time instead of all at once.
Elderly businessman in suit reviewing documents at desk. Professional setting.Kampus Production, Pexels

Advertisement

When You Might Qualify for “Currently Not Collectible”

If paying would cause serious financial hardship, the IRS may temporarily pause collections. This doesn’t erase the debt—but it gives you breathing room.
Nicola BartsNicola Barts, Pexels

Advertisement

Should You Talk to a Professional?

In a situation like this—absolutely. A tax professional or CPA can help you navigate IRS programs and submit the right forms without making costly mistakes.
Businessman in a suit reviewing documents during a meeting indoors with a colleague.RDNE Stock project, Pexels

Advertisement

Timing Matters More Than You Think

There are deadlines for requesting relief, especially Innocent Spouse Relief (typically within 2 years of IRS collection efforts). Acting quickly can make a big difference.
Pexels-Towfiqu-Barbhuiya-3440682-11773871Towfiqu barbhuiya, Pexels

Advertisement

So… Is There Nothing You Can Do?

Actually—there’s quite a bit you can do.

While you may be legally tied to the debt through a joint return, programs like Innocent Spouse Relief exist specifically to protect people in your situation.
Business professional consults elderly clients in an office setting. Collaborative discussion, paperwork visible.Kampus Production, Pexels

Advertisement

The Real Path Forward

Start by reviewing the tax filings, gathering documentation, and exploring relief options with the IRS. You don’t have to accept the situation as-is.
Pexels-Gustavo-Fring-4173364Gustavo Fring, Pexels

One Last Thought During a Difficult Time

You’re already dealing with a lot—this shouldn’t be something you face alone. The IRS may be strict, but there are systems in place to recognize fairness when things weren’t in your control.
Pexels-Tima-Miroshnichenko-5710611Tima Miroshnichenko, Pexels

Advertisement

You May Also Like:

I earned $500 freelancing last year and didn’t report it, and now I’m panicking. Am I in trouble?
I put a $12k purchase on my credit card, and my brother says it’ll be reported to the IRS. My dad says only cash purchases are reported. Who’s right?

Sources: 1, 2, 3


READ MORE

Desk Job

The desk job isn't looking so safe anymore, and the trades are filling the gap

Something is quietly shifting in the American workforce. Professionals who spent years in offices are trading keyboards for tool belts, and the numbers behind that decision are more serious than most people realize.
March 2, 2026 Jane O'Shea
Billy The Kid Intog

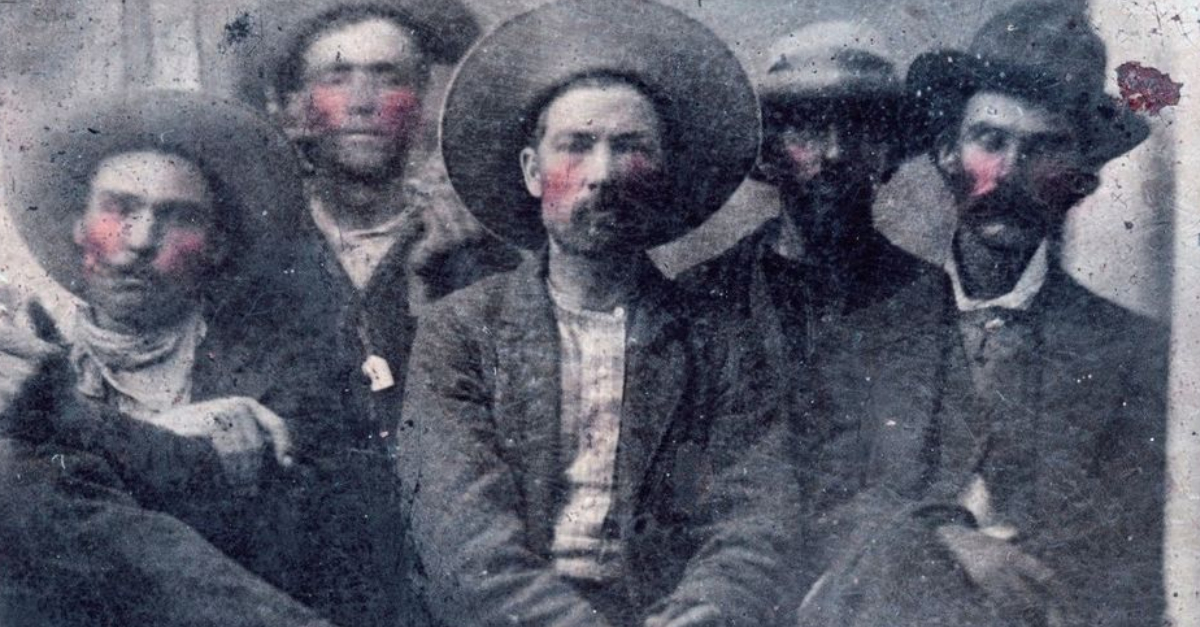
A $10 flea-market find turns out to be a photo of Billy the Kid—one worth millions because of who else is pictured: The man who shot him.

He didn’t think much of it when he bought the old photo for $10 at a flea market. But under the dust and scratches lay something remarkable—a rare glimpse of the legendary Billy the Kid. Yet what stunned historians most wasn’t the outlaw himself…it was the man sitting right next to him.
October 29, 2025 Jesse Singer
Hiddenexpensesinternal

10 Hidden Expenses That Are Draining Your Wallet Every Month

Even the most careful budgeters can end up wondering where their money went at the end of the month. Very often it's the small, recurring expenses that quietly add up over time.
May 6, 2025 Miles Brucker
Retireat40Internal

10 Money Habits Of People Who Retire Before 40

Retiring at 40 isn't a pipe dream, and you don't have to be a tech genius, Wall Street bro, or pro athlete to do it. But you have to follow the habits of those who've done it before.
April 15, 2025 Penelope Singh
 Alt

Once-Boring Postage Stamps That Are Now Jackpot To Collectors

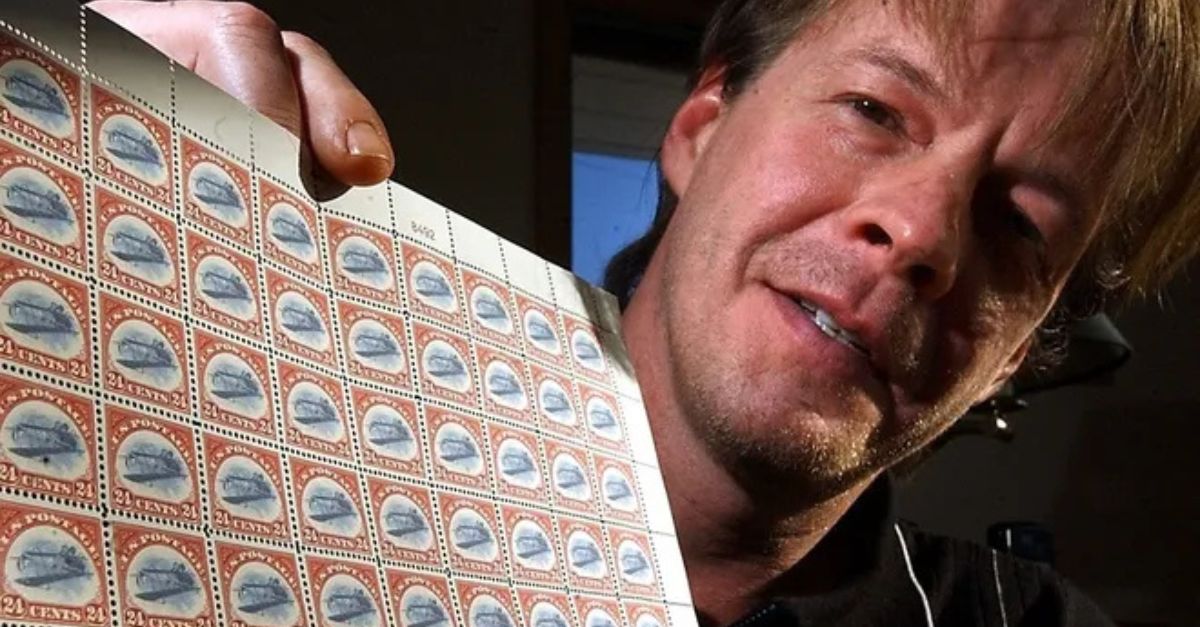
A postmark here, a printing slip there—history has a way of hiding value in plain sight. Some stamps grew from ordinary mail carriers into cultural icons, now ranking among the world’s most sought-after collectibles.
September 16, 2025 Alex Summers


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕