The Money Rules Have Changed
A lot of old money advice still gets repeated like gospel, even though the economy that created it is long gone. In the early 1980s, inflation was brutal, mortgage rates topped 18%, pensions were far more important to retirement planning, and consumer credit worked differently. Some of those old rules still hold up. Others could now leave you paying more, earning less, or making financial moves that backfire badly.
Keep Your Savings At Your Local Bank
There was once a practical reason to keep most of your cash at the bank down the street. Today, loyalty can be expensive because deposit rates vary enormously between institutions. The FDIC reported a national savings rate of just 0.39% in March 2026, making comparison shopping for insured savings accounts much more important.
A Regular Savings Account Is Good Enough
Leaving emergency savings in an ordinary account can mean accepting a very low return simply because the money feels safe. Safety still matters, but consumers can compare insured savings accounts, money-market deposit accounts, and CDs without giving up federal deposit protection when eligibility requirements are met. Your emergency fund should remain accessible, but accessibility does not require settling for almost no interest.
CDs Are All You Need For Long-Term Wealth
High interest rates made certificates of deposit extremely appealing during parts of the 1980s. CDs can still be useful for money needed on a known schedule, but they are not automatically a substitute for a diversified long-term portfolio. Investors also need to consider inflation, growth, liquidity, and the penalties that can apply when a CD is cashed before maturity.
Lock Up Your Money For The Highest Rate
A slightly higher yield can look irresistible when comparing CDs or other fixed-income products. The problem comes when chasing that rate leaves too much of your money unavailable during an emergency. The Federal Reserve found that only 63% of adults in 2025 said they could cover a $400 emergency using cash or its equivalent, which makes liquidity worth considering alongside yield.
Buy A House As Soon As You Possibly Can
Homeownership can build wealth, but buying before your finances are ready can turn the supposed investment into a cash-flow problem. Buyers have to account for the mortgage, taxes, insurance, maintenance, closing costs, and emergency reserves rather than focusing only on whether they technically qualify. With mortgage rates again above 7% in September 2026, rushing into the wrong house can be especially expensive.
Borrow As Much As The Bank Will Approve
A lender's maximum approval is not the same thing as a comfortable household budget. Mortgage underwriting looks at factors such as income, debts, assets, savings, and credit, but it cannot decide how much flexibility you personally want for retirement, travel, childcare, repairs, or job changes. Treat the approved amount as a ceiling, not a spending target.
Put 20% Down Or Do Not Buy
A 20% down payment can reduce borrowing costs, but treating it as an absolute requirement may keep some buyers waiting far longer than necessary. FHA-insured mortgages can require as little as 3.5% down, while many conventional borrowers can eventually request cancellation of private mortgage insurance after reaching specified equity thresholds. The smarter decision depends on the price, financing costs, cash reserves, and what else that down-payment money needs to accomplish.
Take The Adjustable Rate And Refinance Later
An adjustable-rate mortgage can make sense in certain situations, but refinancing later is never guaranteed. The CFPB warns that ARM payments can rise as the underlying index changes, and some loans contain floors or other provisions that make future costs less predictable. Choose an ARM because its risks fit your finances, not because you assume another loan will rescue you later.
Your House Is Your Emergency Fund
Home equity can feel like money sitting unused, but borrowing against it converts that equity into debt secured by your house. A HELOC commonly carries a variable rate, and payments can increase when the borrowing period ends or rates change. If repayment becomes impossible, the consequence can ultimately include foreclosure.
Use Home Equity To Wipe Out Other Debt
Replacing high-rate credit-card debt with a lower-rate home-equity loan can reduce interest in some cases. It can also transform unsecured debt into debt backed by your home and stretch repayment across many additional years. The CFPB specifically warns consumers to be careful about using home equity for debt consolidation because failure to repay can put the home itself at risk.
Debt Is Fine If The Interest Is Deductible
Tax deductions once made certain forms of borrowing look more attractive than they do today. Current federal law generally disallows deductions for personal interest, with specific exceptions, and home-equity interest generally qualifies only when the borrowed money is used to buy, build, or substantially improve the home securing the debt. Borrowing $1 just to obtain a partial tax deduction was never the same as saving $1, and that distinction matters even more under today's rules.
Pay Off Every Debt Before Investing
Eliminating expensive debt can deliver a powerful guaranteed benefit, particularly when credit-card interest is involved. But a blanket debt-first rule can become costly when it causes workers to ignore employer retirement benefits or postpone long-term investing for years. In 2026, workers can defer up to $24,500 into many 401(k) plans, so debt repayment and retirement contributions often need to be coordinated rather than treated as an all-or-nothing choice.
 Srdjan Randjelovic, Shutterstock
Your Company Pension Will Handle Retirement
That assumption was much easier to make when defined-benefit pensions played a larger role in private retirement plans. Department of Labor data show that defined-benefit plans had nearly 38 million participants in 1980, while the 401(k) system expanded rapidly through the rest of the decade. Today, many workers bear far more responsibility for accumulating and investing their own retirement savings.
A 401(k) Is Just A Nice Extra
When 401(k) plans were young, treating them as supplemental savings was understandable. The Department of Labor counted only about 7.5 million active participants in 401(k)-type plans in 1984, but participation expanded sharply over the following years. For millions of modern workers without traditional pensions, workplace retirement accounts can be a central part of retirement planning rather than an optional bonus.
Ten Percent Is Automatically Enough For Retirement
A single savings percentage sounds reassuringly simple, but retirement mathematics depends on when you start, how much you have already accumulated, your expected expenses, investment returns, taxes, and other income. Starting later generally requires substantially larger contributions because there is less time for compounding. A percentage can be a starting point, but it should not replace an actual retirement calculation.
Retirement Starts At 65
For decades, age 65 was deeply embedded in American retirement planning. Congress changed the Social Security full retirement age in 1983, however, gradually raising it to 67 for people born in 1960 or later. Claiming Social Security and leaving work are also separate decisions, so a modern retirement plan needs to use your actual full retirement age rather than an inherited rule of thumb.
 National Cancer Institute, Unsplash
Cash Is The Safest Retirement Investment
Cash protects principal from stock-market swings, which makes it useful for near-term spending and emergency reserves. Over a retirement that may last decades, however, holding too much in cash creates another danger because inflation steadily reduces purchasing power. Modern retirement planning generally balances liquidity and stability with investments that offer greater long-term growth potential.
A Few Blue-Chip Stocks Are Diversified Enough
Owning several famous companies may feel diversified because the businesses themselves are large. It still leaves an investor exposed to company-specific and industry-specific problems. The SEC describes genuine diversification as spreading money both across asset categories and within those categories, which can be easier to achieve through broad funds than through a handful of handpicked stocks.
Invest Heavily In The Company You Know Best
Employees often understand their own company better than businesses they only encounter through financial statements. That familiarity does not eliminate concentration risk, especially when your salary and investments already depend on the same employer. Diversification is designed to prevent a single company or industry from having an outsized effect on your financial future.
Paying High Investment Fees Is Just Part Of Investing
Investors once had far fewer low-cost choices and less ability to compare costs instantly. Today, fund expenses and advisory fees deserve close scrutiny because even apparently small annual charges compound over long periods. The SEC notes that fees directly reduce the amount of money left in your portfolio to earn returns.
Wait For The Perfect Time To Buy Stocks
Trying to jump in immediately before a rally and escape immediately before a decline sounds attractive. In practice, it requires repeatedly predicting short-term markets correctly. The SEC instead describes dollar-cost averaging as investing equal amounts at regular intervals regardless of market swings, which removes the need to make every contribution depend on a forecast.
Savings Bonds Are The Ultimate Growth Investment
U.S. savings bonds remain low-risk tools, but safety and high long-term growth are different objectives. Series EE bonds issued from May through October 2026 pay 2.40%, while Series I bonds issued during that period pay a 4.26% composite rate that can change with inflation. They can have a place in a financial plan, but automatically using them for every decades-long goal can mean ignoring other risk-and-return choices.
 https://kaboompics.com/, Pexels
Whole Life Insurance Is Automatically A Great Investment
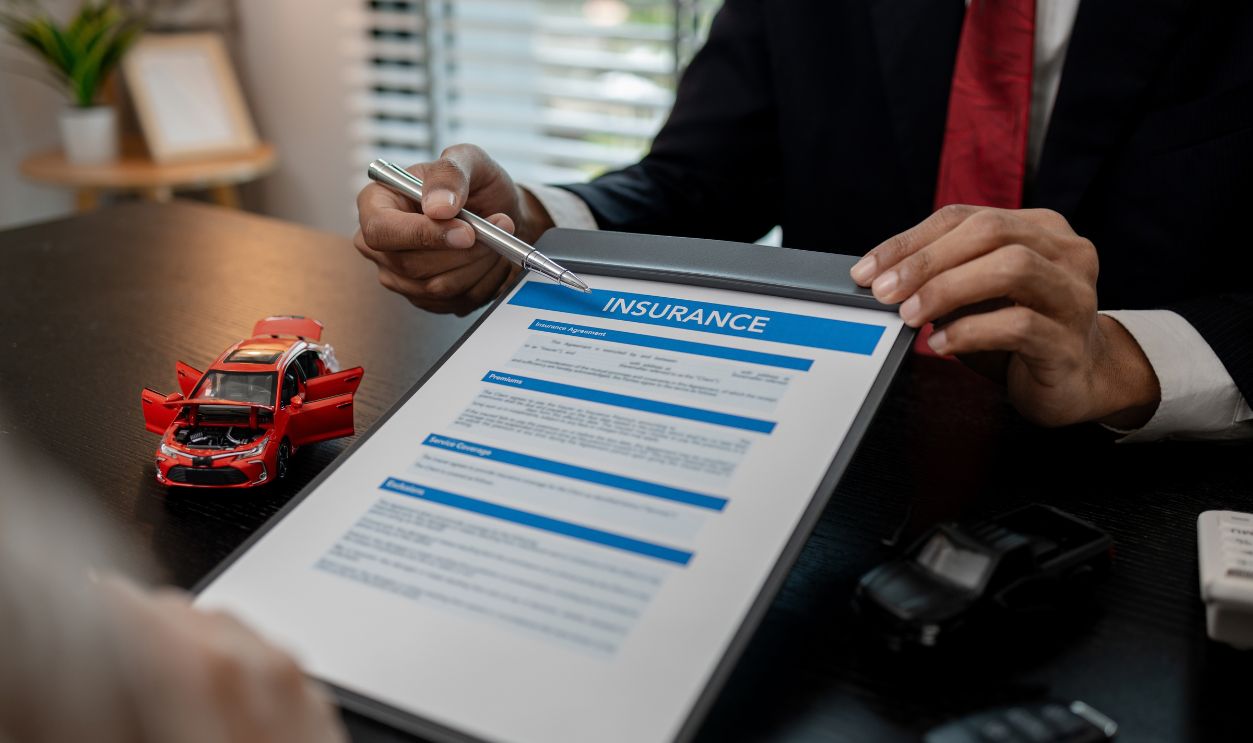
Permanent life insurance can provide lifetime coverage and accumulate cash value, so it is not inherently a bad product. It can also be considerably more complicated than treating insurance protection and investing as separate decisions, with premiums supporting insurance costs, fees, and cash value. Before buying it primarily as an investment, understand the policy's guarantees, costs, surrender values, and what beneficiaries actually receive.
Paying Cash Means Credit Scores Do Not Matter
Avoiding unnecessary debt is still excellent advice, but completely ignoring credit can have consequences beyond borrowing. Credit scores and reports may influence mortgage and auto-loan pricing, credit limits, rental decisions, and in some places insurance-related decisions. A strong credit history can reduce future borrowing costs even for someone who rarely carries debt.
 https://kaboompics.com/, Pexels
Close Credit Cards You Are Not Using
Tidying up old accounts sounds financially responsible, but closing a card does not automatically improve your credit. The CFPB notes that closing an account can reduce your available credit and increase your credit-utilization ratio, potentially lowering your score. Keeping a no-fee account open can sometimes make sense, provided you monitor it for unauthorized charges and do not use it as an excuse to overspend.
 https://kaboompics.com/, Pexels
Carry A Balance To Build Credit
This myth has cost borrowers real money. You do not need to pay credit-card interest to create a positive payment history, and the CFPB says paying cards in full each month is the better approach for building or maintaining a strong score. With the average interest rate on commercial-bank card accounts actually being charged interest at 22.15% in May 2026, carrying unnecessary balances can be extremely expensive.
Let The Car Dealer Handle The Financing
Convenience can make dealership financing tempting, but the easiest offer is not necessarily the cheapest. The CFPB recommends getting prequalified or preapproved with other lenders and comparing APRs before signing, noting that dealers may profit when they arrange financing at a higher rate than the lender provides to them. Walking into the dealership with competing offers gives you something far more valuable than convenience: leverage.
College Will Work Itself Out Later
College planning is much harder to improvise once the bills arrive. For 2025-26, average published tuition and fees reached $11,950 for in-state students at public four-year institutions and $45,000 at private nonprofit four-year schools, before housing and many other expenses. Grants and aid can reduce what families actually pay, but the scale of modern costs makes early planning, saving, aid research, and careful school comparison much more important.
Keep The Principle, Update The Playbook
The best 1980s financial advice was usually built around sensible principles such as saving, avoiding waste, preparing for retirement, and protecting your family. What changed were the products, tax rules, interest rates, retirement systems, credit scoring, and costs surrounding those principles. Keep the discipline, but run today's numbers before following yesterday's rules.
You May Also Like:
Companies That Were Worth Billions In The 1990s—Then Everything Fell Apart
1970s Shopping Habits That Would Feel Totally Foreign Today—Which Would You Actually Bring Back?
Financial Advice That Sounds Safe—Until You Run The Numbers In Today’s Economy