close-up-photo-of-a-stressed-man

Financial Decisions That Become Surprisingly Expensive After Age 60


August 31, 2026 | J. Clarke

Financial Decisions That Become Surprisingly Expensive After Age 60


Think Twice

Retirement can make ordinary money choices much less ordinary. Once Social Security, Medicare, required withdrawals, and tax rules overlap, a harmless-looking decision can trigger permanent benefit reductions, higher premiums, extra taxes, or years of added costs. These moves deserve a second look after 60.
close-up-photo-of-a-stressed-manNicola Barts, Pexels.com

Advertisement

Claiming Social Security As Soon As You Can

Social Security retirement benefits can begin at 62, but claiming before full retirement age permanently reduces the monthly amount. For people born in 1960 or later, full retirement age is 67, and claiming at 62 can reduce the benefit by as much as 30%.
Social Security BenefitsMonkey Business Images, Shutterstock

Advertisement

Waiting Past 70 To Claim Social Security

Delayed retirement credits increase Social Security benefits only until age 70. Postponing a claim beyond that age does not produce a larger monthly retirement benefit, so waiting longer can simply mean passing up payments you were already eligible to receive.
Elderly woman signing paperwork in modern office with consultant.Kampus Production, Pexels

Advertisement

Claiming Benefits While You Are Still Working

If you claim Social Security before full retirement age and keep earning wages, part of your benefits can be withheld. In 2026, people under full retirement age all year lose $1 in benefits for every $2 earned above $24,480.
Business professionals engaged in a meeting, analyzing documents and charts in a modern office.Vlada Karpovich, Pexels

Advertisement

Stopping Work With Fewer Than 35 Earnings Years

Social Security uses your highest 35 years of earnings to calculate retirement benefits. If you stop with fewer than 35 years, zeros enter the calculation, while low-earning years can also reduce the average used to determine your benefit.
Diverse team engaged in a productive office meeting, reviewing documents and collaborating.Pavel Danilyuk, Pexels

Advertisement

Putting Off Medicare Part B Without The Right Coverage

Delaying Part B can be costly if you do not qualify for a Special Enrollment Period. The penalty generally adds 10% to the Part B premium for every full 12-month period you could have enrolled but did not, usually for as long as you have Part B.
Senior woman wearing glasses, reading documents at a desk indoors, showcasing professional focus.cottonbro studio, Pexels

Advertisement

Assuming COBRA Lets You Delay Medicare

COBRA does not extend Medicare’s Part B Special Enrollment Period. Medicare says the eight-month window starts when employment or job-based coverage ends, even if you elect COBRA and keep that coverage afterward.
Elderly businessman focused on reviewing documents at his office desk.Kampus Production, Pexels

Advertisement

Going Too Long Without Coverage

If you go 63 days or more without Part D or other creditable drug coverage after becoming eligible, a penalty can apply. It generally equals 1% of the national base beneficiary premium for each full uncovered month and can continue as long as you have Part D.
Shutterstock-2298734047, Financial advisor talking to a senior man with an investment, savings or retirement planning. Discussion, documents and professional accountant helping an elderly male person with finance paperwork.PeopleImages, Shutterstock

Advertisement

Missing Your Medigap Open Enrollment Window

Federal Medigap open enrollment lasts six months beginning when you are 65 or older and enrolled in Part B. During that window insurers cannot deny you because of health problems; afterward, coverage may cost more, offer fewer choices, or be unavailable.
Senior business professionals signing documents during a meeting in a bright office.Kampus Production, Pexels

Advertisement

Dropping Part B Just To Save The Premium

Canceling Part B can create more than a temporary gap. If you later want it back without a Special Enrollment Period, you may have to wait for the General Enrollment Period and could face a lasting late-enrollment penalty.
Thoughtful senior man sitting indoors, contemplating life.Vitaly Gariev, Pexels

Advertisement

Continuing HSA Contributions After Medicare Starts

Once you are enrolled in Medicare, your HSA contribution limit becomes zero. This can surprise late enrollees because premium-free Part A may be retroactive for up to six months, potentially making recent HSA contributions excess contributions.
Senior professionals collaborating on a project using a digital tablet in a modern office setting.Antoni Shkraba, Pexels

Advertisement

Doing A Huge Roth Conversion In One Year

The taxable portion of a Roth conversion is included in gross income for that year. Because Medicare generally uses tax-return income from two years earlier for IRMAA, a large conversion can later increase Part B and Part D premiums.
Shutterstock-2580045637, Happy senior old family couple clients make financial insurance estate business deal contract signing, agent lawyer, satisfied mature customers signing contract meeting bank manager agree on investmentpics five, Shutterstock

Advertisement

Taking A Large IRA Withdrawal After Social Security Starts

Traditional IRA distributions are generally taxable income, and extra income can also change how much Social Security is taxable. Depending on total income, up to 85% of Social Security benefits can be included in taxable income.
Senior man wearing yellow shirt writing notes at desk with lamp, calculator, and glass sphere nearby.RDNE Stock project, Pexels

Advertisement

Delaying Your First RMD Until The Following Spring

Your first required minimum distribution can generally be delayed until April 1 of the year after you reach the applicable RMD age. But the next RMD is still due by December 31, potentially placing two taxable distributions in one calendar year.
a man holding a pen and looking at a laptopVolodymyr Hryshchenko, Unsplash

Advertisement

Missing A Required Minimum Distribution

A missed or insufficient RMD can trigger a 25% excise tax on the shortfall. The IRS says that rate can fall to 10% when the mistake is corrected within the required time.
Portrait of a senior businesswoman in a blazer reading documents indoors.https://kaboompics.com/, Pexels

Advertisement

Taking A Retirement Lump Sum Without A Direct Rollover

If an eligible employer-plan distribution is paid to you instead of transferred through a direct rollover, 20% federal withholding generally applies. Any taxable amount not rolled over within 60 days is included in income for that year.
Elderly man using a laptop at home, focused on modern technology in a bright room.SHVETS production, Pexels

Advertisement

Draining An IRA To Pay Off The Mortgage

Using one large traditional IRA withdrawal to erase a mortgage can create a taxable-income spike. For Medicare beneficiaries, that same spike can also contribute to higher income-related Part B and Part D premiums two years later.
Shutterstock-663753898, Senior Couple Insurance Application FormRawpixel.com, Shutterstock

Advertisement

Selling A Large Block Of Appreciated Investments At Once

Selling appreciated investments can create taxable capital gains. For a Medicare beneficiary, concentrating a large gain in one year can also raise modified adjusted gross income enough to trigger or increase IRMAA later.
Professional business meeting with two colleagues reviewing documents at an office desk.Los Muertos Crew, Pexels

Advertisement

Giving To Charity Without Checking QCD Rules

At age 70½ or older, a qualified charitable distribution can send money directly from an eligible IRA to a qualified charity. A properly structured QCD can be excluded from income, making it worth comparing with withdrawing IRA money and donating cash yourself.
Senior businessman in suit counting money at office desk with a laptop. Elegance and financial focus in modern workspace.Gustavo Fring, Pexels

Advertisement

Giving Away Assets To Qualify For Medicaid

Gifting assets shortly before seeking Medicaid long-term-care coverage can backfire. Transfers for less than fair market value during the five years before an application can cause long-term-services-and-supports coverage to be denied for a penalty period.
Shutterstock-2520695661, Conversation, documents and senior couple with financial advisor for retirement annuity saving account. Meeting, finance paperwork and elderly man and woman with investment banker for pension growth.PeopleImages, Shutterstock

Assuming Medicare Pays For Long-Term Custodial Care

Medicare generally does not pay for long-term custodial care at home, in the community, or in a nursing home. Medicare says beneficiaries pay all costs for non-covered services, including most long-term care.
Adult man monitoring elderly woman's blood pressure at kitchen table using sphygmomanometer.Gustavo Fring, Pexels

Advertisement

Taking A Reverse Mortgage Without Pricing The Fees

Home Equity Conversion Mortgages are available to eligible homeowners 62 and older, but they carry real costs. The CFPB says they can include origination charges, closing costs, mortgage insurance, interest, servicing fees, and other ongoing expenses.
Shutterstock-2628404001, Young confident financial agent talking with senior couple about health insurance in retirement sitting on sofa at home. Elderly man and woman meeting with advisor going to sign investment contract.Studio Romantic, Shutterstock

Advertisement

Automatically Renewing The Same Medicare Plan

Medicare Advantage and Part D plans can change costs and coverage each year. Annual notices can show changes to premiums, cost sharing, formularies, provider networks, and service areas, so renewing automatically can leave you paying more than expected.
Close-Up Shot of an Elderly Woman with Eyeglasses Having a Phone CallAnna Shvets, Pexels

Advertisement

Ignoring An IRMAA Notice After Retiring

IRMAA is usually based on older tax information, which can be painful right after retirement. Social Security lets people whose income fell after certain life-changing events, including work stoppage or reduction, request a lower income-related Medicare adjustment.
An elderly woman and a man in a professional meeting discussing documents indoorsRDNE Stock project, Pexels

Advertisement

You May Also Like:

My wife wants to stop contributing to retirement so we can send our kids to private school. Which future should come first?

My adult daughter uses buy-now-pay-later for groceries, and I’m worried she is normalizing debt for basics. How do I explain this to her?

Sources: 1, 2


READ MORE

Saving money

Are Canadians Saving More Than Americans? Latest Studies Reveal A Surprising Gap

Curious how your savings stack up? This article compares average savings in the U.S. and Canada, revealing surprising gaps, reasons behind them, and shocking stats about American savings.
January 28, 2026 Allison Robertson
concerned woman holding phone

I just found out about the $600 rule and I’ve been using Venmo and PayPal all year—am I about to owe a huge tax bill?

A growing number of people are suddenly hearing about a $600 rule connected to Venmo and other cash apps, usually in the form of warnings, screenshots, or half-explained posts. There’s rarely context—just the implication that a normal year of payments may have crossed an invisible line with real consequences.
January 28, 2026 Jesse Singer
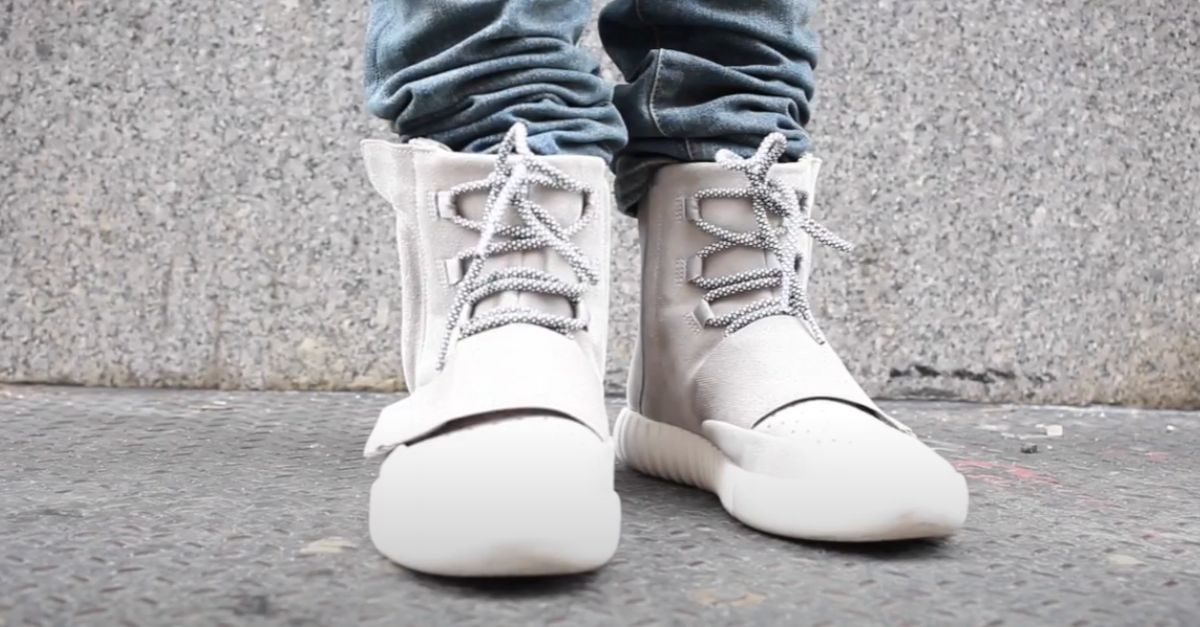
Adidas X Kanye West Yeezy 750 Boost Light Grey

Who Knew Sneakers Could Cost As Much As Your Mortgage? Here Are The World's Most Expensive Kicks.

Do your sneakers cost more than your dinner payment? That's cute. Some of these kicks could pay your whole house’s mortgage.
January 27, 2025 Miles Brucker
Inheritance

My grandpa just died and my cousins all got a big inheritance, but my mom is keeping my portion. I’m 40 years old. Can she do that?

Your cousins got their inheritance, but your mom is keeping yours—at age 40. Learn what rights you have and how to challenge unfair inheritance issues when a parent blocks your share.
January 20, 2026 Allison Robertson
Ceaseanddesistinternal

I anonymously posted a bad online review. The company posted my name and address and sent a cease-and-desist letter. What can I do?

When you posted a negative online review of a company's service, they published your contact information online and sent a cease-and-desist letter. We look at how you can protect yourself.
January 13, 2026 Jane O'Shea
Insurance Int

Here’s How To Figure Out If You’re Paying Too Much For Car Insurance

Car insurance has a funny way of becoming invisible. You sign up, set the payment to auto-draft, and then forget about it—until your bank account reminds you every month. The problem is that many drivers end up overpaying not because they’re reckless or unlucky, but because their policy hasn’t kept up with their life. If you’ve ever wondered whether your premium feels a little too spicy for what you’re getting, these signs will help you figure it out.
January 9, 2026 J. Clarke


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team