Worried woman

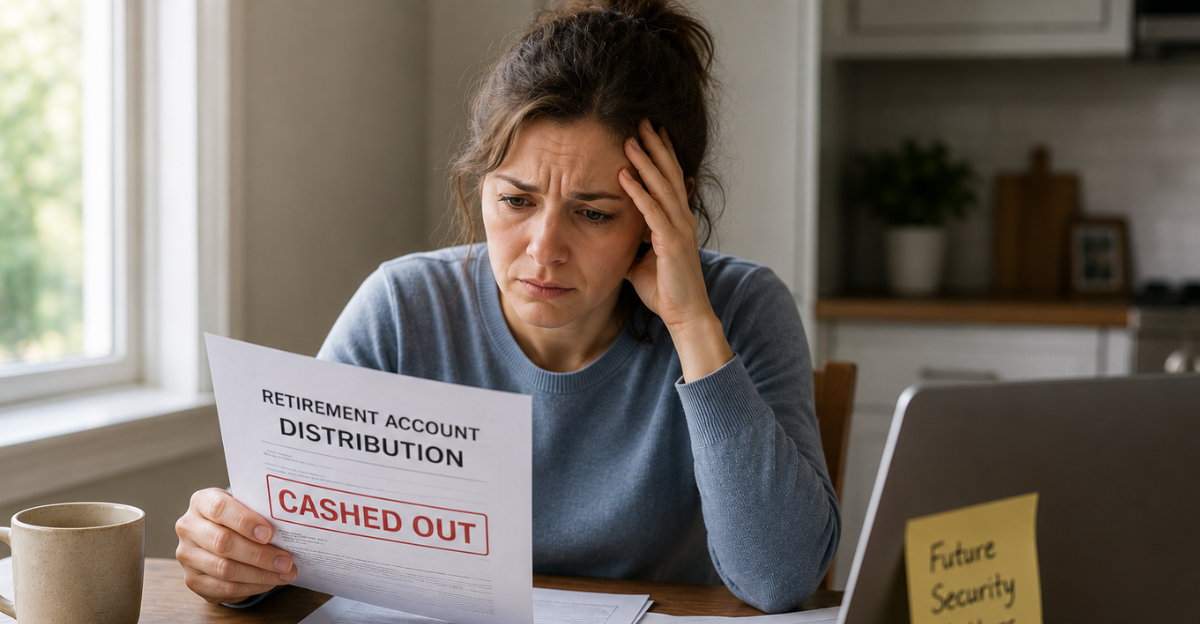
I cashed out retirement savings to help my family, and now I’m worried I’ll never recover financially. How can I fix this?


July 8, 2026 | J. Clarke

I cashed out retirement savings to help my family, and now I’m worried I’ll never recover financially. How can I fix this?


Helping Family Can Come With A Real Cost

Helping your family when they’re in trouble can feel like the only choice at the moment. Maybe someone had medical bills, lost a job, needed housing, or just had nowhere else to turn. But if the emergency makes you turn to your retirement savings, it’s completely normal to look at your retirement account and think, “What did I just do to my future?” once the crisis passes. 
Worried woman Factinate LTD

Advertisement

First, Get The Full Picture

Before you panic, figure out exactly where things stand. How much did you withdraw? How much did you lose to taxes or penalties? How much do you still have saved? The goal here isn’t to make yourself feel worse. It’s to stop guessing and start planning.
A couple working remotely at home with documents and a dog on the sofa.Nataliya Vaitkevich, Pexels

Advertisement

Early Withdrawals Can Sting

Taking money out of retirement early can be expensive. In many cases, withdrawals from traditional retirement accounts before age 59 can trigger income taxes and a 10% early withdrawal penalty unless you qualify for an exception. That means the amount you took out may have cost more than you first realized.
"Small" Withdrawals Don't Get A PassAnnaStills, Shutterstock

Advertisement

Don’t Turn This Into A Shame Spiral

Yes, this is a setback. No, it does not mean you ruined your life. People dip into retirement savings for all kinds of serious reasons, including illness, caregiving, job loss, and family emergencies. Be honest about the damage, but don’t waste all your energy beating yourself up.
woman leaning on white wooden table while holding black Android smartphoneKev Costello, Unsplash

Advertisement

Figure Out Your New Starting Point

Take stock of your current retirement balance, income, debt, monthly bills, and how many working years you likely have left. This may not be the number you hoped to see, but it’s the number you can work with. A real plan starts with real numbers.
woman in gray shirt sitting on chairAleksandra Sapozhnikova, Unsplash

Advertisement

Start Contributing Again As Soon As You Can

Once the immediate crisis is over, the most important thing is getting money flowing back into retirement. Even if you can only restart with a small contribution, do it. The habit matters, and you can increase the amount later as your budget gets stronger.
Young woman diligently working on accounting with a calculator and documents. Perfect for business and finance themes.Mikhail Nilov, Pexels

Advertisement

Don’t Leave Employer Match Money On The Table

If your job offers a 401(k) match, try hard to contribute enough to get the full match. That match is part of your compensation, not a bonus you should casually skip. When you’re rebuilding, every extra dollar matters.
a man sitting at a desk with a laptop and papersVitaly Gariev, Unsplash

Advertisement

Give Compound Growth A Chance To Help

The sooner you start rebuilding, the more time your money has to grow. You may not be able to undo the withdrawal overnight, but steady contributions can add up over time. If retirement is still years away, time is still one of your biggest advantages.
Holding Too Much Idle Cash In Low-Yield AccountsRDNE Stock project, Pexels

Advertisement

Don’t Try To Make It All Back With A Big Gamble

It can be tempting to chase risky investments when you feel behind. But putting a large chunk of money into speculative stocks, crypto, or “hot tips” can dig the hole even deeper. Rebuilding should be steady, not desperate.
person using black and gray laptop computerKanchanara, Unsplash

Advertisement

Build A Small Emergency Fund

One reason people end up raiding retirement accounts is because there’s no cash cushion. You don’t need a perfect emergency fund right away, but even a small one can protect you from using retirement savings again. Start with whatever amount feels realistic.
Woman in Black Long Sleeves Shirt Doing AccountingNataliya Vaitkevich, Pexels

Advertisement

Look For Easy Cuts In Your Budget

You don’t have to cancel your whole life to recover financially. Start by looking at subscriptions, insurance rates, takeout, unused memberships, and recurring charges. Small cuts can free up money that goes straight back into savings.
You Can Ask For A Full Accounting (And You Should)Jack Sparrow, Pexels

Advertisement

Think About Working A Little Longer

This may not be what you want to hear, but working an extra year or two can make a big difference. It gives you more time to save, more time for investments to recover, and fewer retirement years to fund. Even a small delay can help repair the damage.
people doing office worksAlex Kotliarskyi, Unsplash

Advertisement

Look For Ways To Bring In Extra Income

If your budget is tight, increasing income may help more than cutting every little expense. A raise, extra shifts, freelance work, seasonal work, or a part-time job can all help. The key is to send that extra money toward retirement instead of letting it disappear into everyday spending.
a man riding a bike down a streetPim de Boer, Unsplash

Advertisement

Use Catch-Up Contributions If You Qualify

If you’re 50 or older, you may be allowed to contribute extra money to certain retirement accounts through catch-up contributions. These rules are designed to help people save more later in their careers. If you’re eligible, this can be a useful rebuilding tool.
Worried woman Factinate LTD

Advertisement

Watch Out For Tax Surprises

A retirement withdrawal can increase your taxable income for the year. That may affect your refund, your tax bill, or even certain income-based benefits. If the withdrawal was large, it’s worth getting tax help before another surprise shows up.
A woman looking over receiptsKarolina Grabowska, Pexels

Advertisement

Make Sure Your Investments Still Fit

After a big withdrawal, your old retirement plan may not fit anymore. Check whether your investments still make sense for your age, goals, and risk tolerance. You don’t want to be so conservative that your money barely grows, but you also don’t want to take risks you can’t handle.
Shutterstock-2646324851, Young couple sitting at home reviewing documents and laptop together, focused on managing household expenses, bills, or investments. Serious expressions reflect financial planning, budgeting, and lifesimona pilolla 2, Shutterstock

Advertisement

Have A Clear Conversation With Family

If you cashed out savings to help relatives, it may be time for a difficult but necessary conversation. You can love your family and still set boundaries. They need to understand that your retirement money cannot become the family emergency fund every time something goes wrong.
Restaurant InvestmentFactinate

Advertisement

Update Your Retirement Timeline

You may need to adjust when or how you retire, and that’s okay. Maybe you work a little longer, save more aggressively, downsize later, or change your retirement lifestyle expectations. A revised plan is much better than pretending nothing changed.
Shutterstock-2368562285, Stress, old couple with documents and taxes in home, mortgage payment and retirement funding crisis. Financial budget, senior man and woman on sofa with anxiety for bills, life insurance and debt.PeopleImages, Shutterstock

Advertisement

Get Professional Help If You’re Overwhelmed

A financial planner or tax professional can help you see your options more clearly. They can estimate how much the withdrawal set you back, how much you need to save now, and what changes would make the biggest difference. You don’t have to solve the whole thing alone.
Three colleagues engaged in a business meeting discussing documents at a table indoorsMikhail Nilov, Pexels

Advertisement

Focus On What You Can Do Next

You may not be able to perfectly replace every dollar you withdrew. But you can restart contributions, lower unnecessary expenses, avoid another early withdrawal, and give your investments time to recover. The goal is progress, not punishment.
Two colleagues discussing important business documents at an office desk.Mikhail Nilov, Pexels

This Setback Doesn’t Have To Define Your Future

Cashing out retirement savings can feel scary, especially when you did it to help someone else. But one financial setback does not automatically mean you’ll never recover. Start with the numbers, rebuild your savings habit, protect yourself from future emergencies, and keep moving forward one step at a time.
man woman credit - accountsMikhail Nilov, Pexels

Advertisement

You May Also Like:

My parents want to transfer assets right before they retire. Is it a good idea to move so much money around right before retiring?

I won $8,500 gambling on sports this year. My uncle told me that if it’s under $10,000 I don't have to declare it on my taxes. Is that true?

Sources:  1, 2


READ MORE

Rss Thumb - Second Home In Retirement

We have $2M saved for retirement but want to buy a second home. Is that financially wise?

You have $2 million saved for retirement, but is buying a second home a smart move? Discover the hidden costs, risks, and ways to protect your nest egg.
October 15, 2026 Jack Hawkins
Rss Thumb - 1990S Stores Family Budgets

Stores From The 1990s That Families Budgeted Around Before Online Shopping Took Over

Before Amazon changed shopping forever, American families planned their budgets around these beloved 1990s stores. How many do you remember?
October 15, 2026 Jack Hawkins
AI-generated image of two frustrated men arguing

My brother says executor fees are greedy, but the estate work is taking months. When is payment reasonable?

My brother calls executor fees greedy, but managing an estate takes months. Learn when executors deserve compensation, how fees are calculated, and what beneficiaries can legally challenge during probate proceedings.
October 15, 2026 Sasha Wren
Rss Thumb - Tiktok Follow Boss

I work at a social media marketing company. My boss demanded that we all follow his TikTok or get fired. Can I be terminated over that?

Your boss demands you follow his TikTok or lose your job. Can he legally fire you for refusing? Here's what U.S. employment laws say about your rights.
October 15, 2026 Jack Hawkins
Internalfb Image (3)

My brother used our late mother's reward points before probate without telling me. Are loyalty points part of an inheritance?

Reward points can feel like free money, especially when a loved one dies and a stash of miles is sitting there unused. That is why fights can start fast if one family member logs in and cashes them out before probate even gets moving. The key question is simple but not always intuitive: are loyalty points actually part of an inheritance?
October 15, 2026 Miles Brucker
woman in 1960s store with candy bars

Candy Bars From The 1960s And 70s Baby Boomers Loved—But Millennials Have Never Heard Of (Or Even Tasted)

The candy aisle of the 60s and 70s had plenty of favorites that you won’t find at the checkout today. These bars disappeared, leaving behind old wrappers and some very loyal fans. How many did you try—and which one are you still waiting for someone to bring back?
October 15, 2026 Jesse Singer


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕