concerned woman holding phone

I just found out about the $600 rule and I’ve been using Venmo and PayPal all year—am I about to owe a huge tax bill?


January 28, 2026 | Jesse Singer

I just found out about the $600 rule and I’ve been using Venmo and PayPal all year—am I about to owe a huge tax bill?


A “$600 Rule” Is Being Mentioned Everywhere—and It Sounds Bad

A growing number of people are suddenly hearing about a $600 rule connected to Venmo and other cash apps, usually in the form of warnings, screenshots, or half-explained posts. There’s rarely context—just the implication that a normal year of payments may have crossed an invisible line with real consequences.
concerned woman holding phoneFactinate

Advertisement

Why Does This Sound Like Something You’re Supposed to Already Know?

The scariest part is how casually people talk about this rule—like everyone else got the memo except you. No warning, no letter, no clear explanation. Just a number, a payment app, and the suggestion that the IRS might now be involved.
Credit Card Misusednampix, Shutterstock, Modified

Advertisement

First, Take a Breath—This Isn’t a New Tax

Before assuming the worst, it helps to know this didn’t suddenly create a brand-new tax. What changed wasn’t whether money can be taxed—it was how certain payments are reported. That difference is subtle, but it matters more than most headlines admit.
image of a couple calculating taxesChay_Tee, Shutterstock

Advertisement

What the $600 Rule Actually Is

The $600 rule refers to Form 1099-K, which payment platforms may issue if you receive more than $600 in certain types of payments in a year. That form is sent to you and the IRS as a record—it’s not a bill, a fine, or an accusation.
Why Current Tax Calculations VaryMikhail Nilov, Pexels

Advertisement

Why the Rule Feels So Sudden

For years, platforms only issued a 1099-K if you had over $20,000 and 200 transactions. Dropping that threshold to $600 made it feel like a massive shift, even though the underlying tax rules didn’t change at all for individuals.
Man checking financial documents or insurance bills on laptop at homWESTOCK, Adobe Stock

Advertisement

This Rule Is About Income—Not Personal Transfers

Here’s the part most panic posts leave out. The rule focuses on payments tied to work, selling, or services—not everyday money between friends. Splitting rent, reimbursing someone for dinner, or sending a gift generally isn’t what this rule is targeting.
HR NightmaresShutterstock

Advertisement

Getting a 1099-K Doesn’t Mean You Owe Taxes

This is where most panic spirals begin. A 1099-K is simply an information form. It tells the IRS money moved—it doesn’t determine whether that money was taxable after expenses, losses, or exclusions.
Woman working in officeRDNE Stock project, Pexels

Advertisement

Yes, Personal Payments Can Show Up by Mistake

Payment apps don’t always label transactions perfectly. That means personal transfers sometimes appear on a 1099-K. That doesn’t automatically make them taxable—it just means you may need to categorize them correctly when filing your return.
Female person or freelancer with paperwork on computer in financial planRene L, Adobe Stock

Advertisement

The Real Risk Is Ignoring the Form

If the IRS receives a 1099-K and you pretend it doesn’t exist, that’s when problems can arise. Addressing it—by reporting income properly and backing out non-taxable amounts—is usually enough to keep things routine and uneventful.
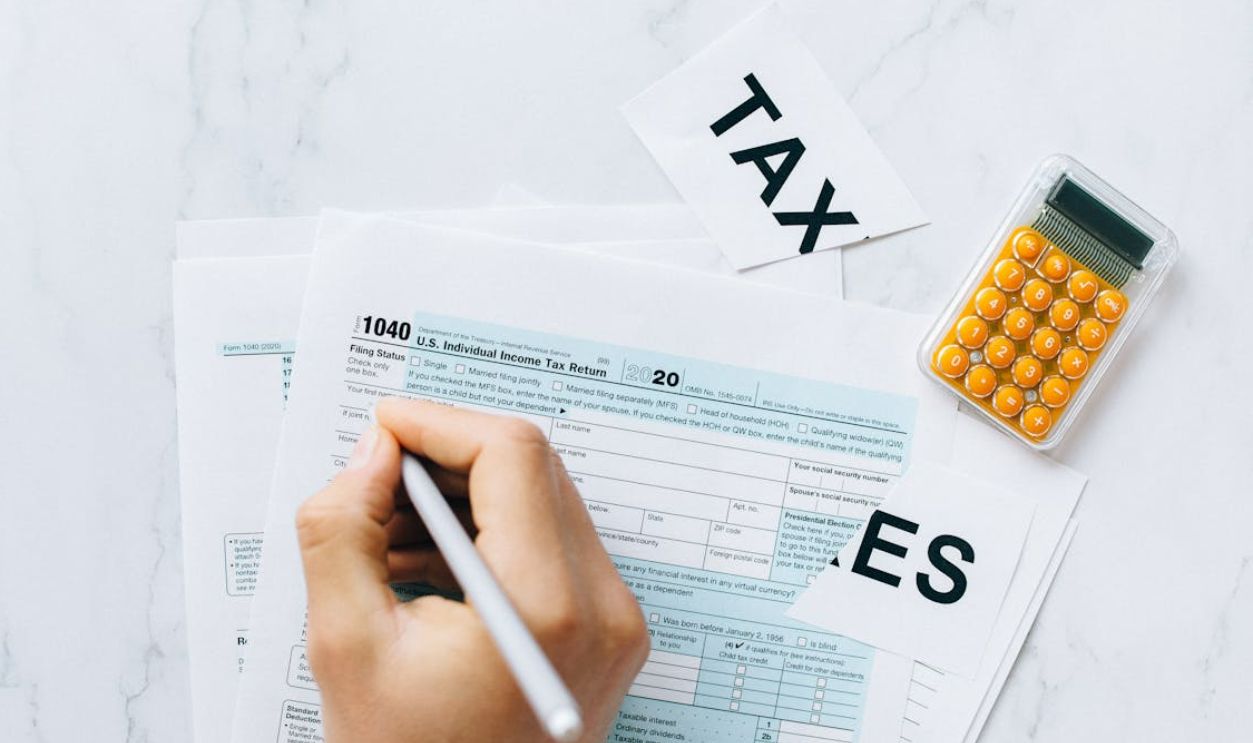
Signing tax documentsNataliya Vaitkevich, Pexels

Advertisement

Selling Stuff Doesn’t Automatically Mean Profit

If you sold personal items for less than you paid for them, that’s typically not taxable income. Many people assume all sales count as earnings, but losses on personal-use items usually aren’t taxed at all.

Buying/selling onlineAdobe

Advertisement

Side Hustles Are Where This Rule Actually Matters

Freelancers, gig workers, and online sellers are the group most affected here. The income was always reportable—the $600 rule just makes it harder to overlook and easier for the IRS to cross-check later.
Woman working at homeVlada Karpovich, Pexels

Advertisement

Expenses Still Count (And Matter)

If you did earn income, legitimate expenses can reduce what’s taxable. Platform fees, supplies, mileage, and equipment often make a meaningful difference in the final number owed at tax time.
Lady counting moneyPhoto By: Kaboompics.com, Pexels

Advertisement

The IRS Is Not Watching Every Transaction

Despite how it feels, this rule doesn’t mean the IRS is monitoring your Venmo feed line by line. Most enforcement comes from mismatches between reported forms and filed returns—not individual everyday payments.
Use Neutral LanguageAnna Shvets, Pexels

Advertisement

This Rule Doesn’t Apply to Cash or Zelle the Same Way

The $600 threshold applies to third-party payment processors. Cash and some bank-to-bank transfers aren’t reported the same way, which adds to confusion and fuels a lot of misleading online advice.
Online BankingTumisu, Pixabay

Advertisement

Why Social Media Made This Sound Way Worse

“Venmo will tax your rent payments” spreads faster than a nuanced explanation ever could. A lot of panic came from oversimplified posts that skipped the most important distinctions entirely.
The Venmo Factor Makes It WorseMikhail Nilov, Pexels

Advertisement

Most People Who Panic End Up Owing Nothing

Tax professionals routinely report that many people who receive 1099-Ks either owe nothing extra or already accounted for the income elsewhere. The fear almost always outweighs the actual financial impact.
Woman On The PhoneKarola G, Unsplash

Advertisement

When You Should Actually Be Concerned

If you earned significant unreported income, mixed business and personal payments heavily, or ignored taxes in the past, this rule can surface issues. That’s stressful—but usually manageable with the right help.
BudgetingKaboompics.com, Pexels

Advertisement

What To Do If You Get a 1099-K

Don’t panic or ignore it. Review your transactions, separate income from personal payments, and report accordingly. When things get messy, a tax professional can usually straighten it out quickly.
Young man using calculator and laptop computer, sitting at kitchenProstock-studio, Adobe Stock

Advertisement

Why This Rule Exists in the First Place

The lower threshold was meant to improve income reporting, not target casual users. The rollout caused confusion, but the intent wasn’t punishment or increased enforcement on everyday people.
Man checking documentsKampus Production, Pexels

Advertisement

This Is More About Paperwork Than Penalties

For most people, the $600 rule creates inconvenience—not catastrophe. Better records and a little extra attention matter far more than fear or worst-case assumptions.
Businessman using laptop among crumpled paper drafts messy in office. Professional typing important document on keyboard, writing article or report, working at computer. Close up of handsfizkes, Shutterstock

If You’ve Been Using Venmo Casually, You’re Probably Fine

If your activity is mostly friends, family, and reimbursements, this rule likely doesn’t change much. The panic comes from uncertainty, not actual tax exposure.
AS_PhotographyAS_Photography, Pixabay

Advertisement

The Bottom Line

The $600 rule sounds alarming, but it’s mainly a reporting change wrapped in bad explanations. If you earned income, report it. If you didn’t, document that. Either way, this is fixable—and usually far less dramatic than it sounds.Business person, hands and writing with documents for corporate finance, proposal or budget planning at office. Japan, closeup or financial planner with paperwork or pen for company report or policyPeopleImages, Shutterstock
Advertisement

You Might Also Like:

I was supposed to receive a year's severance, but my former employer cut off my benefits and I need a root canal. What now?

The cost of living squeeze isn’t one thing. It’s all these things at once.
Sources:  1, 2


READ MORE

Prenupchallengeinternal

I wasn’t worried when my wife filed for divorce, but now she’s challenging the prenup and draining our joint account to pay her legal fees. Now what?

When your wife filed for divorce, you may have thought a prenup would protect you, but if she's using marital funds to contest the prenup you need to move quickly to protect your finances.
August 20, 2025 Marlon Wright
Inheritancedisinternal

My dad left me $220K in his will, but it means I'm going to lose my disability benefits when I claim the inheritance. What now?

If you're on disability, and a loved one leaves you a large inheritance in their will, you might find yourself at risk of losing the benefits you depend on. What can you do?
July 22, 2025 Miles Brucker
Executorinternal

I need my $60K inheritance from Dad’s will to pay my credit card debt, but the executor went on vacation. Now probate is delayed for a year. What now?

It’s difficult to wait for probate while debts go unpaid, but if the executor doesn't act in a timely fashion, your patience will be pushed to its limits.
August 12, 2025 Penelope Singh
Mcdthumb

McDonald's Has Used 45 Slogans, How Many Can You Remember?

I bet you can name a McDonald's slogan off the top of your head. Maybe you can get 3-4. If you can get all 45, I'll be VERY impressed.
April 2, 2024 Jamie Hayes
Young woman is surprised, worried, indignant.

Convenience Fees That Consumers Pay Almost Every Day Without Realizing There May Be Another Option

Convenience fees used to feel like a rare annoyance. Now they show up when Americans buy tickets, pay bills, order food, book travel, and so much more.
September 16, 2026 Sammy Tran
AI-generated image of a man worried about executor fees.

My Sibling Says Executor Fees Are Greedy, But The Estate Work Is Taking Months. When Is Payment Reasonable?

When it comes to an executor fee, the real question isn’t whether relatives should help for free, it’s whether the compensation matches the work and follows the rules governing the estate.
September 29, 2026 Peter Kinney


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕