A Tax Bill From Your Former State? Here's What You Need To Know
You've been living happily in your new state for years when a letter arrives from your old state's tax department. It says "Final Notice" and demands payment. Surely there's been a mistake? Maybe, but before you throw that letter away, there are some important things to understand.
Moving Away Doesn't Always End Your Tax Obligations
Here's the surprising part: leaving a state doesn't automatically eliminate everything you might owe its tax department. Depending on when you moved, where your income came from, and whether you filed the appropriate returns, your former state might still have a legitimate claim.
First, Don't Ignore That Letter
A final notice isn't something to toss into the recycling bin. If the bill is genuine, ignoring it could lead to penalties, additional interest, or collection action. Even if you're certain there's been a mistake, you need to respond before the applicable deadlines expire.
But Don't Rush To Pay It, Either
Seeing the words "Final Notice" can make anyone nervous, especially when the amount is substantial. However, paying immediately isn't necessarily the best solution. First, establish whether the letter is genuine, what tax year it concerns, and why the state believes you owe money.
Make Sure The Letter Is Legitimate
Unfortunately, scammers sometimes impersonate state tax agencies. Rather than trusting the telephone number or payment link on the notice, visit the state's official tax department website independently. Contact the agency through its published details and ask whether the bill actually exists.
Check Which Tax Year They're Asking About
That date is one of the most important details on the entire letter. Are they demanding taxes from the year you moved? Or are they claiming you owed money three years afterward? The answer helps determine whether this is an old liability or a disagreement about residency.

The Year You Moved Can Be Complicated
Suppose you lived in Pennsylvania until June before retiring to Florida. Depending on your circumstances, you could have filing obligations associated with both states that year. Many states have special rules for part-year residents, so an ordinary full-year return might not tell the whole story.
 https://kaboompics.com/, Pexels
You May Have Needed A Part-Year Return
When people move, they sometimes forget that their former state may require a part-year resident tax return. This generally accounts for the period they lived there and any additional income taxable by that state. Missing paperwork can eventually generate an unexpected notice.
Your Former State Might Still Tax Certain Income
Even after you've established a permanent home elsewhere, certain income can remain taxable in your former state. For example, rent collected from a property there or earnings from work physically performed there may create a nonresident filing obligation.
Keeping Your Old House Could Matter
Did you keep your former home after moving? If you rented it out, the rental income could still be taxable where the property sits. Keeping a home available for your own use may also affect residency determinations under certain state laws.
Your Driver's License Isn't The Whole Story
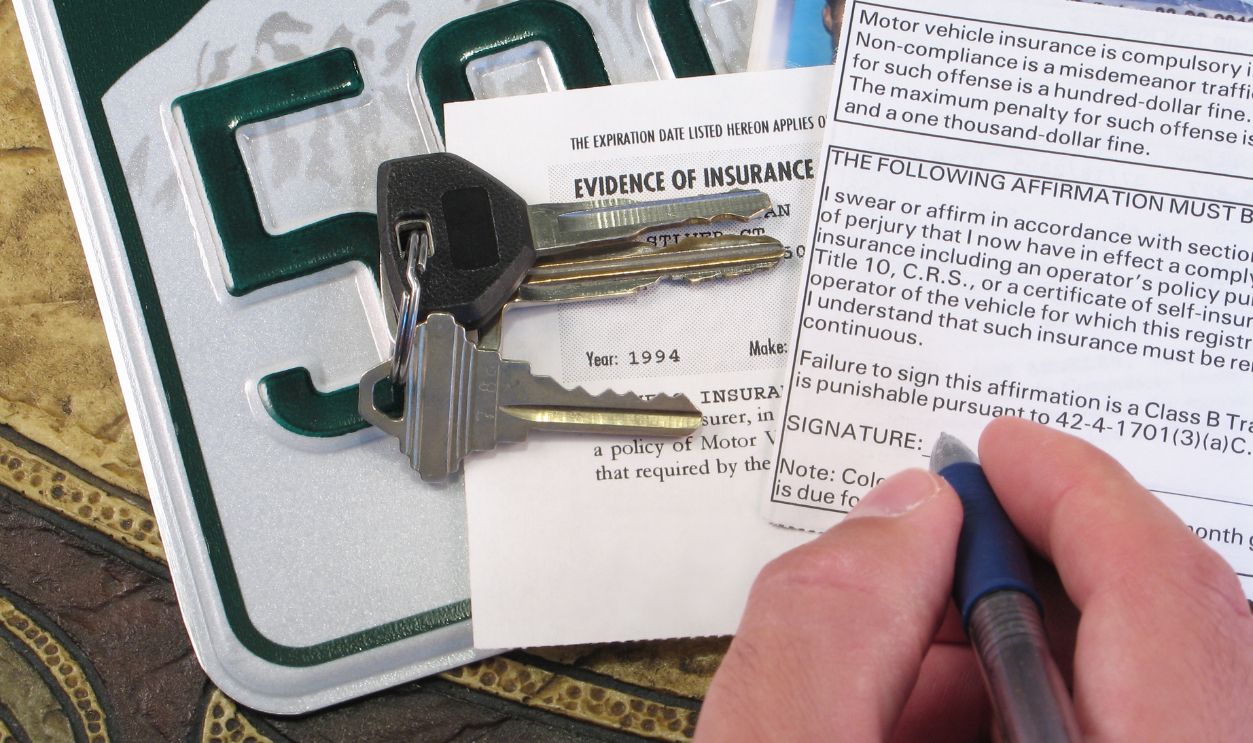
Changing your driver's license and vehicle registration helps document a move, but neither necessarily proves you changed your tax residency. States can examine where you actually lived, maintained a home, worked, and established your permanent ties during the years in question.
There's A Difference Between Residence And Domicile
These terms sound interchangeable, but tax departments distinguish between them. Your domicile generally means your intended permanent home, while statutory residency may depend on other factors. New York, for example, applies specific rules concerning permanent living quarters and days spent in the state.
Retirement Doesn't Automatically Settle The Question
Retiring and moving south is a familiar American tradition. But retirement itself doesn't establish when your former state's residency ended. Tax authorities may still examine your housing arrangements, physical presence, and other connections to determine whether you genuinely changed your domicile.
Your Pension Deserves Special Attention
There's an important federal protection for retirees. Under 4 U.S.C. § 114, states generally cannot tax qualifying retirement income received by someone who is no longer their resident. This protection covers many pensions and retirement distributions, although it doesn't eliminate every possible state tax obligation.

What About Social Security Benefits?
Social Security benefits have their own tax rules. Whether your current state taxes them is a separate question from whether your former state can establish residency or another legitimate tax obligation. Don't assume every retirement-related dollar is treated identically.
Gather Proof Of When You Moved
If the state believes you remained a resident, documentation becomes extremely important. Look for your new home's closing documents or lease, moving receipts, utility bills, vehicle registrations, and other dated records showing when you established your new home.
Dig Out Your Old Tax Returns
Those old tax returns you nearly threw away could be surprisingly useful. Find your federal returns and any state returns from the disputed years. Check the income reported, the addresses listed, and whether your former state received a part-year or nonresident return.
Ask The State To Explain The Charges
Contact the tax department and request a breakdown of the bill. Ask which income they're taxing, how they calculated the amount, and whether they've added penalties or interest. You should also establish whether this is a proposed assessment or an already finalized debt.
Sometimes The State Thinks You Never Filed
Tax departments receive income information from employers, banks, and other sources. If their records suggest you earned taxable income but no return was filed, they may contact you. The missing return could be the real problem, even if you believe you owe nothing.
Watch Out For The Appeal Deadline
Every state has its own procedures. California generally allows 60 days to protest a Notice of Proposed Assessment, while New York generally allows 90 days to challenge certain deficiency notices. Check the specific deadline and appeal rights on your letter rather than assuming you have months.
You Can Challenge An Incorrect Tax Bill
If you disagree with the assessment, follow the state's formal protest or appeal procedure. Explain why the bill is wrong and include supporting documents. Don't assume a telephone conversation or informal complaint automatically preserves your legal right to challenge the assessment.
What If The Deadline Already Passed?
A missed deadline can make the situation more complicated, but don't automatically assume nothing can be done. Contact the state immediately and ask about available reconsideration, correction, refund, or other procedures. Your options will depend on the state's laws and the status of the assessment.
Could The Bill Be Too Old To Collect?
Possibly, although states have different collection limits. California generally has a 20-year period for collecting certain tax liabilities, subject to rules that can extend or suspend it. The age of the tax year alone doesn't establish whether the government can still collect.
Moving Away Doesn't Stop Collection Efforts
Unfortunately, an outstanding state tax debt doesn't necessarily disappear when you cross state lines. Depending on the state and the debt's legal status, collection tools may include bank levies, wage garnishments, or liens. That's another reason to investigate a genuine final notice promptly.
Make Sure Your Address Is Updated
Here's a detail that's easy to overlook. If the tax department still has your previous address, earlier notices might never have reached you. California specifically warns that outdated addresses can contribute to missed deadlines, assessments, and collection problems. Update your contact information with the agency.

What If You Really Do Owe The Money?
If the charges are accurate and legally enforceable, you'll generally need to resolve the debt even though you no longer live there. Ask for an updated balance, including penalties and interest, and confirm your payment options directly with the state.
You May Be Able To Arrange Monthly Payments
Don't panic if you can't afford the full amount. Many state tax agencies offer installment agreements. California, for example, has payment plans for eligible taxpayers. Just remember that interest and applicable penalties may continue while you're paying off the balance.
Ask About Financial Hardship Options
For retirees living on a fixed income, a large unexpected tax bill can seriously disrupt the household budget. Some agencies offer hardship-related collection relief or settlement programs. California, for example, provides certain hardship accommodations and an offer-in-compromise process, subject to eligibility requirements.
When Should You Bring In A Professional?
If the bill involves multiple years, a substantial balance, disputed residency, or threatened collection, consider consulting a CPA, enrolled agent, or tax attorney familiar with that state's laws. Professional advice can be particularly valuable when you're trying to challenge an assessment that's already final.
So, Do You Actually Have To Pay?
Not necessarily. You may owe legitimate taxes from before you moved or on income earned afterward in your former state. But an incorrect residency determination, missing paperwork, or mistaken assessment could change the outcome. Verify the debt, examine the evidence, and exercise your available appeal rights.
The Bottom Line: Don't Ignore It, But Don't Panic
Receiving a final tax notice from somewhere you haven't lived in years is unsettling. Still, the important question isn't how long you've been gone. It's whether the state has a valid, enforceable claim. Check the facts, protect your deadlines, and only pay what you legally owe.
You May Also Like:
My Credit Union Is Merging With Another Institution. What Happens To My Deposits And Insurance?