A Family Boat Deal With Retirement Tied To It
Your father wants you to buy his boat at full price so he can use the money for retirement. On paper, that may sound simple. In reality, it wraps family loyalty, a major purchase, and a retirement shortfall into one awkward deal. Saying no does not make you selfish, especially if the timing, price, or your own finances do not line up.
Why This Feels So Loaded
In a family, a boat is rarely just a boat. It can hold years of memories, pride, and a strong sense of what it should be worth. Once that emotional value gets tied to a retirement plan, turning it down can feel like much more than passing on a purchase.
Start With The Price
If your father is asking full price, the first question is whether that number matches the real market. Used boat values are not simple. Condition, engine hours, maintenance history, age, and location all matter. Even in a family deal, the price should come from outside facts, not emotion.
Boat Prices Are Not A Guess
NADA Guides, now run through J.D. Power, is still one of the best-known tools for used boat values. It gives buyers and sellers a way to estimate price based on boat type, model year, and options. That takes some of the pressure out of a family negotiation.
A Survey Can Change The Whole Deal
Before paying full price for a used boat, getting a marine survey is often the smartest step. BoatUS has long advised buyers to use a professional survey because hidden problems can be expensive and even unsafe. A boat can look great at the dock and still turn into a money pit once a pro starts checking it over.
The Cost Does Not End With The Sale
Even if the asking price is fair, that is only the beginning. The U.S. Coast Guard and boating groups regularly remind owners that maintenance, insurance, storage, fuel, and registration all add up. If you do not really want the boat, paying full price could lock you into years of costs you never wanted.
A Retirement Plan Should Not Hang On One Sale
There is another hard truth here. If your father needs you, specifically, to pay full price so he can retire, that suggests his plan may be shaky. The Consumer Financial Protection Bureau warns people to watch for family financial arrangements that create pressure, guilt, or confusion.
You Are Not A Retirement Fund
Parents can sell assets. Children can say no to buying them. Both things can be true at the same time, even when feelings run high. A retirement gap is serious, but that does not automatically make it your job to fill it by overpaying for something you may not even need.
Fair Does Not Always Mean Full Price
Family sales often happen below retail value because they avoid listing fees, save time, and keep the item in the family. Full price could still make sense if the boat is in excellent shape and you actually want it. But you do not owe full price just because the seller is your father.
What The IRS Looks At In Family Sales
The Internal Revenue Service pays attention when family members transfer assets for less than fair market value because part of the deal could count as a gift. That does not mean every discount causes a problem, but it does mean the price should be thoughtful and documented. If the amount is large, talking to a tax pro makes sense.
Retirement Accounts Have Rules Too
If your father is trying to close a retirement gap, he may have options besides leaning on a family sale. The IRS publishes annual rules on catch-up contributions for older savers. Depending on his age, income, and timing, he may be able to strengthen his plan with more contributions, delayed retirement, or a broader plan for his assets.
 Kobus L/peopleimages.com, AdobeStock
Social Security Timing Can Matter
The Social Security Administration makes clear that the age when someone claims benefits can change the monthly amount. For some retirees, waiting can raise long-term income. That will not solve every cash crunch, but it is another reason one boat sale to one family member should not be treated as the only answer.
Real Value Needs Real Paperwork
If your father believes the boat is worth full price, ask to see maintenance logs, engine records, upgrade receipts, and any recent survey. That moves the talk away from guilt and toward proof. If the records support the asking price, you can look at the deal more clearly.
A Sea Trial Matters
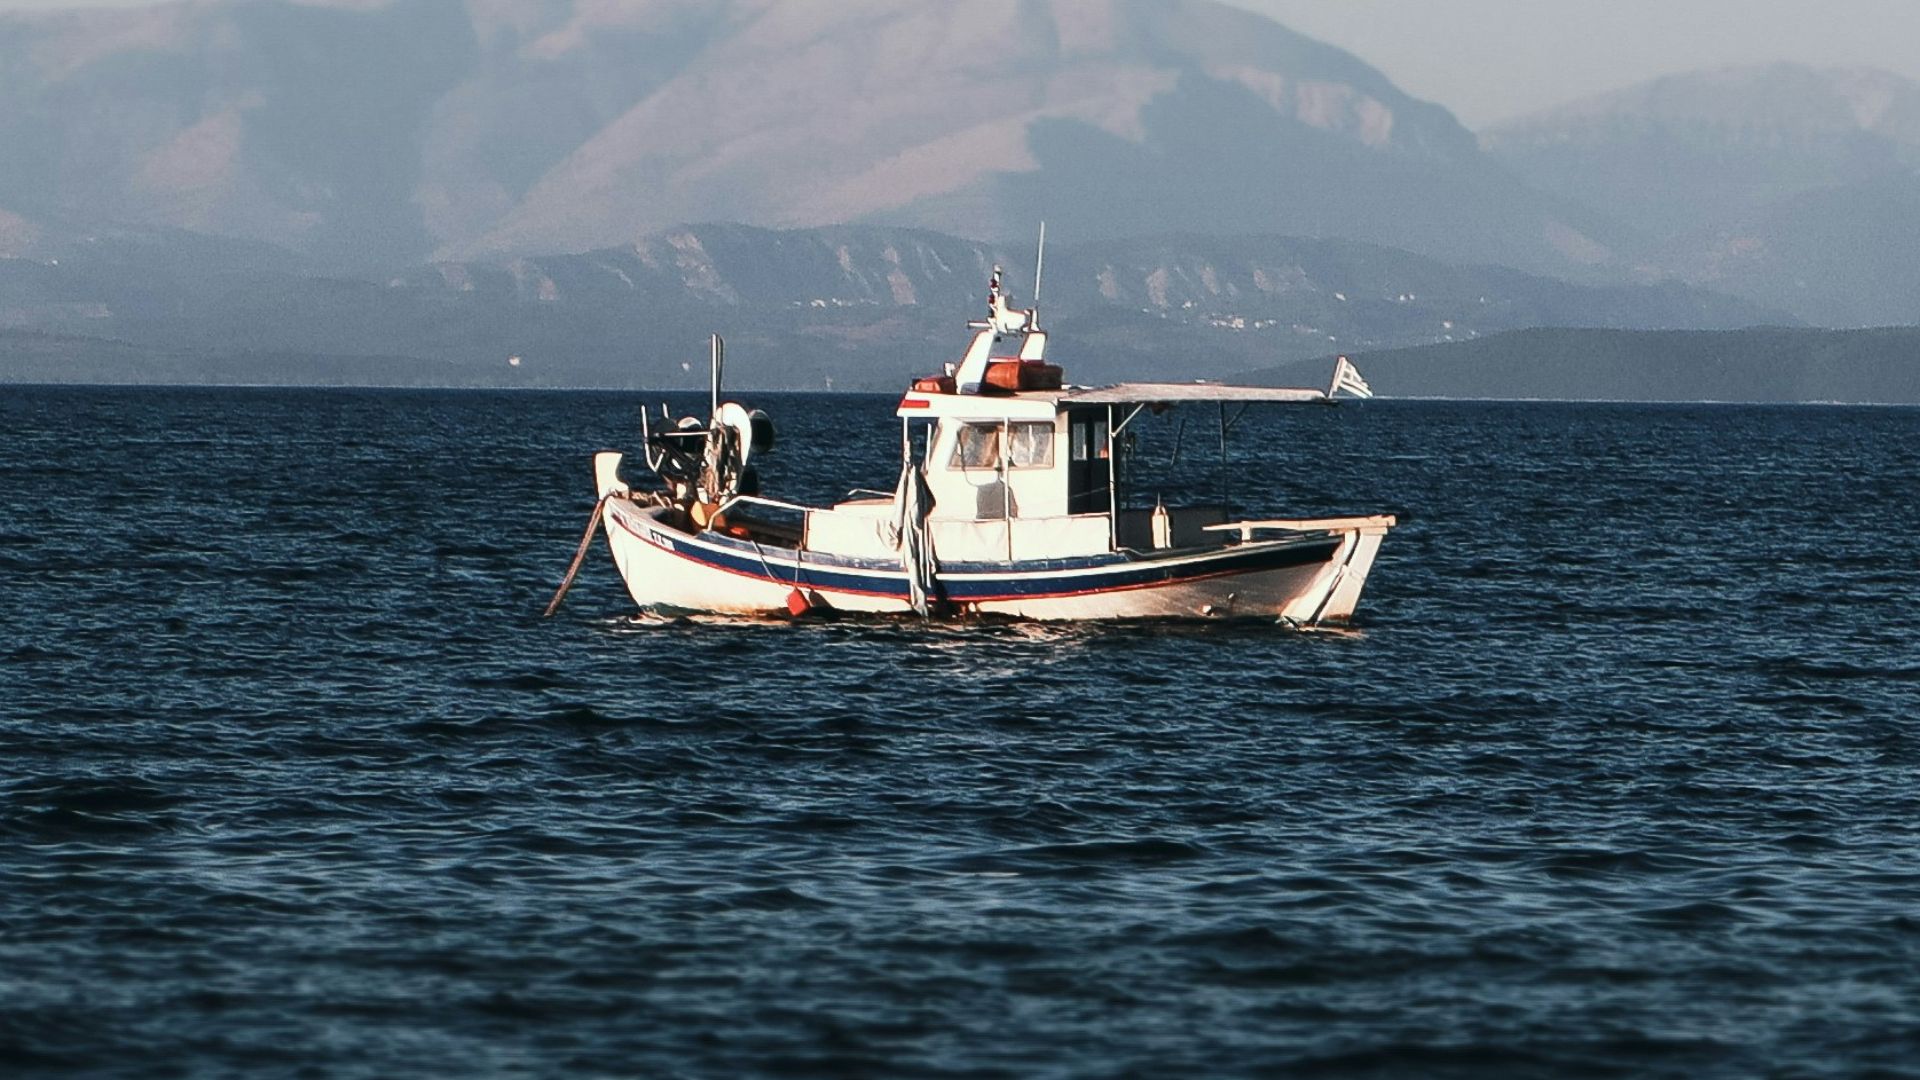
A used boat should be tested on the water before anyone buys it. BoatUS advises buyers to treat the sea trial as a key part of due diligence, not just a quick spin. Steering issues, vibration, electronics problems, or weak performance often show up only when the boat is actually running.
The Emotional Markup Is Real
Family sellers often give an item extra value because they remember what they paid, how much they loved it, or the plans they had for it. The market does not pay for nostalgia the way families do. That gap is where a lot of these fights start.
Your Finances Come First
If buying the boat would drain your savings, add debt, or throw off your own retirement goals, saying no is the smart move. The Federal Trade Commission regularly urges consumers to make major money decisions based on verified terms and what they can actually afford. A family request does not change the math.
Helping Is Not The Same As Subsidizing
You may want to help your father without stepping into a bad deal. Helping could mean assisting with the listing, finding comparable sales, or paying for a survey that helps him sell it. Subsidizing means you take on the cost and risk so he does not have to face the real market.
A Neutral Appraisal Can Cool Things Off
One of the best ways to lower the tension is to bring in a neutral third party. A marine surveyor or broker can give an estimate of condition and market value without the family baggage. That gives everyone a shared set of facts instead of clashing opinions. Freeday photo, Shutterstock
If You Want The Boat, Set Clear Terms
Maybe you do want it, just not under the current terms. If so, insist on a written agreement, an independent valuation, title transfer paperwork, and clarity on trailers, gear, liens, and repairs. Family sales go sideways when people assume good intentions can replace paperwork.
If You Do Not Want The Boat, Say So
Sometimes the clearest answer is also the simplest one: you do not want to own a boat. That is a valid reason on its own. You do not have to take on a floating expense just to avoid disappointing someone.
What To Say If The Talk Gets Tense
You can say, “I want to support you, but I cannot buy the boat at a price that does not fit my finances or the market.” It is respectful and direct. It shows you understand his position without pretending your wallet is the fix for his retirement plan.
Retirement Stress Can Twist Family Deals
Money pressure can make normal boundaries look personal. That is why financial counselors often tell families to separate love from business whenever they can. A good relationship is more likely to survive a declined sale than a deal that leaves one side feeling trapped or resentful.
What If He Says You Are Taking Advantage
If you offer less than he wants, he may take it as an insult. Remind him that market value is not a judgment on his memories or his choices. It is simply the number a willing buyer would likely pay after looking at condition, risk, and other options.
What If He Says He Needs The Money Right Now
Urgency does not prove that the deal makes sense for you. If he truly needs cash fast, selling to the open market may still be the better move, even if it takes more effort. A rushed family sale can leave behind years of regret.
The Best Middle Ground May Be No Sale
Sometimes the fairest outcome is helping him sell the boat to someone else for whatever price the market will support. That gives him a shot at raising retirement funds without pushing you into ownership. It can also keep your relationship from turning into one long fight over value.
So, Are You Wrong To Refuse
No. You are not wrong to refuse to buy your father’s boat at full price, especially if the value is unclear or the purchase would hurt your own finances. The smart move is to confirm the boat’s real market value, separate emotion from the price, and remember that retirement planning should not depend on pressuring a child into a major purchase.