A Big Family Gift Can Sound More Taxing Than It Really Is
Handing children part of their inheritance while everyone is still around to enjoy it can sound much easier than dealing with an estate later. However, once the amount gets large enough, tax questions start appearing fast. The surprising part is that the biggest tax issue may not be the one families expect.
The Recipient Usually Doesn't Pay Federal Income Tax
One of the biggest misconceptions is that receiving a large cash gift automatically creates taxable income for the recipient. Generally, it doesn’t. If parents give an adult child $50,000 as a genuine gift, the child normally doesn’t add that $50,000 to taxable income simply because the money arrived in a bank account. Federal gift-tax rules primarily concern the person giving the property.
The Gift Tax Is Primarily The Donor's Responsibility
Under federal law, the person making the gift is generally responsible for any required gift-tax reporting and, in the relatively uncommon situation where tax is actually owed, the tax itself. That distinction matters because parents can transfer amounts far larger than many families realize before writing a federal gift-tax check.
The 2026 Annual Exclusion Is $19,000
For 2026, one person can generally give another person up to $19,000 during the year without using any of the donor's lifetime federal gift-and-estate tax exemption. The annual exclusion applies separately to each recipient. A parent could therefore give $19,000 to each of three children and potentially have all three gifts fall within the annual exclusion.
Two Parents Can Potentially Give $38,000 To One Child
Because each donor gets a separate annual exclusion, two parents can generally transfer a combined $38,000 to the same child during 2026 without dipping into either parent's lifetime exemption, assuming the gifts qualify for the annual exclusion. If those parents have several children, the exclusion applies separately to each recipient rather than being a single $38,000 family limit.
Giving More Than $19,000 Doesn't Automatically Trigger A Tax Bill
This is where families often become unnecessarily alarmed. Suppose one parent gives a child $50,000 in 2026. The first $19,000 may qualify for the annual exclusion, while the remaining $31,000 generally becomes a taxable gift for reporting purposes. That doesn't necessarily mean the parent owes gift tax. The excess can usually be applied against the parent's much larger lifetime exemption.
The Lifetime Exemption Is Enormous For Most Families
For 2026, the federal basic exclusion amount for gift and estate tax is $15 million per individual. That means most families can make gifts exceeding the annual exclusion without paying federal gift tax because the excess simply reduces the amount that can later pass under the donor's remaining lifetime estate-and-gift exemption. Very wealthy families need to plan around that number carefully, but ordinary families shouldn't confuse "taxable gift" with "tax immediately due".
Form 709 May Still Be Required
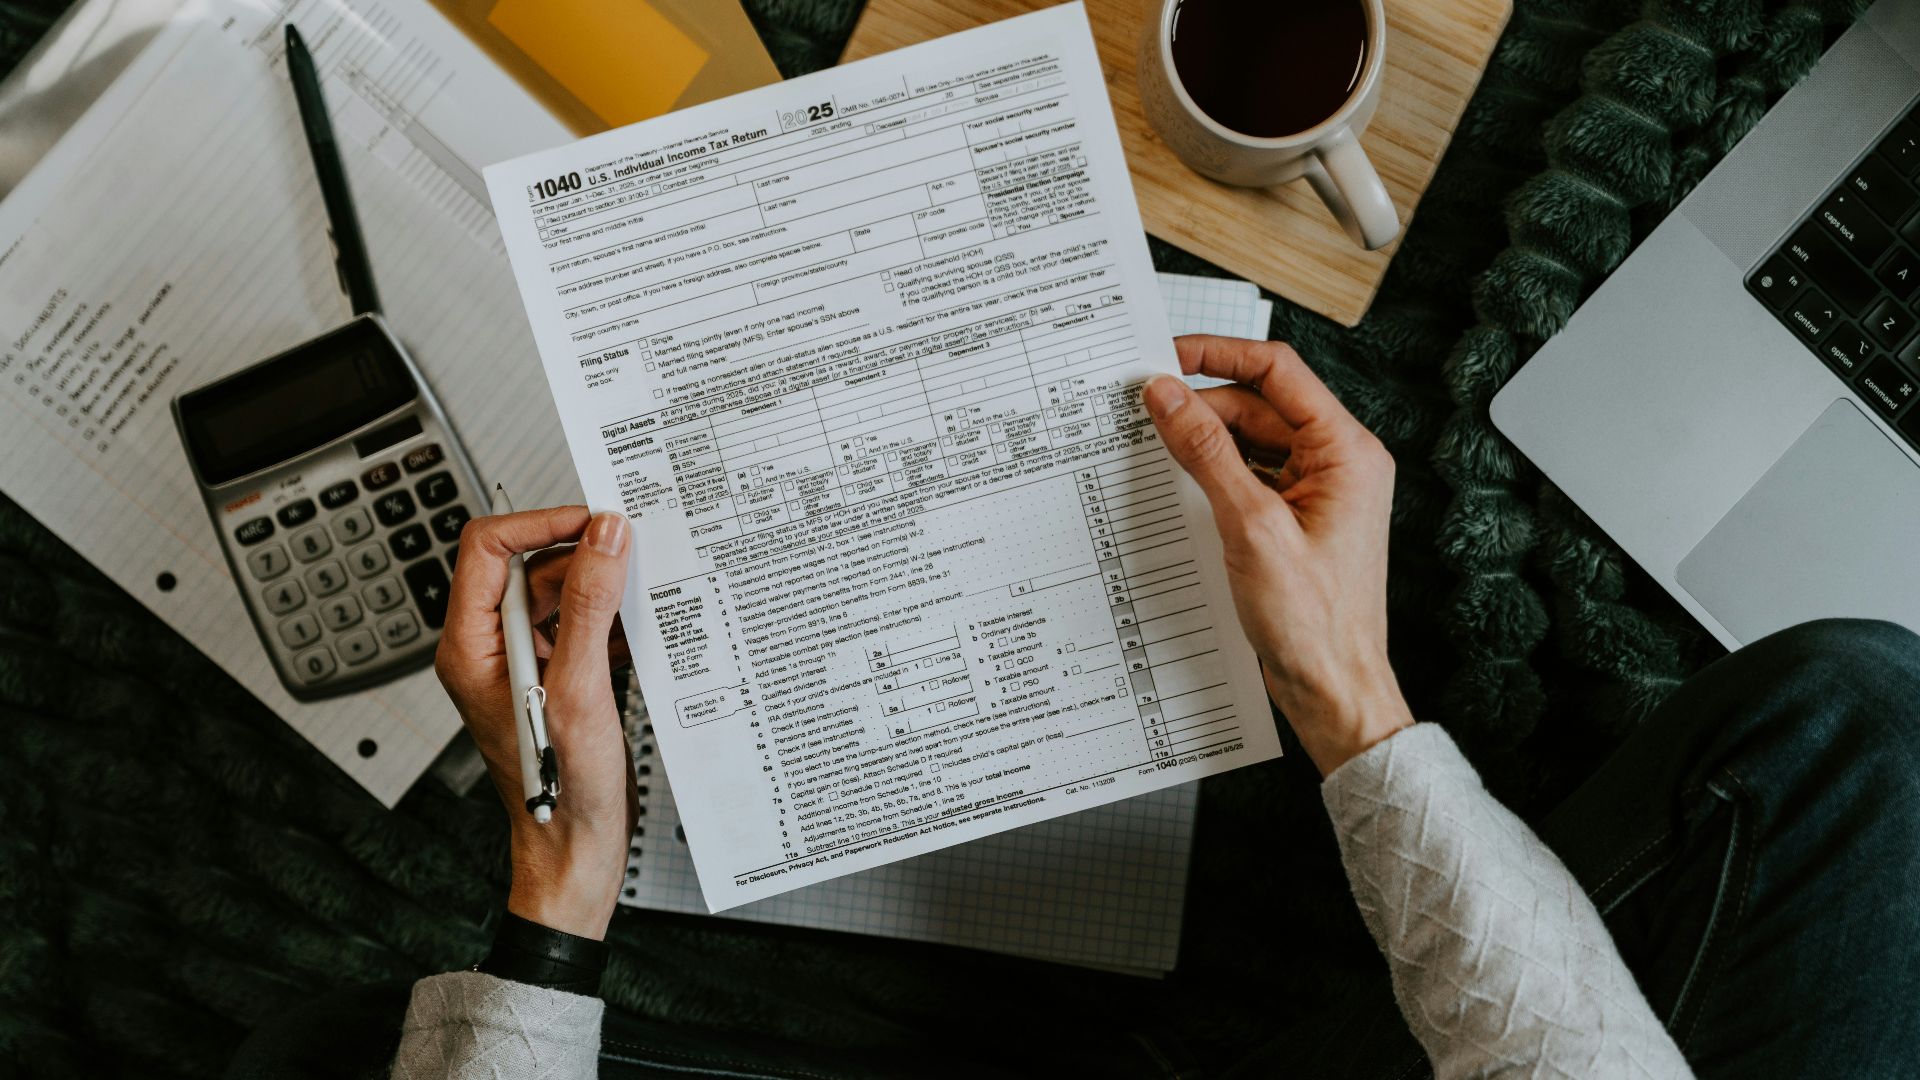
Even when no gift tax is owed, the donor may have to file IRS Form 709, the United States Gift and Generation-Skipping Transfer Tax Return. Generally, a gift above the annual exclusion to a particular person requires reporting unless another exclusion applies. The return tracks how much of the donor's lifetime exemption has been used.
Filing A Gift-Tax Return Isn't The Same As Paying Gift Tax
Parents sometimes deliberately keep gifts below the annual exclusion because they believe crossing it creates an immediate tax. Often, what it actually creates is paperwork. A properly filed Form 709 reports the gift and applies the excess against the lifetime exclusion. For families far below the federal estate-tax threshold, the difference between filing a return and owing tax can be enormous.
Gift Splitting Can Help Married Parents
Married couples can sometimes elect to treat gifts as though each spouse gave half, a strategy known as gift splitting. This can allow them to use both spouses' annual exclusions even when the money technically came from one spouse's property. Gift splitting has specific Form 709 requirements, however, so couples making substantial gifts should have a tax professional handle the paperwork rather than assuming the transfer automatically qualifies.
Cash Is Usually The Simplest Asset To Give
From a tax-basis perspective, cash is straightforward. Giving someone $30,000 doesn't create the future capital-gains complications that can come with transferring a house, stock portfolio, or other appreciated asset. If parents simply want to provide financial help and have sufficient cash available, the tax analysis can be significantly simpler than gifting property they've owned for decades.
Appreciated Stock Is A Very Different Gift
Suppose parents bought stock for $20,000 years ago and it's now worth $100,000. If they give the shares to a child, the child generally receives the donor's existing tax basis rather than resetting the basis to today's $100,000 market value. If the child later sells the stock, that old embedded gain can become important.
Inherited Assets Often Receive A New Basis
Property inherited after someone's passing generally receives a basis tied to its fair market value at the date of death, subject to certain exceptions. That can dramatically reduce capital gains on assets that appreciated over many years. As a result, giving highly appreciated stock or real estate shortly before passing can sometimes produce a worse income-tax result than leaving the same property through the estate.
That Makes "Give It All Away Now" A Potentially Expensive Strategy
Gift and estate tax aren't the only taxes that matter. Parents with an estate far below the $15 million federal exclusion may gain little estate-tax advantage from gifting appreciated assets, while the recipient inherits a low tax basis. Before transferring a longtime family home, investment property, or heavily appreciated securities, families should compare the gift-tax result with the future capital-gains result.
Gifting The House Deserves Extra Caution
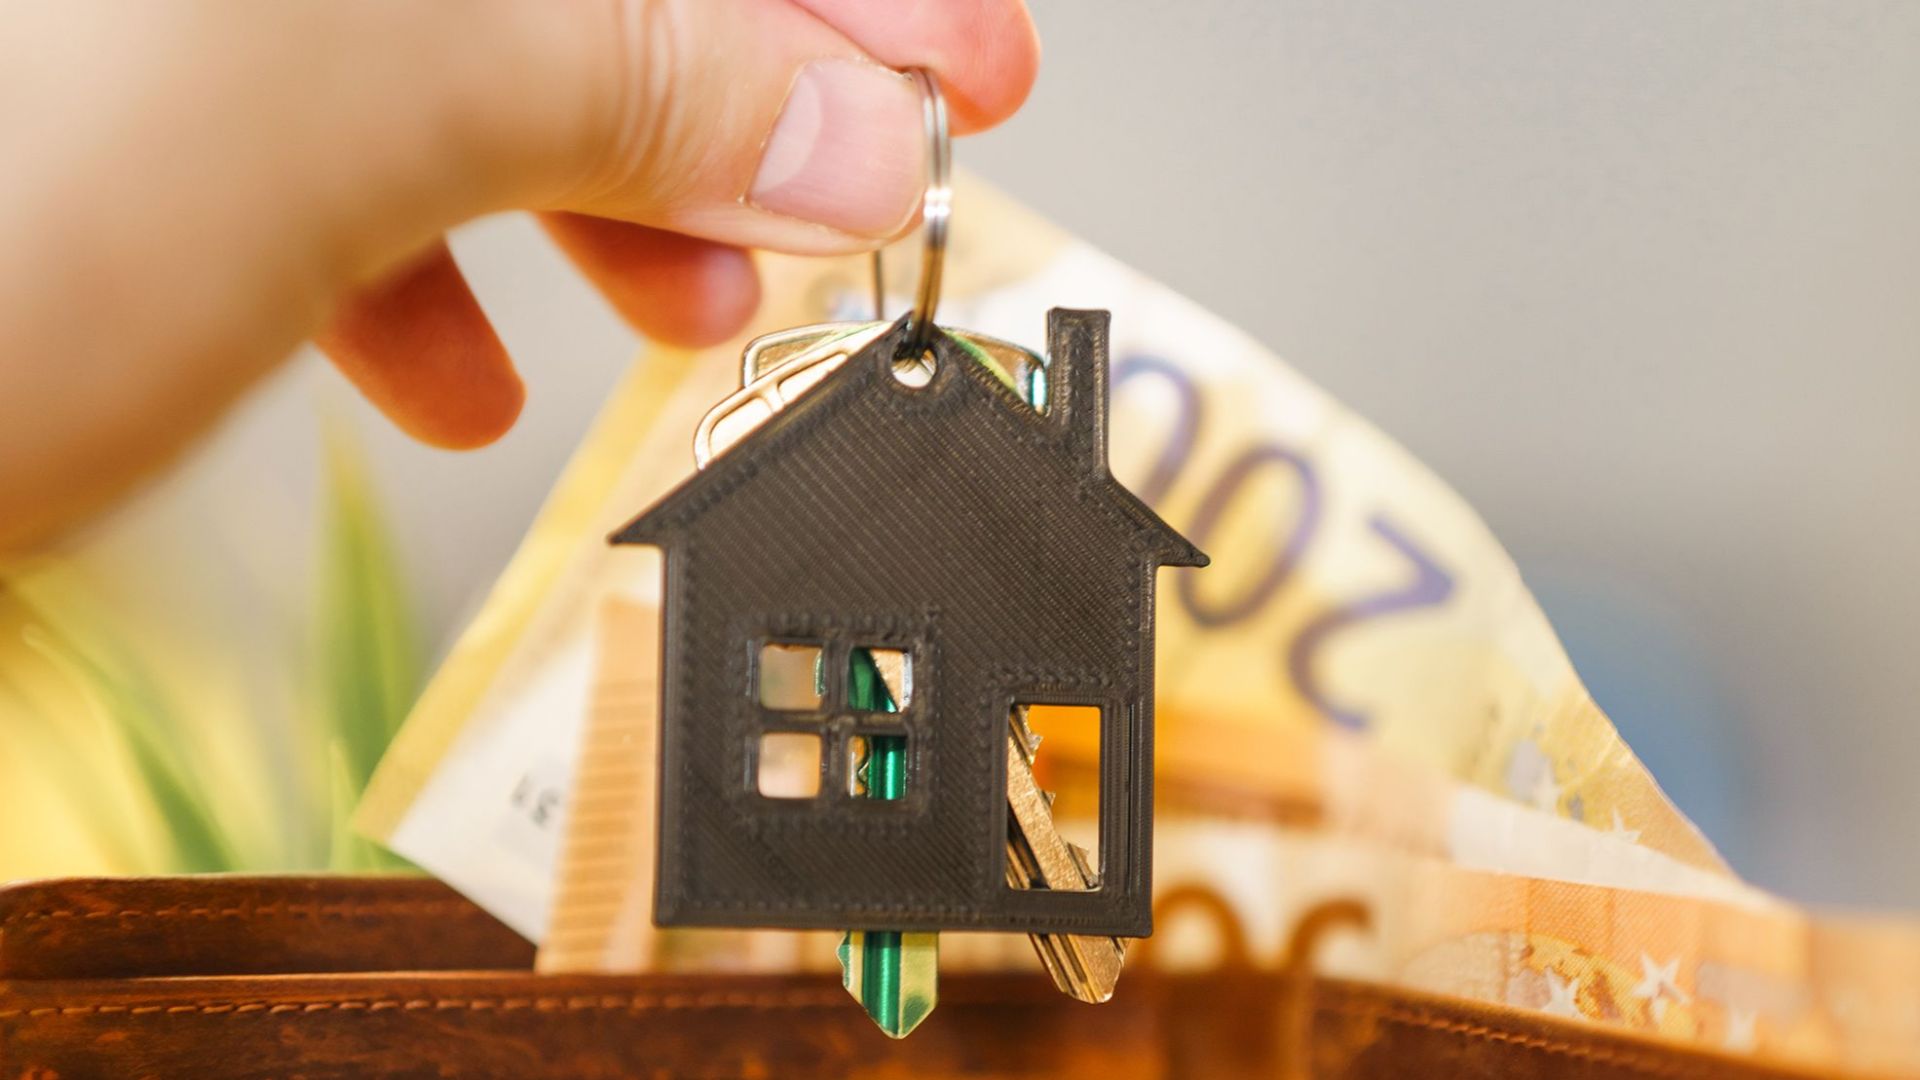
Parents sometimes think transferring the deed now is an easy way to keep a house out of the estate. It can instead create capital-gains, property-tax, creditor, ownership, Medicaid, and family-dispute issues. The recipient may receive the parents' old basis rather than the potentially more favorable basis that could apply to inherited property. A house transfer is significant enough to justify estate-planning and tax advice before anyone signs a deed.
Medical Bills Have A Special Exception
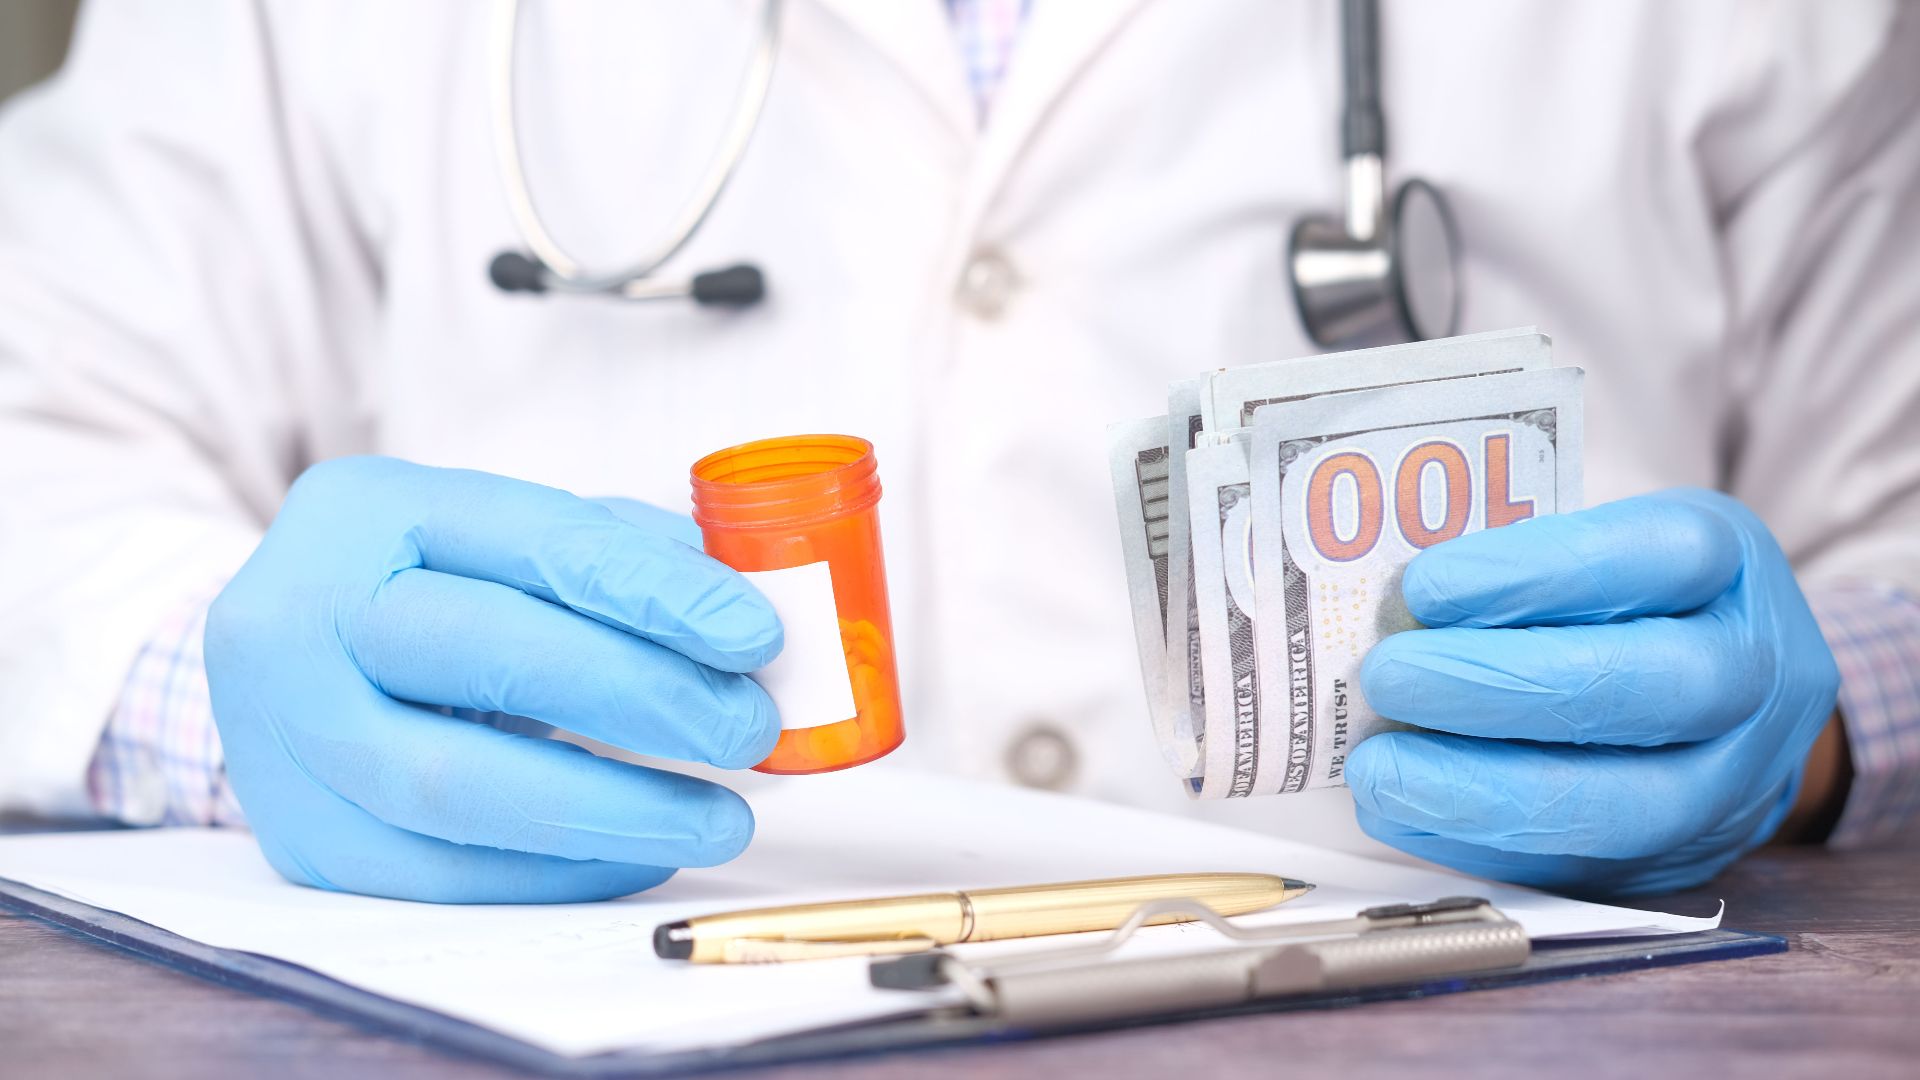
Parents can generally pay another person's qualifying medical expenses directly to the medical provider without those payments counting against the normal annual gift-tax exclusion. The word "directly" matters. Giving the child $30,000 and telling them to pay the hospital isn't necessarily treated the same way as paying the hospital itself.
Tuition Has A Similar Rule
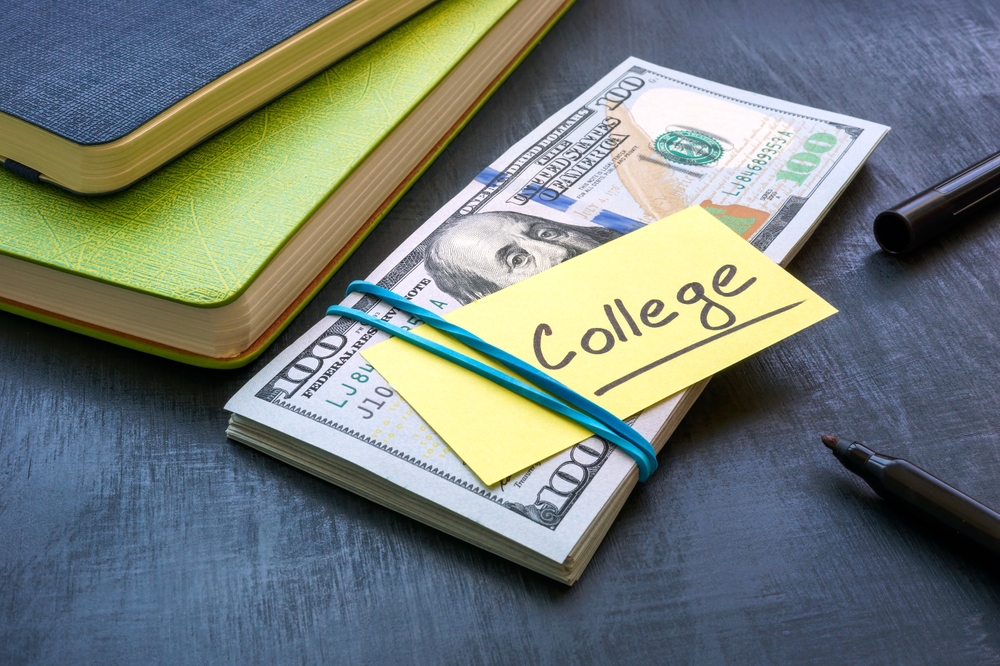
Qualifying tuition paid directly to an educational institution can generally fall outside the normal gift-tax limits as well. That can let parents or grandparents help with substantial education costs without consuming the annual exclusion or lifetime exemption. The special exclusion generally applies to tuition itself, not simply to every education-related expense such as housing, books, or spending money.
 Vitalii Vodolazskyi, Shutterstock
529 Plans Offer Another Planning Tool
Families helping younger generations with education can also consider 529 college-savings plans. Federal tax rules allow donors to elect to spread a larger 529 contribution over five years for gift-tax purposes. Because the annual exclusion is $19,000 in 2026, potentially significant amounts can be contributed upfront while using several years of annual exclusions, although Form 709 reporting is involved.
Don't Forget About Medicaid's Five-Year Lookback
Gift-tax planning and long-term-care planning are not the same thing. Medicaid generally reviews certain asset transfers made during the five years before someone seeks coverage for long-term services and supports. Giving away money for less than fair market value during that period can potentially create a penalty that delays Medicaid coverage for long-term care, subject to exceptions.
The Annual Gift-Tax Exclusion Doesn't Protect Against Medicaid Rules
This is an especially dangerous misunderstanding. A parent may hear that giving each child $19,000 is "tax free" and assume the transfer is harmless for every government program. It isn't. A gift can fit comfortably within federal gift-tax rules and still create issues under Medicaid eligibility rules. Parents who may need long-term care should talk with an elder-law attorney before transferring substantial assets.
State Taxes Can Add Another Layer
Federal gift tax receives most of the attention, but families shouldn't assume federal rules are the entire story. States have their own estate, inheritance, and related tax systems, and those rules vary considerably. Where the parents live, where property is located, and where heirs live can all matter. Large transfers deserve a state-level tax review as well as a federal one.
Keep Records Of Large Family Gifts
Parents should document what was transferred, when it happened, how much it was worth, and whether a Form 709 was filed. Records become particularly important for gifted stock, real estate, business interests, and other property whose tax basis may matter decades later. Future heirs shouldn't have to reconstruct the parents' original purchase price from a shoebox of statements after everyone who knew the answer is gone.
A Down-Payment Gift May Need Extra Paperwork
If parents are providing money for a child's home purchase, the mortgage lender may ask for a gift letter confirming that the money isn't secretly a loan that has to be repaid. That mortgage documentation is separate from IRS gift-tax reporting. Families should be truthful about whether the transfer is genuinely a gift because disguising a family loan as a gift can create problems for both the mortgage application and future family finances.
An Interest-Free "Loan" Can Create Its Own Tax Questions
Calling a transfer a loan doesn't automatically avoid gift-tax rules. The IRS can treat below-market or interest-free loans as producing a gift under certain circumstances. If parents genuinely expect repayment, a written promissory note, appropriate interest rate, payment schedule, and records of actual repayments can help demonstrate that the arrangement really is a loan rather than an undocumented gift.

Parents Should Make Sure They Can Afford To Be Generous
Tax efficiency isn't much consolation if parents give away money they later need for housing, healthcare, long-term care, or ordinary living expenses. Before making a large lifetime gift, they should model their own retirement needs and maintain adequate emergency reserves. Once money is genuinely gifted, getting it back may depend entirely on the recipient's willingness and financial ability to return it.
Sometimes The Best Answer Is A Mix Of Gifting And Inheritance
Families don't necessarily have to choose between giving everything now and leaving everything later. Parents might use annual cash gifts for immediate help while retaining highly appreciated assets that could receive more favorable basis treatment at death. They might pay tuition directly, contribute to 529 plans, or make larger reported gifts when there is a clear estate-planning reason. The right mix depends on the family's assets, health, estate size, and goals.
Don't Let Fear Of "Gift Tax" Stop Sensible Planning
For most American families, receiving money from parents doesn't create federal income tax for the recipient, and giving more than $19,000 in 2026 doesn't automatically mean the parents owe gift tax. The real issues are often Form 709 reporting, the $15 million lifetime exclusion, capital-gains basis, Medicaid planning, and whether the parents can comfortably afford the transfer. Before moving a house, investments, or a very large amount of money, a CPA or estate-planning attorney can help make sure a generous decision doesn't create a tax problem nobody expected.
You May Also Like: