Adjustablemortgageinternal

What To Do When You Have An Adjustable Rate Mortgage And Rates Go Up


April 23, 2025 | Jane O'Shea

What To Do When You Have An Adjustable Rate Mortgage And Rates Go Up


After years of renting, buying your first home is an exciting milestone. The keys in your hand, the sense of permanence, and the pride of ownership are all unforgettable. But when the celebration is followed by rising mortgage payments due to an adjustable-rate mortgage (ARM), things can change in a hurry.

Good Times And Bad Times

Many buyers choose ARMs for their initially low interest rates, especially when fixed-rate options seem unaffordable. But when those rates adjust upward—as they often do in a volatile market—you can find yourself paying hundreds or even thousands more per month. If you’re in this position, here’s what to know and what you can do next.
Kindel MediaKindel Media, Pexels

Advertisement

Understand The Terms Of Your ARM

Before you panic, take a deep breath and review your mortgage documents. Most ARMs have an initial fixed-rate period (commonly 3, 5, 7, or 10 years) followed by an adjustment schedule (e.g., annually after the fixed period). They normally also have caps that limit how much your interest rate can increase at each adjustment and over the life of the loan. With these hard numbers in hand you can make a properly informed decision on how to proceed.

Look At The Hard Numbers

If your rate has already adjusted, compare your current rate to the cap. You might still have room before it hits its ceiling, or you might be close to maxed out. Understanding where you are in that arc helps you assess your urgency and your options.

Assess Your Monthly Budget

Next, look at how much your mortgage payment has increased and re-evaluate your monthly expenses. Can you cut discretionary spending (streaming services, dining out, vacations) to absorb the difference? This won’t be a long-term solution if rates keep rising, but it can buy you time. Also consider if your income has grown since you bought your home. Sometimes a promotion or second income source can help offset the spike.
RDNE Stock projectRDNE Stock project, Pexels

Advertisement

Consider Refinancing

If your credit score and income are strong, changing to a fixed-rate mortgage may be the simplest solution. This locks in a fixed payment and shields you from future hikes. Even if current fixed rates are higher than your original ARM rate, locking in now can prevent escalation down the road. Keep in mind refinancing often has closing costs from 2–5% of the loan amount. Run the numbers to see if the long-term savings justify the upfront cost.

Explore Loan Modification

If refinancing isn’t possible—perhaps due to lower income or a dip in your home’s value—talk to your lender immediately. In some cases, they may be willing to modify your loan terms, especially if you’ve been making payments consistently.

Explore Assistance Programs

Some state or federal programs may also offer mortgage relief assistance, especially in times of widespread economic difficulty. These won’t apply to everyone, but they’re worth exploring if you’re at risk of falling behind.
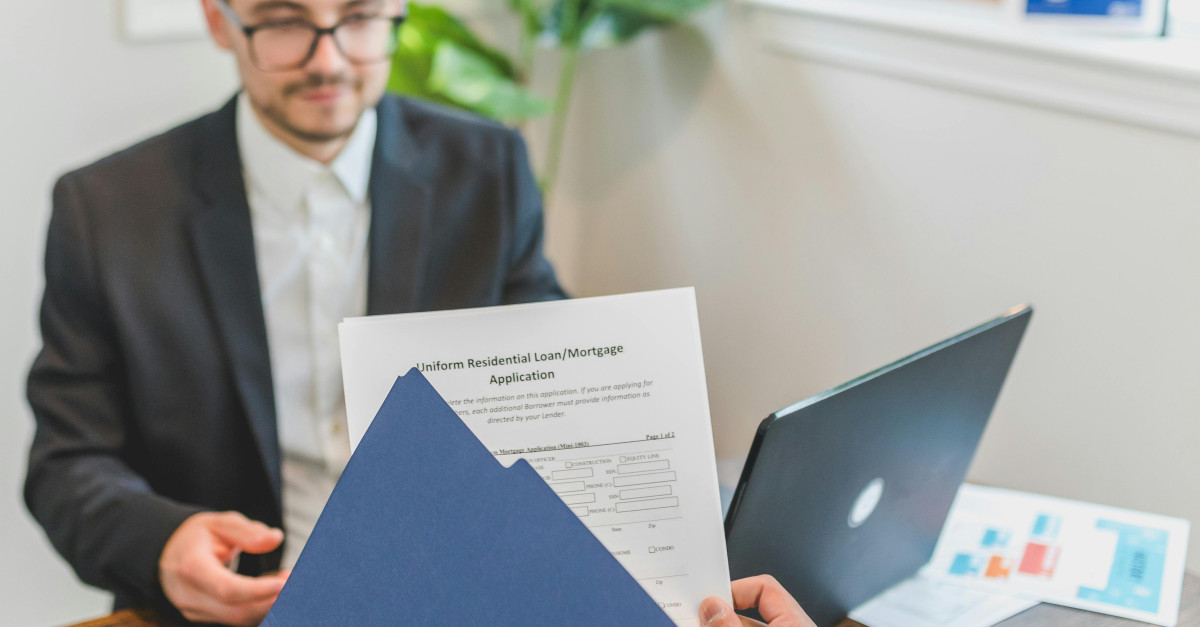
RDNE Stock projectRDNE Stock project, Pexels

Advertisement

Rent Out Space Or Generate Supplemental Income

If your home has an extra room, basement, or separate unit, consider renting it out. Platforms like Airbnb or longer-term leases can provide the cash flow to help cover your rising mortgage costs. Other options include side gigs, freelancing, or remote part-time work. These might feel like short-term fixes, but they can make a difference in weathering rate adjustments.

Selling May Be A Last Resort—But Not A Failure

If payments become unmanageable and no other options work, selling your home may be necessary. This isn’t failure—it’s financial self-preservation. If your home has appreciated, you might walk away with a profit and be in a better position to buy again later with a fixed-rate loan and more experience. It’s better to sell on your terms than face foreclosure down the line.

Be Proactive, Not Paralyzed

Rising payments on an ARM can feel like the rug being pulled out from under you, but you’re not helpless. Understand your mortgage terms, evaluate your options, and stay in contact with your lender, and you’ll be able to make the best decisions that protects your financial future. The key is to act early; the sooner you respond, the more choices you’ll have.

You May Also Like:

Simple Things You Can Do To Increase The Value Of Your Home

Money Management Apps & Tools To Help You Improve Your Finances

Understanding Mortgage Prepayments
Sources: 1, 2, 3


READ MORE

Couple Discussing

My husband insists we should stop paying extra on our mortgage and put every spare dollar into stocks. Is investing always better?

It is an argument happening at kitchen tables all over America. One spouse wants the guaranteed win of paying down the mortgage faster, while the other wants to chase the higher long-term returns that stocks have often delivered. The truth is that investing is not always better than becoming debt-free, and the smartest answer depends on your interest rate, your risk tolerance, and your timeline.
September 23, 2026 Jamie Hayes
stressed and upset man with documents in front of his inherited home

My grandmother left me her house, but the family expects me to let my unemployed cousin live there rent-free. Am I selfish to sell it?

It sounds like a windfall, but inheriting a house can turn into a family standoff fast. One common flashpoint is when relatives assume the new owner should let someone stay there for free, sometimes for months or even years. If you inherited your grandmother’s home and now feel pressure to house an unemployed cousin indefinitely, the real question is not whether you are selfish. It is whether you are being asked to shoulder a financial burden that was never actually yours.
September 23, 2026 Jamie Hayes
My parents paid for my college, but now they want the money back

My parents paid for my college, but now they want the money back because I earn more than my siblings. Can a gift become a loan years later?

It is a stomach-dropping moment. Your parents paid for college years ago, never mentioned repayment, and now they want the money back because you earn more than your siblings. The big legal question is simple but loaded: can a gift be turned into a loan after the fact.
September 23, 2026 Jamie Hayes
Facebook  Internal

My wife opened a store credit card in my name to get 20% off a renovation purchase. Am I wrong to be uncomfortable with that?

A store card opened for a one-time renovation discount can look like a harmless shortcut. But if your spouse opened that account in your name without your permission, the discount may be the smallest part of the story. What starts at the checkout counter can quickly turn into identity theft, credit damage, and a legal mess inside a marriage.
September 23, 2026 Miles Brucker
Internalfb Image (1)

Mom had a fall and needs care, but I live far away. My sister moved in, and now she expects reimbursement. Are siblings expected to split caregiving?

It often starts with love and ends with resentment. One sibling lives nearby and becomes the default caregiver, while another lives hours away and gets accused of doing too little. The painful question is whether a brother or sister can fairly demand reimbursement for caring for an aging parent.
September 23, 2026 Miles Brucker
worried woman with calculator and documents, listening to her husband and son in discussion

My husband wants to borrow against his pension to help our son start a business. Is risking retirement for an adult child ever sensible?

Helping an adult child launch a business can feel like a proud family milestone. It can also become a retirement trap when the money comes from assets meant to support you for the rest of your life. If your husband wants to borrow against his pension, the first question is not whether your son’s idea is promising, but whether your retirement can survive the risk.
September 23, 2026 Jamie Hayes


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team