The Calls Started After He Died
Your father dies, then the phone starts ringing. A collector says there are unpaid medical bills and wants to know who is handling them. It can sound like the debt has landed in your lap. In most cases, it has not, but there are exceptions worth knowing before anyone pays.
His Debt Usually Does Not Become Your Debt
Adult children generally do not become responsible for a parent’s medical debt simply because they are family. Valid debts are usually handled through the deceased person’s estate. If the estate cannot pay and nobody else is legally liable, some debts may remain unpaid. Being someone’s child does not automatically make you the debtor.
The Estate Is Where The Bills Usually Go
The estate includes property and assets legally belonging to the person who died. The executor or administrator generally handles valid creditor claims using estate assets. That does not mean the executor must personally cover the bills. They are managing the estate, not taking on the debt.
Executors Need To Be Careful
Serving as executor does not normally make someone personally responsible for the deceased person’s debts. Problems can arise, however, if estate assets are distributed or handled in violation of probate law. That is why bills should not simply be ignored or paid at random. The estate process matters.
Do Not Pay The Loudest Creditor First
Collectors can create urgency, but that does not mean the first caller gets the first check. State probate laws can control how claims are reviewed and prioritized. Paying one creditor too quickly can create problems if higher-priority claims appear later. Follow the estate rules, not the pressure level.
A Broke Estate Can Leave Bills Unpaid
Suppose your father left $20,000 in medical bills but almost no estate assets. If nobody else is legally responsible, collectors generally cannot force adult children to cover the shortfall. The unpaid balance may simply remain unpaid. A collector asking for money is not proof that you owe it.
Co-Signing Changes Everything
The answer can change if you signed an agreement making yourself responsible. A co-signer generally shares liability, so the other person’s death does not necessarily erase that obligation. Check admission forms, financing agreements, and other contracts. The signature matters more than the family relationship.
Joint Debt Can Follow The Survivor
Joint debts can leave a surviving account holder responsible. A true joint borrower is different from someone who simply had permission to use an account. That distinction often matters with credit cards and other forms of credit. The underlying agreement is what counts.
An Authorized User Usually Is Not Responsible
Being an authorized user on a deceased parent’s credit card generally does not make you responsible for the balance. Authorized users can make purchases but usually have not agreed to repay the account. The Consumer Financial Protection Bureau says they generally are not liable for a deceased relative’s card debt. If a collector says otherwise, ask for proof.
Spouses Can Face Different Rules
A surviving spouse may have obligations that an adult child does not. Community-property rules can affect certain debts, depending on the state. Some states also make one spouse responsible for certain necessary expenses of the other. Medical care can fall into that category.
Community Property Can Matter After Death
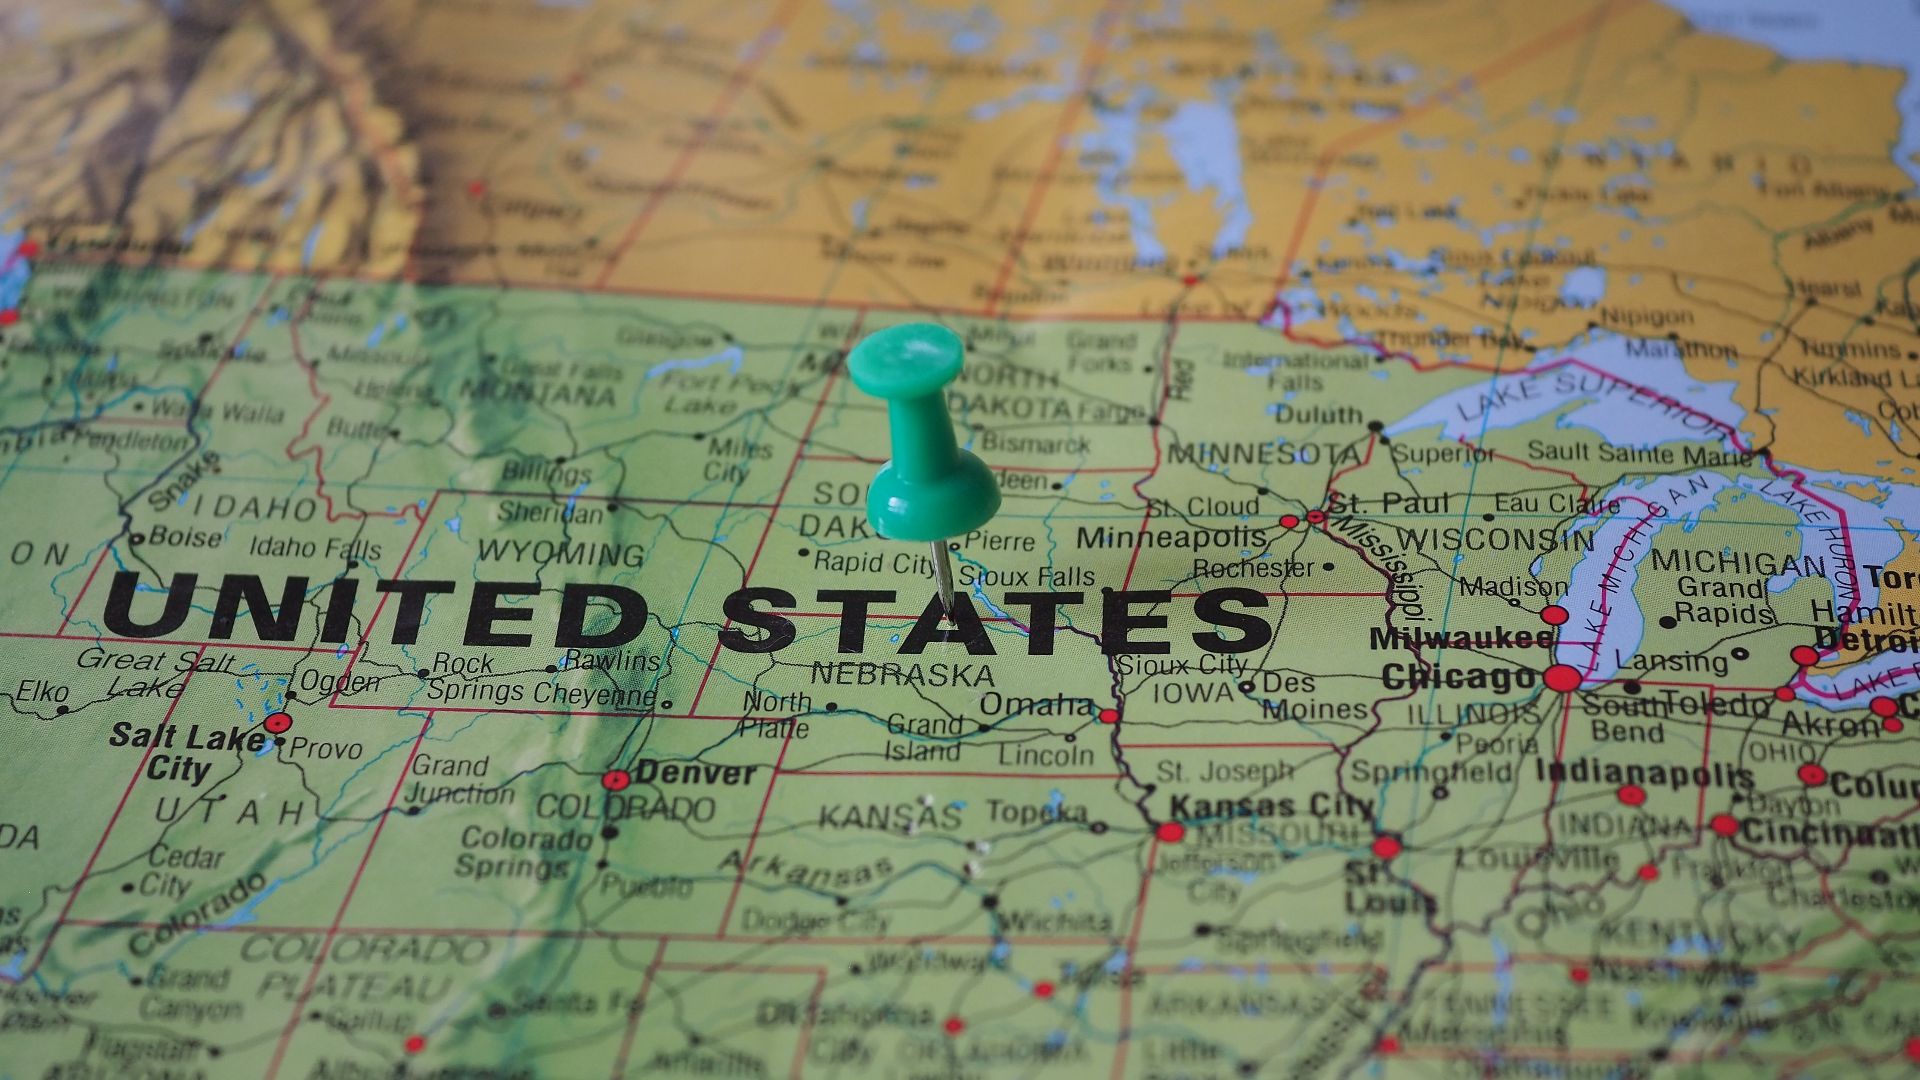
Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin are community-property states. Alaska also allows an optional arrangement in some circumstances. Certain debts incurred during marriage can affect community property or the surviving spouse. The exact result depends on the debt and state law.
Medical Bills Can Trigger Spousal Liability
Some states recognize rules covering family “necessaries.” Necessary medical treatment can fall within those rules. That means one spouse may sometimes be responsible for the other’s medical care even without signing the hospital bill. Surviving spouses should check state law before assuming they owe nothing.
Collectors Cannot Tell Every Relative Everything
Federal rules restrict who may receive details about a deceased person’s debt. Collectors can usually discuss it with a spouse, attorney, executor, administrator, or another authorized representative. They may contact another relative to locate that person, but usually cannot discuss the debt itself. Asking for the executor is not the same as proving you owe money.
Answering The Phone Does Not Make You Liable
Picking up the phone does not turn you into the debtor. Ask who is calling, which company they represent, and which account they mean. Do not hand over banking information just because the caller sounds official. Scammers can target grieving families using public information.
 ANTONI SHKRABA production, Pexels
Get The Claim In Writing
Debt collectors generally must provide validation information during the initial communication or shortly afterward. That can include the creditor, the amount claimed, and details about disputing the debt. Written documentation lets the estate compare the demand with bills, insurance records, and payments. A phone call alone is not enough.
Medical Bills Deserve A Second Look
Healthcare billing can involve hospitals, doctors, labs, insurers, and collection companies. That leaves room for old balances, duplicate charges, and insurance adjustments. The estate representative should compare the collection claim with the underlying records. The amount being demanded still needs to be verified.
You Can Dispute A Questionable Claim
Federal rules provide important dispute rights after a validation notice is received. A written dispute sent within the applicable 30-day period generally requires the collector to pause collection of the disputed amount until it provides verification. That can help when the family does not recognize the bill. Keep copies of everything.
Old Debt Is Not Automatically Dead Debt
An old medical bill is not automatically invalid because years have passed. States set statutes of limitations for lawsuits on many kinds of debt. A collector may sometimes still ask for voluntary payment after that deadline. What it cannot lawfully do is sue or threaten to sue on a time-barred debt.
A Small Payment Can Create A Big Problem
Sending a token payment just to stop the calls can be risky. In some states, a partial payment or acknowledgment can affect the statute-of-limitations period. The rules vary by jurisdiction. If the debt is old, check its legal status before sending money.
 https://kaboompics.com/, Pexels
Check Whether The Hospital Offered Assistance
Tax-exempt hospitals must maintain written financial-assistance policies for eligible emergency and medically necessary care. Those policies explain who qualifies for free or discounted treatment. They can also affect how much should be collected. If the bill came from a nonprofit hospital, check whether assistance was available.
Nonprofit Hospitals Have Collection Rules Too
Federal tax rules require nonprofit hospitals to make reasonable efforts to determine financial-assistance eligibility before certain extraordinary collection actions. Those can include lawsuits and some liens. The rules can also apply when outside collectors are involved. The original hospital’s policies are worth reviewing.
Medicaid Recovery Is A Different Issue
A Medicaid estate-recovery claim is not the same as an ordinary unpaid hospital bill. Federal law requires states to seek recovery for certain benefits paid for people age 55 or older, especially some long-term-care costs. Protections can apply for certain surviving spouses and children. States must also provide hardship-waiver procedures.
Pennsylvania Has An Unusual Exception
Pennsylvania has a broad filial-support law that can, in some circumstances, make a financially able adult child responsible for care provided to an indigent parent. Courts have applied it to substantial nursing-care bills. That does not mean every unpaid medical bill automatically passes to a child after death. Pennsylvania families should get state-specific advice.
You Can Tell A Collector To Stop Contacting You
Federal law lets people covered by debt-collection protections tell a collector to stop contacting them. The CFPB recommends making the request in writing and keeping a copy. After that, the collector generally has only limited reasons to contact the person again. The debt itself does not disappear.
Repeated Calls Are Not Unlimited
Collectors also face federal limits on repeated phone calls. CFPB rules create a presumption of a violation when a collector places more than seven calls within seven days about a particular debt, or calls again within seven days after a phone conversation about it. Exceptions can apply. Keeping a call log can help.
False Threats Cross The Line
Collectors cannot falsely tell an adult child that paying a parent’s debt is legally required when it is not. They also cannot use deceptive threats or false claims about arrest or government action. Problems can be reported to the CFPB, FTC, and state attorney general. Save letters, voicemails, dates, and names.

The Safest First Move Is Verification
The biggest mistake is assuming every call must either be ignored or immediately paid. If you are not legally responsible, direct legitimate estate matters to the executor or administrator. If you are handling the estate, get the claim in writing and verify it before paying. Your father’s medical debt usually belongs to his estate, not to you simply because you are his child.
You May Also Like:
My mother left me more because I handled her care, but my siblings say that’s unfair. Who is right?