The Pitch Sounds Great
Your friend who loves 0% financing isn't entirely wrong. It can be a smart move if you qualify: Keep your cash on hand or earning interest and pay off the full balance before the promo ends. But the fine print can turn a great-looking deal into an expensive one fast. That's why both the Federal Trade Commission and the Consumer Financial Protection Bureau tell shoppers to read the terms carefully.
 Vitaly Gariev, Pexels, Modified
What 0% Financing Really Means
A 0% financing offer usually means no interest for a limited promotional period, not forever. The offer might come from a carmaker, a retailer, or a credit card company, and the rules can vary a lot. In many cases, missing just one requirement can erase the main benefit.
The First Hidden Cost Is Opportunity Cost
Paying cash has a cost too, because that money can no longer sit in a high-yield savings account or cover other needs. If you can borrow at 0% and keep your cash earning interest, financing may look better on paper. But that only works if you avoid every fee and make every payment on time through the whole promo period.
 https://kaboompics.com/, Pexels
Car Deals Often Come With A Trade-Off
Automakers often advertise 0% APR loans, but there is often a catch. Consumer Reports notes that buyers may have to give up cash rebates or other discounts to get that low rate. The hidden cost is not always a fee. Sometimes it is the money you leave behind when you choose the promo loan.
Sometimes The Rebate Is Better Than The Zero Rate
This is where the math matters. A buyer might save more by taking a manufacturer rebate and using a regular loan than by choosing 0% financing with no rebate. Consumer Reports recommends comparing the full out-the-door cost under both options, because the flashy offer does not always lead to the cheaper deal.
Your Credit Score Decides Whether The Deal Is Real
Those big 0% ads usually aim at borrowers with very strong credit. The Consumer Financial Protection Bureau says your APR is based in part on your creditworthiness, which means not everyone gets the advertised rate. If your score does not meet the cutoff, the hidden cost may be ending up with a much higher rate than you expected.
Deferred Interest Is The Biggest Trap
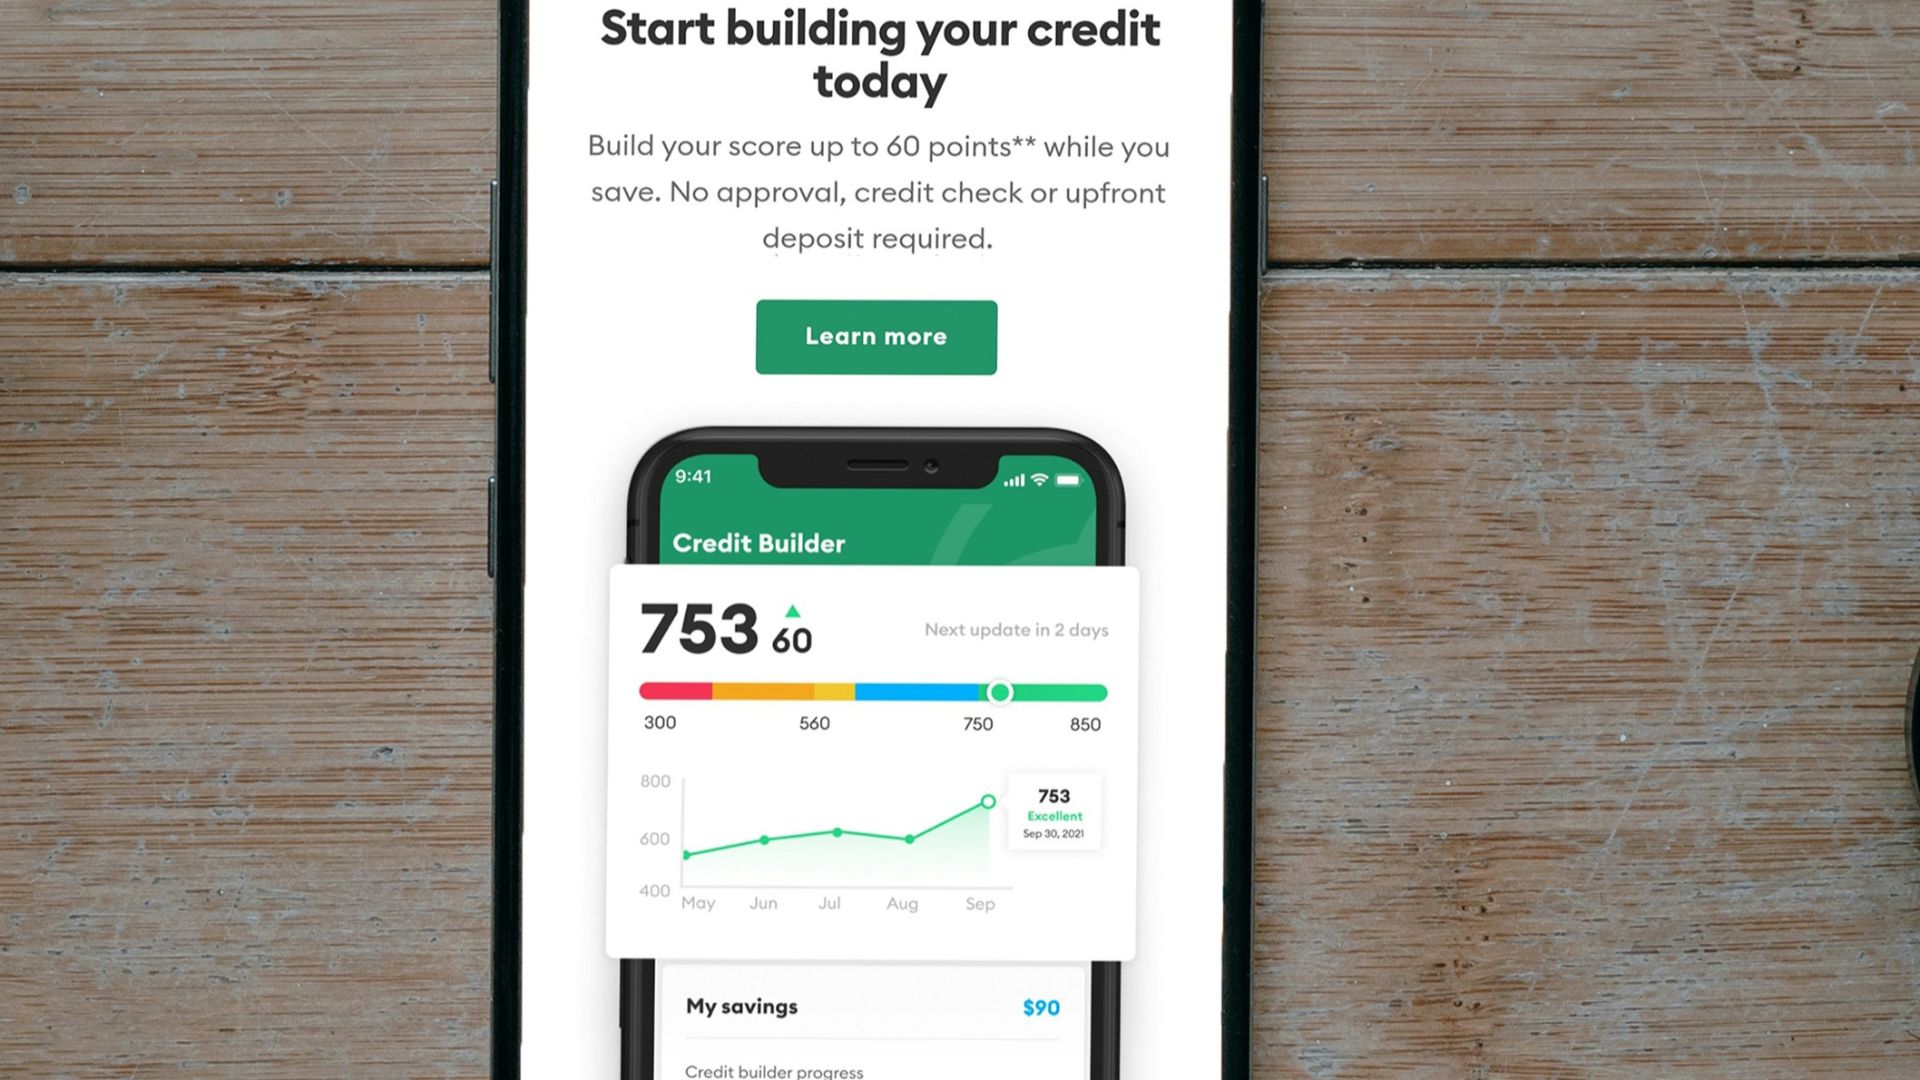
Some store promotions are not true 0% APR offers at all. The CFPB has warned about deferred interest promotions, where interest gets charged from the purchase date if the balance is not paid in full by the end of the promo period. That means even one dollar left over can trigger interest on the entire original purchase amount.
True 0% APR And Deferred Interest Are Not The Same
This difference matters more than most shoppers realize. With a true 0% APR offer, no interest builds up during the promo period. With deferred interest, the interest is there in the background the whole time, waiting to hit your account if you miss the payoff deadline.
The CFPB Has Warned About This For Years
The Consumer Financial Protection Bureau has repeatedly told consumers to figure out whether interest is actually waived or just delayed. That one detail can decide whether a deal saves you money or sets you up for a big retroactive charge later.
 Tony Webster, Wikimedia Commons
One Late Payment Can Blow Up The Deal
Promotional financing often requires every payment to arrive on time. The CFPB says issuers may revoke a promotional APR if you pay late, depending on the terms. One missed due date can mean fees, penalty rates, or the loss of the special financing altogether.
Late Fees Can Add To The Damage
Even if the lender does not cancel the promo right away, late fees can still pile up. Credit card late fees are regulated, but they still cost money, and they can hurt your credit if the delinquency is reported. That is another hidden cost people miss when they focus only on the 0% headline.
Minimum Payments Can Fool You
Minimum payments are often too small to wipe out a balance before the promotional period ends. The CFPB has specifically warned consumers using deferred interest promotions to calculate the payment needed to clear the full balance by the deadline. If you just make the minimum, you may drift straight into a costly interest charge.
Promo Expiration Dates Matter A Lot
A 12-month or 18-month offer can sound generous until life gets in the way. A job change, medical bill, or plain old budgeting mistake can leave part of the balance unpaid when the clock runs out. The hidden cost is that the deal only works if your payoff plan is realistic from the start.
Balance Transfer Fees Can Wipe Out The Benefit
On the credit card side, 0% balance transfer offers often charge an upfront fee. According to the CFPB, transfer fees are commonly a percentage of the amount moved, which means the financing is not truly free. If the fee is 3% to 5%, you need to compare that cost with the interest you would have paid otherwise.
New Purchase Offers Can Have Fees Too
Some financing promotions come with annual fees, account-opening terms, or add-on charges that eat into the savings. The Federal Trade Commission advises shoppers to check every charge in the agreement, not just the APR. A zero interest rate does not cancel out every other way borrowing can cost you.
Cash Buyers Sometimes Have More Leverage
In some deals, especially outside the more standardized auto financing world, cash can simplify the transaction and help you negotiate. Sellers may be more flexible when they know there is no lender approval, delayed funding, or financing paperwork. The hidden cost of financing can be losing bargaining power on the final price.
But Cash Is Not Always King
That old saying does not always hold up. Some dealerships make more money from financing and may be less eager to cut a deal for a cash buyer. That is why it makes sense to negotiate the vehicle price first, then compare the financing package, rebate options, and cash alternative separately.
Longer Loans Can Quietly Raise The Risk
A 0% APR over a longer term can make the monthly payment look harmless. The problem is that long loans can keep you tied to a depreciating asset for years, especially with cars. The CFPB has warned that longer auto loans can raise the chance that you owe more than the vehicle is worth for part of the loan term.
Being Underwater Has A Cost Of Its Own
If your car is totaled or you need to sell it early, an upside-down loan can become a real problem. Even with a 0% rate, negative equity can force you to bring cash to the table or roll debt into your next vehicle. That is a hidden cost that has nothing to do with interest, but it can hit a household budget hard.
 Brian Teutsch, Wikimedia Commons
Keeping The Cash Takes Discipline
The case for financing only works if the cash you did not spend stays available. If you finance at 0% and then burn through the cash on vacations, impulse buys, or everyday overspending, the strategy falls apart. What looked smart on paper turns into debt with no backup cushion.
 https://kaboompics.com/, Pexels
Inflation Can Help, But Not By Much
In theory, paying back a fixed 0% loan with future dollars can work in your favor when prices and wages rise. But inflation is not a free pass for bad planning. It only helps if the purchase price is competitive and the loan terms do not include hidden penalties or lost discounts.
 Andrii Yalanskyi, Shutterstock
Retail Financing Deserves Extra Skepticism
Big-ticket furniture, electronics, and medical financing offers are common places for deferred interest deals. The FTC has long advised consumers to look past phrases like no interest if paid in full and ask what happens if the balance is not cleared in time. Those few words can hide the most expensive part of the deal.
Medical And Dental Promotions Need A Hard Look
Healthcare financing can be especially tricky because people often agree while stressed or rushed. The CFPB has reported on medical credit products and warned that promotional financing can expose patients to deferred interest and other costs they did not fully expect. If a provider offers financing at the front desk, slow down and read everything before signing.
Read The Truth In Lending Disclosures
This is where the boring paperwork becomes your best defense. Federal lending disclosures are meant to show the APR, fees, payment schedule, and other key terms in writing. If the salesperson's summary sounds better than the disclosure form, trust the document.
Run The Numbers Two Ways
Before you choose 0% financing, compare the total cost under at least two scenarios. First, calculate the financed option with every fee and any lost rebate. Second, calculate the cash option, including what your money could earn if you kept it instead of spending it.
Set Autopay And A Personal Deadline
If you take the promotional deal, automate more than the minimum payment when possible. Set a payoff target that clears the balance one or two billing cycles before the promo expires. That extra cushion can protect you from processing delays, statement timing issues, and plain old human error.
So Is 0% Financing Always Better Than Cash
No. It can be better, but only if the promotional rate is real, the purchase price is competitive, no better rebate is being sacrificed, fees are low or nonexistent, and you have a solid plan to pay on time and in full. The hidden costs to watch for are deferred interest, lost discounts, fees, long loan terms, late-payment penalties, and the temptation to spend the cash you meant to keep.