ConsumerRights

I bought a brand-new car I couldn’t afford just to impress my hyper-competitive coworkers. Now it’s been repossessed. Can I fix my credit?


February 19, 2026 | Marlon Wright

I bought a brand-new car I couldn’t afford just to impress my hyper-competitive coworkers. Now it’s been repossessed. Can I fix my credit?


CreditRecoveryAntoni Shkraba Studio, Pexels, Modified

Buying a car to impress people who barely think about you is expensive. However, losing that car to repossession is even more expensive as the bill keeps coming long after the tow truck leaves. If you're reading this with an empty parking space and a sinking feeling in your gut, you already know the damage is done. A repossession is a serious financial wound that shows up on your credit report for seven years and tanks your score by 100–150 points almost immediately. But can you actually recover from this? Yes. Will it be quick or easy? Absolutely not. Thousands of people dig themselves out of repo situations every year, rebuilding their credit from the ground up. The path forward requires honesty about what went wrong, strategic action to minimize the damage, and patience while your credit slowly heals. 

The Brutal Reality Of Repossession Damage

A vehicle repossession doesn't just disappear from your credit report with an apology. It stays there for seven years from the date of your first missed payment, acting like a financial scarlet letter that screams "risky borrower" to anyone who pulls your report. Your credit score likely dropped between 100 and 150 points the moment that tow truck drove away, and that's before factoring in the late payments that led up to the repo. Lenders see repossession as one of the most serious negative marks possible because it shows you couldn't maintain payments on a secured debt—something they consider worse than missing credit card payments. The damage compounds because the lender will likely sell your car at auction for less than you owed, leaving you with a deficiency balance that could haunt you for years.

The financial consequences extend beyond just your credit score. That deficiency balance, the difference between what you owed and what the car sold for at auction, becomes a debt the lender can pursue through collections or lawsuits. Many people don't realize they still owe money even after losing the car. If you owed $25,000 and the car sold for $15,000 at auction, you're still on the hook for $10,000 plus repo fees, storage costs, and auction expenses. This debt will appear as a separate collection account on your credit report, creating a second negative mark that further tanks your score. 
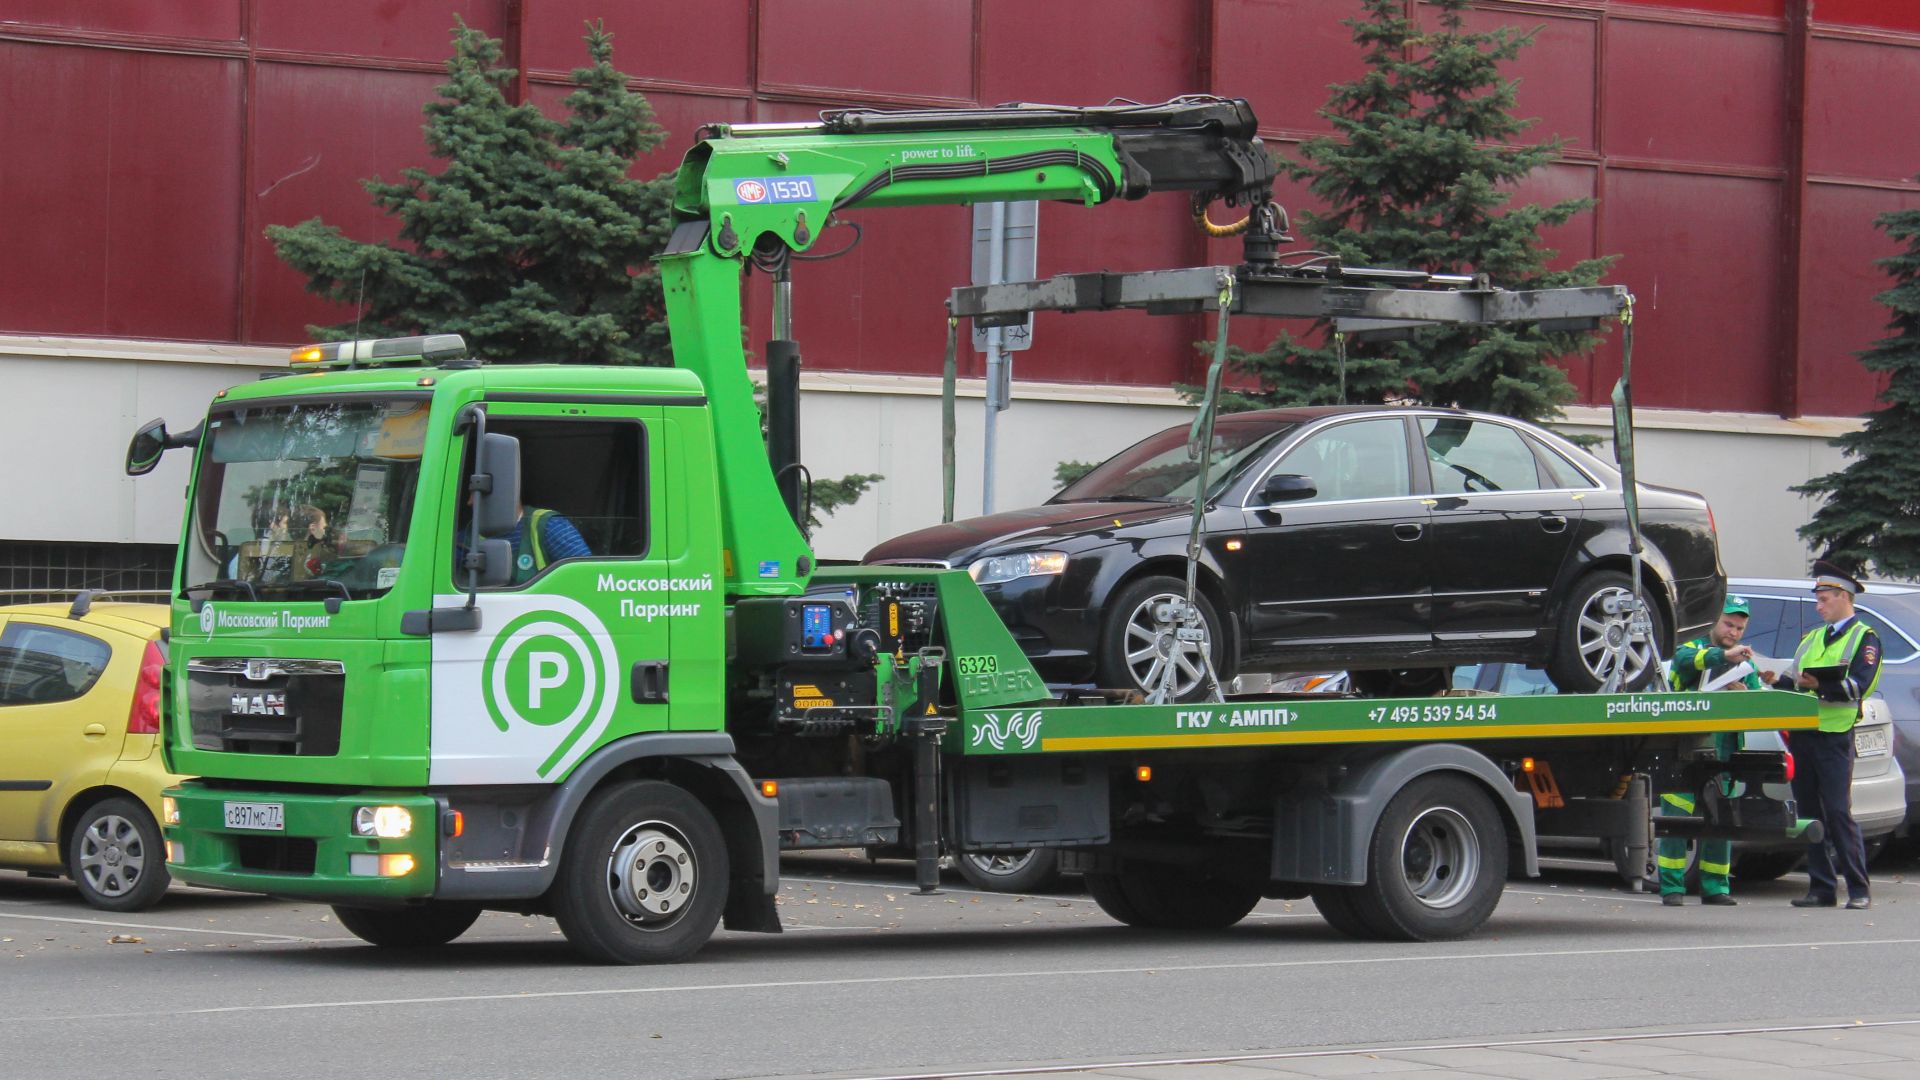
File:Tow truck in Moscow 01.jpgStolbovsky, Wikimedia Commons

Advertisement

Your Step-By-Step Recovery Strategy

Start by getting copies of your credit reports from all three bureaus—Equifax, Experian, and TransUnion—through AnnualCreditReport.com. Examine every detail of how the repossession is reported. Lenders must follow strict legal procedures during repossession, and if they violate your state's laws or report inaccurate information, you have grounds to dispute the entry. Document everything: dates of missed payments, communications with the lender, and the timeline of the repossession itself. If the lender failed to provide proper notice, sold the car without informing you, or didn't conduct a commercially reasonable sale, you might be able to challenge the deficiency amount or even the repossession's credit reporting. Consider consulting with a consumer rights attorney who specializes in Fair Debt Collection Practices Act and Fair Credit Reporting Act cases.

The most important action you can take right now is negotiating with your lender before the debt goes to collections. Contact them immediately and try to arrange a settlement on the deficiency balance. Many lenders would rather accept 40–60% of what you owe as a lump sum than chase you through collections for years. Get any agreement in writing before sending money, and insist on "pay for delete" language if possible, though most major lenders won't agree to remove accurate reporting. If you can't settle, set up a payment plan you can actually afford. Even small monthly payments show future creditors you're taking responsibility. Simultaneously, start rebuilding your credit by opening a secured credit card with a small limit, becoming an authorized user on someone else's good account, or taking out a credit-builder loan through a credit union. These positive payment histories won't erase the repo, but they'll gradually dilute its impact as your report fills with on-time payments. 
Your Step-By-Step Recovery StrategyMikhail Nilov, Pexels

Advertisement

READ MORE

Internal - Paying Cash For House

My dad says I should always pay cash for houses. But my financial advisor says I need to get a credit card to apply for a mortgage. Who's right?

My dad says to always pay cash for a house, but my advisor says I need a credit card to get a mortgage. Here’s who’s right, how credit really works, and what future homebuyers should do.
April 1, 2026 Jack Hawkins
Rss Thumb - Family Dispute Inheritance

My sister says she deserves more inheritance because she visited our parents more, but I paid their bills. How do families measure fairness?

My sister says she deserves more inheritance because she visited our parents more, while I paid their bills. Learn how families can evaluate caregiving, financial contributions, estate documents, reimbursements, and fairness without turning an inheritance dispute into a permanent family feud.
September 1, 2026 Jack Hawkins
AI-generated image of a couple that retired at different times.

My spouse and I retired at different times, and planning became way more difficult than expected. Is it always so complicated?

Many couples spend years planning for retirement, imagining the day they'll finally leave work behind together. Then reality arrives, and one spouse retires while the other keeps working for several more years.
July 1, 2026 Quinn Mercer
Internal - Power Bill Hack

Our power company was hacked and they delayed billing by 3 months to fix it. Now, my bill is over $1,000. Are they just guessing how much I owe?

Power bill delayed after a utility hack? Learn whether your electric company is estimating what you owe, how to read a catch-up bill, and what to do if a surprise $1,000 charge lands in your mailbox.
April 1, 2026 Jack Hawkins
Millionaire's Row Historic District, Williamsport, PA, April 2011

Detroit's Millionaire's Row shined like a diamond until it crumbled when the Great Depression decimated auto production.

There lies a Detroit neighborhood where wealthy families once strolled tree-lined streets past sophisticated Victorian homes. Today, you’ll only find scattered buildings that hint at a lost world of prosperity.
September 1, 2026 Alex Summers
Woman worried gold recession

My cousin says buying gold is the only way to protect your money right now. The economy has me worried, does he have a point?

When markets feel shaky, gold suddenly starts sounding like the answer to everything. It has a long history, it feels tangible, and it tends to get attention whenever inflation, recessions, or geopolitical stress are in the news. That’s probably why your friend is so confident about it right now. But “the only way” to protect your money is a much bigger claim than the evidence supports.
April 1, 2026 Miles Brucker


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team