Money gone fast.

I tried to save money by doing my own taxes. Now the IRS says I owe $14,000. That would ruin me, am I completely doomed?


February 19, 2026 | Marlon Wright

I tried to save money by doing my own taxes. Now the IRS says I owe $14,000. That would ruin me, am I completely doomed?


Owe IRS much.olia danilevich, Pexels, Modified

That sinking feeling when you open an envelope from the IRS and see a five-figure number staring back at you is genuinely stomach-churning. You thought you were being smart and thrifty by filing your own taxes, maybe using some free software or just winging it with the forms. Fast forward a few months, and suddenly you're facing a $14,000 bill that feels like it appeared out of nowhere. Your mind races through worst-case scenarios: wage garnishment, property seizure, maybe even jail time. But here's the thing about IRS debt that most people don't realize until they're knee-deep in it. You're probably not so doomed as you think you are, and that terrifying number isn't necessarily set in stone. 

Why Your Tax Bill Exploded

The most common reason DIY tax filers end up with massive bills is misunderstanding deductions and credits, especially if you're self-employed or have side income. When you work for yourself, you're responsible for both the employee and employer portions of Social Security and Medicare taxes, which is about 15.3% of your net earnings right off the bat. Many first-time freelancers or gig workers don't realize they should be making quarterly estimated tax payments throughout the year. They just see the gross income rolling in. Miss those quarterly payments, and you'll face underpayment penalties on top of the actual tax owed. Another huge mistake is claiming deductions you don't qualify for or inflating business expenses beyond what's legitimate. 

The IRS computers are incredibly good at catching discrepancies between what you report and what your employers, banks, and investment companies report about you. If you forgot to include income from a 1099 form or miscalculated your self-employment tax, their system flags it automatically. Sometimes the error isn't even yours. Maybe you got bad advice from a well-meaning friend or relied on outdated information from internet forums. Perhaps the tax software you used had a glitch, or you accidentally skipped a critical question that would have changed your entire return. The IRS doesn't particularly care how the mistake happened. They just see that you owe money based on the actual numbers versus what you filed. But understanding where things went wrong is your first step toward fixing the situation, because some errors are more negotiable than others when it comes to penalties and interest.
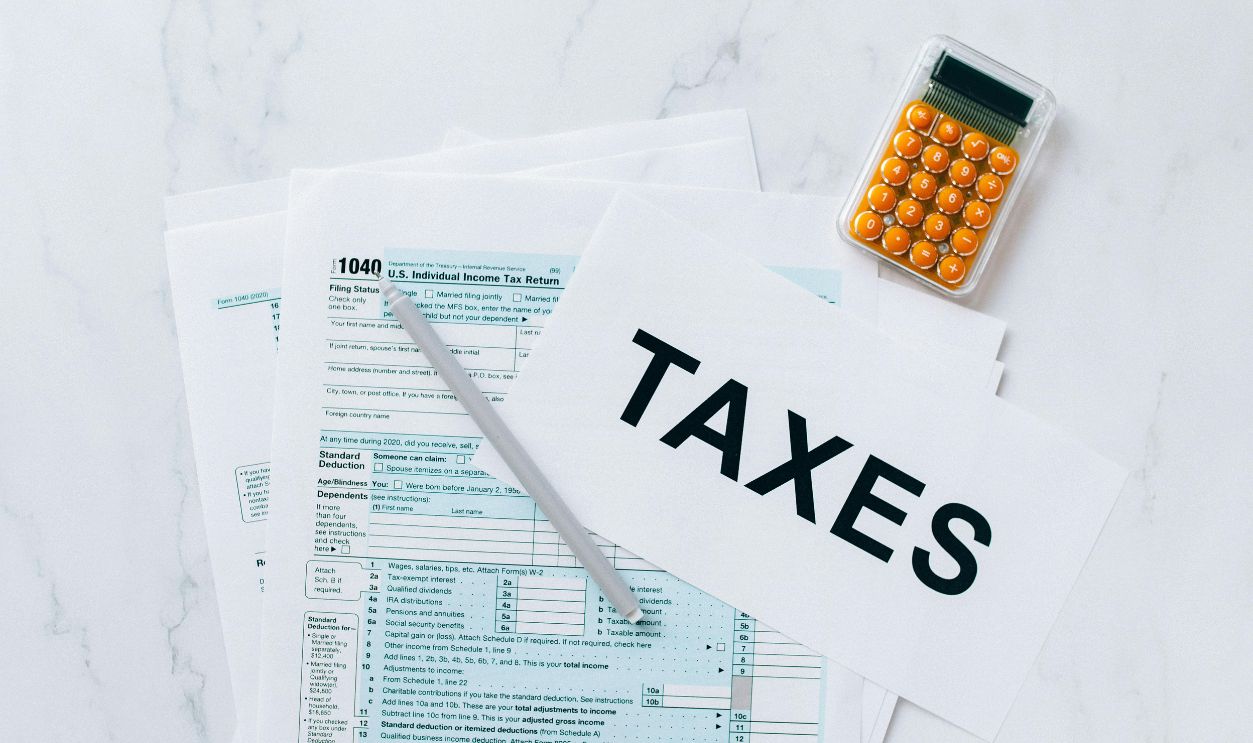
Why Your Tax Bill ExplodedNataliya Vaitkevich, Pexels

Advertisement

You Have More Options Than You Think

Before you start imagining IRS agents showing up at your door, understand that the agency would much rather work with you than against you. Their goal is to collect what's owed, not ruin your life. The first thing you should do is not ignore that notice. Seriously, the worst thing you can do is pretend it doesn't exist and hope it goes away. It won't, and ignoring it only adds more penalties and interest to your balance. Instead, verify that the IRS calculation is actually correct by reviewing your return against their notice. Sometimes they make mistakes too, or they're missing information you can provide to reduce the bill. If their number is right and you genuinely owe the money, you have several paths forward that don't involve paying $14,000 immediately.

An installment agreement lets you pay off your debt in monthly chunks, and the IRS approves most requests for amounts under $50,000 if you're current on filing all your returns. You can set this up online in about fifteen minutes, and as long as you make your payments on time, they won't take any collection action against you. If your financial situation is truly dire, you might qualify for an Offer in Compromise, where the IRS accepts less than the full amount owed. This isn't easy to get approved, but it's possible if you can demonstrate that paying the full debt would create genuine financial hardship. There's also the Currently Not Collectible status, which temporarily pauses collection efforts if you can prove you can't afford both basic living expenses and your tax debt. The penalties and interest keep accruing, but at least you're not facing immediate collection action while you get back on your feet.
You Have More Options Than You Think Vanessa Garcia, Pexels

Advertisement

READ MORE

Propvalue-Int

Upgrades You Should Implement To Increase Your Property Value

The housing market is competitive, to say the least. If you want your home to stand out on the market, here are some things you can do to make it seem brand new.
April 15, 2025 Ethan Vestby
Last Will

Things You Need In Your Will That Too Many People Forget

Think your will is complete? Even the most carefully crafted ones often miss necessary elements that could leave your family in limbo. If you want it to be a peaceful ride, continue reading.
January 13, 2026 Miles Brucker
Fb Og Image - Career Changes

Simple Career Changes To Make More Money In 2025

If you're looking to change tracks in 2025 and jump into a new career but aren't looking to go back to school or spend time and money retraining in an entirely new profession, here are some career changes you can make to make more money next year.
January 1, 2025 Jack Hawkins
Husbandgamblinginternal

My husband hid over $100K in gambling debts while I thought he had the money invested. At 55, our retirement is off-track. What happens next?

It can be devastating to discover hidden debt if you're in your 50s, but there are steps you can take to protect your future and your retirement.
October 29, 2025 Sammy Tran
Laidoff50Internal

Laid Off In Your 50s: Strategies For Moving Forward

Losing your job is bad enough, but being laid off in your 50s hits especially hard. We look at strategies for getting back on track.
October 30, 2025 Alex Summers
Leasemileage-Simple

My Lease Is Ending And I’m Over The Mileage Limit. Should I Buy It Out Or Turn It In?

You’re cruising toward the end of your lease, feeling pretty good… until you check the odometer and your contract. You’re thousands of miles over the limit, and those little extra miles are about to cost real money. Do you pay the mileage fees and turn it in, or buy out the car and keep it? The good news is that you actually have more control here than it feels like.
December 4, 2025 Peter Kinney


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕