When Your Parents' Retirement Becomes Your Problem
Your parents worked for decades, but now retirement is approaching and their savings are alarmingly small. Instead of discussing how they plan to manage, they seem to assume you will cover whatever they cannot afford. You love them, but you also have bills, financial goals, and a future to protect. So where does your responsibility actually begin, and where should it end?
Loving Your Parents Doesn't Mean Funding Everything
Supporting aging parents can be an expression of love, but financial assistance should not automatically mean unlimited payments. The Consumer Financial Protection Bureau encourages families to discuss financial arrangements openly and plan for changing needs. Before agreeing to anything, separate what your parents genuinely need from what they expect you to provide. Those two things may be very different.
The Law Might Surprise You
In the United States, adult children are not automatically responsible for every unpaid expense their parents accumulate. However, some states have filial responsibility laws that can create support obligations under particular circumstances. The rules, exceptions, and enforcement practices depend on where the family lives. Before assuming you have no legal responsibility, check the laws in the relevant state.
Your Parents' Financial Choices Still Matter
There is an important difference between parents who struggled financially despite careful planning and those who repeatedly spent beyond their means. Either situation can produce genuine hardship, but understanding the cause helps determine whether financial assistance will actually solve the problem. If overspending continues, additional money may only postpone another crisis. A realistic support plan must address both income and spending.
Start With An Uncomfortable Money Conversation
Before promising financial assistance, ask your parents to explain their complete financial situation. The CFPB recommends discussing financial matters early, particularly when aging could eventually affect someone's ability to manage money. Request information about monthly income, savings, debts, housing costs, insurance, and expected retirement dates. Without those details, you cannot accurately estimate how much help they need.
Find Out What They Actually Have
A small retirement account does not necessarily mean your parents have no financial resources. They may have Social Security benefits, pensions, home equity, savings accounts, or other assets that affect their options. Ask them to prepare a complete list of assets and liabilities, including outstanding mortgages and credit card balances. This gives everyone a clearer starting point than simply saying retirement savings are almost gone.
Social Security Could Cover Part Of The Gap
For eligible American retirees, Social Security provides monthly benefits based on their earnings records and claiming circumstances. The Social Security Administration allows workers to review retirement benefit estimates through their personal online accounts. Ask each parent to check their expected payment rather than relying on a guess. Those figures should become part of the household's retirement budget before you calculate any contribution of your own.
Don't Overlook Spousal Benefits
A parent with limited employment history may still qualify for Social Security benefits through a spouse's work record. According to the Social Security Administration, eligible spouses can receive benefits worth up to half the worker's full-retirement-age benefit, although claiming early can reduce payments. Some divorced spouses may also qualify if their marriages lasted at least ten years and other requirements are met. Checking these options could reveal income your parents have overlooked.
Low Savings May Open The Door To Additional Help
Supplemental Security Income, or SSI, provides assistance to eligible people with limited income and resources who are at least 65, blind, or have qualifying disabilities. Eligibility also depends on citizenship or qualifying immigration status, residency, and other rules. Parents who qualify may receive assistance even when their retirement savings are extremely limited. Encourage them to check eligibility directly with the Social Security Administration instead of assuming they will be rejected.
Retirement Doesn't Always Mean Stopping Work Completely
If your parents are healthy enough and willing, part-time employment may help close a retirement income gap. Even a modest paycheck could reduce the amount they need from relatives each month. They should examine how additional earnings could affect Social Security payments, SSI eligibility, taxes, and other assistance. Working longer is not realistic for everyone, but it deserves consideration before the family commits to permanent financial support.
Their Monthly Budget Needs A Reality Check
Once income is established, compare it against essential expenses such as housing, groceries, utilities, transportation, and medical care. Separate unavoidable bills from discretionary purchases, subscriptions, and spending that could be reduced. If monthly expenses exceed reliable income, the difference reveals the immediate shortfall. That number is much more useful than an open-ended request for financial help.
Housing Could Be Their Biggest Decision
If your parents own a home, its ongoing costs may consume a substantial portion of their retirement income. Mortgage payments, property taxes, insurance, maintenance, and utilities all belong in the calculation. Downsizing, relocating, or exploring suitable housing assistance could reduce pressure on the family budget. Selling a home is a major decision, however, so compare the full costs and consequences before treating it as an easy solution.
Don't Assume Medicare Pays For Everything
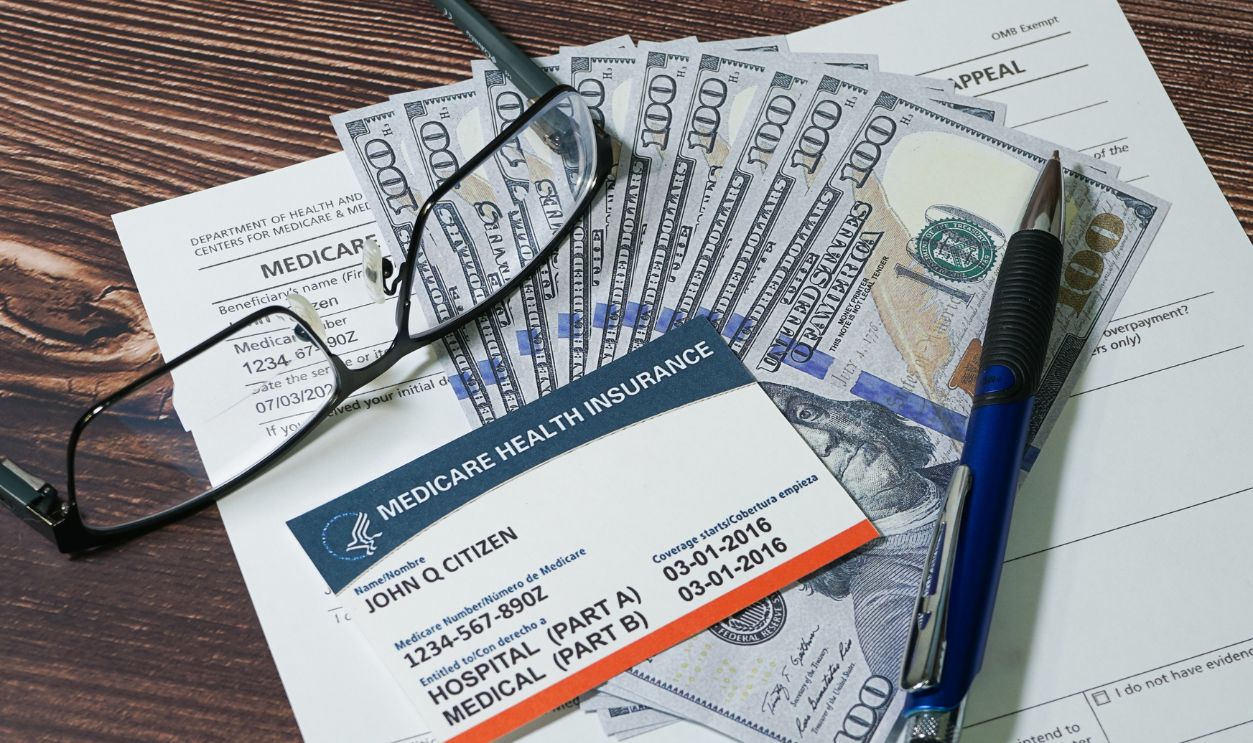
Medicare covers many healthcare services, but it does not eliminate every medical expense. Original Medicare generally excludes routine dental care, hearing aids, and certain vision services, subject to specific exceptions. Your parents may also face premiums, deductibles, copayments, and expenses for services that are not covered. Their retirement budget needs a realistic healthcare category rather than an assumption that insurance will handle everything.
Long-Term Care Changes The Financial Equation
One of the biggest potential expenses is assistance with everyday activities such as bathing, dressing, or moving around safely. Medicare generally does not pay for ongoing custodial long-term care, whether provided at home or in a nursing facility. Medicaid may cover certain long-term services for people who satisfy their state's eligibility requirements. Understanding these differences before a health crisis can prevent rushed and expensive family decisions.
Government Programs Could Reduce The Pressure
Before using your own savings, investigate programs designed to help older Americans with limited resources. Medicare Savings Programs can help eligible beneficiaries pay certain Medicare premiums and other covered costs, depending on the program. Medicare's Extra Help program can also reduce prescription drug expenses for qualifying individuals. These benefits could free up money for groceries, housing, and other necessities without requiring a larger contribution from you.
 Rix Pix Photography, Shutterstock
Decide What You Can Actually Afford
Your parents' financial shortfall should not automatically determine how much money you contribute. Start with your own essential expenses, outstanding debts, emergency savings, and retirement contributions. Calculate an amount you could provide without sacrificing those priorities or relying on credit cards. If that amount is zero, you can still help them research benefits, organize bills, or find affordable services.
 https://kaboompics.com/, Pexels
Your Own Retirement Cannot Be An Afterthought
Using retirement savings to cover your parents' expenses could leave you facing a similar problem later in life. Consider how years of monthly assistance would affect your investment contributions and long-term financial security. For example, contributing $400 every month means giving away $4,800 annually before accounting for any potential investment growth. Helping one generation should not require leaving the next generation financially vulnerable.
Set A Specific Limit Instead Of Making An Open-Ended Promise
If you decide to contribute, establish a clear monthly amount and explain exactly what it covers. You might offer to pay one utility bill or contribute a fixed amount toward groceries rather than covering every unexpected expense. Agree on when the arrangement will be reviewed and what circumstances would require another discussion. A defined commitment makes it easier to help consistently without creating an obligation you cannot sustain.
Be Careful About Putting Their Debts In Your Name
There is a major difference between voluntarily helping with a payment and becoming legally responsible for a loan. The CFPB warns that co-signers can be required to repay the full outstanding debt when the primary borrower fails to pay. Missed payments may also damage the co-signer's credit history and expose them to collection activity. Think carefully before co-signing a mortgage, personal loan, or other debt to solve your parents' immediate cash shortage.

Nursing Home Paperwork Deserves Extra Attention
If your parents eventually require residential care, you may be asked to help complete admission documents. Federal rules prohibit Medicare- and Medicaid-participating nursing facilities from requiring a third party to personally guarantee payment as a condition of admission or continued residence. The CFPB has documented disputes involving agreements that attempted to impose personal liability on relatives. Review paperwork carefully and seek legal advice before signing anything that appears to make you responsible for care costs.
You Don't Have To Manage Their Money Yourself
Helping your parents organize finances does not necessarily require taking control of their bank accounts. The CFPB explains that relatives can provide informal budgeting and bill-paying assistance while the account holder retains authority over transactions. Other arrangements, including powers of attorney, carry different responsibilities and should be understood before use. Begin with the least complicated arrangement that provides the help your parents actually need.
Watch For Financial Problems Beyond Poor Planning
Sometimes a sudden financial shortfall reflects more than inadequate retirement savings. The CFPB identifies unexplained withdrawals, missing funds, unusual gifts, and sudden changes in spending as potential warning signs of financial exploitation. If your parents cannot explain where their money went, investigate carefully rather than immediately replacing the missing funds. Identifying fraud or financial abuse early may prevent additional losses.
Having Siblings Should Change The Conversation
If you have brothers or sisters, avoid assuming that one person must provide all the financial assistance. Organize a family discussion about your parents' needs and what each person can reasonably contribute. One sibling might provide transportation, another could handle paperwork, and another might contribute toward essential bills. A fair arrangement does not necessarily require identical contributions, but it should make expectations clear.
Moving Them Into Your Home Isn't Automatically Cheaper
Inviting your parents to live with you may appear to eliminate their housing expenses, but it can introduce costs and responsibilities of its own. Consider groceries, utilities, home modifications, transportation, privacy, and possible changes to your working arrangements. Discuss whether they will contribute toward household expenses and how long the arrangement is expected to last. Treat shared housing as a significant financial decision rather than an emergency solution that requires no planning.
Financial Support May Come With Tax Considerations
The IRS allows taxpayers to claim certain qualifying relatives, including eligible parents, as dependents when specific requirements are satisfied. These rules involve income limits, support tests, and other conditions, so simply paying a parent's bills does not guarantee a tax benefit. Some taxpayers may also qualify for the Credit for Other Dependents or certain dependent care benefits. Keep records of your contributions and consult a qualified tax professional before claiming anything.
Sometimes Professional Advice Is Worth The Cost
A financial planner familiar with retirement income can help your parents evaluate spending, available assets, and sustainable income options. An elder-law attorney may be useful when questions involve Medicaid eligibility, support obligations, or complicated family arrangements. If your parents are struggling with basic financial management, local aging-services organizations may also provide guidance. Getting qualified advice before committing substantial money can be less expensive than trying to correct a poorly structured arrangement later.
You Can Say No Without Abandoning Them
Refusing an unlimited financial commitment does not mean refusing every form of assistance. You can help your parents apply for benefits, compare housing options, review expenses, and locate appropriate community services. The CFPB points families toward local Area Agencies on Aging and the Eldercare Locator for assistance with financial management resources. Practical help can be meaningful even when direct financial support is not possible.
The Answer Depends On Your Limits, Not Just Their Needs
Your parents' lack of retirement savings is a serious problem, but it does not automatically make you responsible for funding the rest of their lives. Any legal obligation depends on applicable law, while your personal decision should account for your finances, family circumstances, and willingness to help. Start by establishing what resources they have, what assistance they qualify for, and what contribution you can realistically sustain. The goal is to help your parents find stability without creating a second retirement crisis for yourself.
You May Also Like:
Everyday Fees That Make A “Cheap” Purchase Much More Expensive
The Budget Categories Families Underestimate—Until They Suddenly Blow Up