You're Facing A Financial Nightmare
You've just lost your wife after five weeks in the hospital, and now you're facing another frightening possibility: enormous medical bills. You don't know what insurance covered, what the hospital might demand, or whether your savings and home could be at risk. What happens next?
The Answer Might Surprise You
Here's the reassuring part: being married doesn't automatically make you responsible for every medical bill your spouse leaves behind. Generally, unpaid debts belong to the deceased person's estate. However, state laws, shared financial obligations, and certain agreements can change that answer considerably.
Understand What An Estate Is
Your wife's estate generally consists of the property and financial assets she owned when she died. Depending on state law, valid outstanding medical bills may be paid from those assets before heirs receive their inheritance. That doesn't necessarily mean creditors can take your personal savings.
Marriage Doesn't Guarantee Liability
In most circumstances, you don't become personally liable for a deceased spouse's debts simply because you were married. However, the Consumer Financial Protection Bureau warns that exceptions exist for shared obligations and certain state laws. Before paying anything, establish whether you actually owe it.
Your State Makes A Difference
The laws of the state where you live can dramatically affect your obligations. Some states treat certain marital debts as shared, while others have special rules concerning necessary expenses. A surviving spouse in California may face different legal responsibilities than someone living in Florida.
Community Property Changes Things
In community property states, certain debts incurred during marriage can be satisfied from marital property, even when only one spouse received treatment. Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin follow community property systems, with important differences between them. Alaska offers an elective arrangement.
Medical Care Counts As Necessary
Some states recognize what's called the doctrine of necessaries, which can make one spouse responsible for certain essential expenses incurred by the other. Hospital treatment may qualify. However, the doctrine's application varies considerably, and some states have abolished or restricted it.
Did You Sign Anything?
Think back to your wife's hospital admission. Did you sign paperwork identifying yourself as a financial guarantor, rather than merely acknowledging treatment or providing emergency contact information? Those distinctions matter. A genuine payment agreement may create obligations, but your signature alone doesn't automatically establish liability.
Request The Hospital Paperwork
Ask the hospital for copies of admission agreements, financial responsibility forms, and any documents bearing your signature. Review them carefully before agreeing to pay. If you're unsure what you signed, an attorney can determine whether the agreement creates an enforceable obligation under your state's laws.
 Media Whale Stock, Shutterstock
Insurance Comes Into Play
Before worrying about a $150,000 hospital statement, determine what insurance was in effect when your wife received treatment. Private insurance, Medicare, or Medicaid may cover substantial portions of eligible expenses. A hospital's initial charges are not necessarily the amount ultimately owed after insurance processes the claims.
Suppose She Had Private Insurance
Imagine your wife's hospital charged $180,000 for five weeks of care. Her insurance might negotiate those charges down substantially and pay much of the allowed amount. Your actual financial exposure could be limited by deductibles, coinsurance, and applicable out-of-pocket maximums, subject to coverage rules.
Check The Out-Of-Pocket Maximum
Most qualifying private health plans have annual limits on covered, in-network cost-sharing. Once your wife reached her applicable limit, additional covered in-network services generally wouldn't generate more cost-sharing that year. However, premiums, noncovered services, and certain out-of-network expenses may fall outside those protections.
What If She Had Medicare?
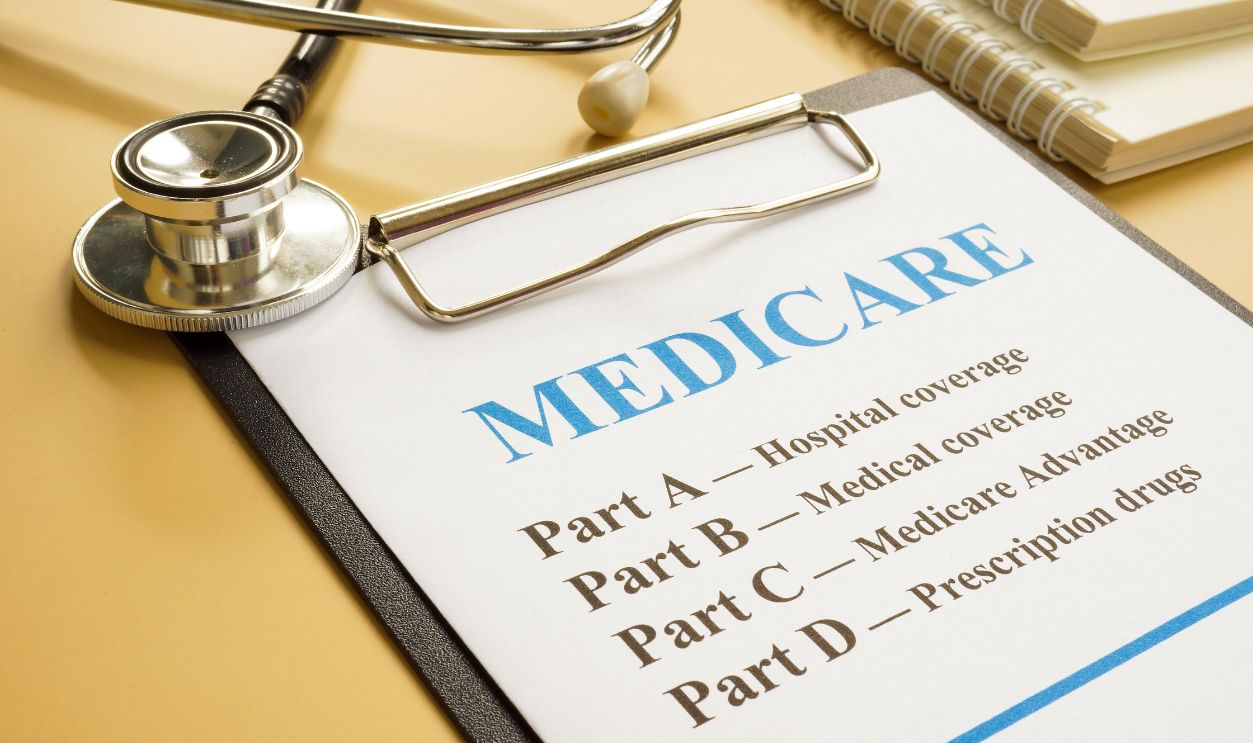
If your wife had Original Medicare, inpatient hospital care generally falls under Part A, with applicable deductibles and benefit-period rules. Extended hospitalizations can involve daily coinsurance. Medigap or other supplemental coverage may reduce those costs, so review every policy before estimating what remains unpaid.
 Vitalii Vodolazskyi, Shutterstock
Medicare Advantage Works Differently
If she had Medicare Advantage instead, the plan's hospital copayments, coinsurance, network rules, and annual out-of-pocket limit become especially important. Five weeks of hospitalization could generate significant cost-sharing, but covered Part A and Part B services are subject to the plan's applicable annual maximum.
Medicaid Has Special Rules
If your wife received Medicaid, covered hospital services generally involve limited patient cost-sharing. Medicaid also has estate recovery rules for certain benefits, particularly long-term care. Importantly, federal law generally prohibits estate recovery while a surviving spouse is alive, although state-specific rules still require attention.
What If She Was Uninsured?
Without insurance, five weeks in the hospital could produce staggering charges. However, you shouldn't assume the original bill is final. Ask about uninsured-patient discounts, financial assistance, and negotiated reductions. Even if the estate owes money, your personal responsibility still depends on state law and any enforceable agreements.
Hospitals May Offer Financial Assistance
Nonprofit hospitals must maintain financial assistance policies to satisfy federal tax requirements. Depending on your wife's financial circumstances and the hospital's rules, her care may qualify for reduced charges or forgiveness. Ask for the application, eligibility requirements, and deadlines, even if bills have already arrived.
Watch For Surprise Bills
Federal protections under the No Surprises Act restrict certain unexpected out-of-network charges, including many emergency services and some treatment at in-network facilities. If an unfamiliar physician or specialist sends a separate bill, investigate whether those protections apply before paying the amount demanded.
 Andrii Iemelianenko, Shutterstock
Review Every Itemized Bill
Request itemized statements showing procedures, medications, supplies, and professional fees. Compare them with insurance explanations of benefits, looking for duplicate charges, incorrect dates, denied claims, or services that appear inconsistent with her treatment. An explanation of benefits isn't itself a bill, and discrepancies deserve investigation.
 Stanislaw Mikulski, Shutterstock
Don't Pay Before Probate
If your wife's estate must go through probate, creditors generally follow state procedures for submitting claims. Don't distribute estate assets or pay large medical bills without understanding creditor priorities and deadlines. Paying one creditor prematurely could create problems if the estate later lacks sufficient money for higher-priority obligations.
 Amnaj Khetsamtip, Shutterstock
Your Home May Be Protected
Losing your wife doesn't automatically mean losing your house to medical creditors. Ownership arrangements, homestead exemptions, marital property rules, and probate protections all matter. A jointly owned home may receive substantial protection, but don't assume it is untouchable without checking your state's specific laws.
What About Joint Accounts?
Money held in joint bank accounts can raise complicated questions. Some accounts pass directly to surviving owners, while state law may still allow certain creditor claims against particular assets. Before transferring large sums or closing accounts, determine which funds legally belong to you and which may face estate obligations.
Collectors Have Strict Rules
Debt collectors may contact you about your deceased wife's bills, but that doesn't prove you're personally responsible. Federal law generally prohibits misleading collection practices and harassment. If someone demands payment, request written debt validation and avoid providing financial information before verifying the collector and the obligation.
You Can Challenge The Debt
If a collector sends a validation notice and you dispute the debt in writing within 30 days, the collector generally must pause collection efforts until providing verification. You can challenge incorrect amounts, mistaken identity, or unsupported claims of personal liability. Keep copies of every communication.
Get Professional Advice Early
If substantial bills remain, consult an estate attorney familiar with your state's medical debt laws. Bring insurance documents, hospital agreements, financial statements, and any collection notices. An attorney can assess personal liability, identify protected assets, and help the estate respond appropriately before expensive mistakes occur.
Don't Assume You Owe
After losing your wife, the last thing you need is pressure to pay bills that may not legally be yours. Verify insurance coverage, review the hospital's claims, understand your state's laws, and protect estate assets. Most importantly, never mistake a payment demand for proof of responsibility.
You May Also Like:
New companies are using AI to successfully appeal their denied health insurance claims.