The Shopping Habit We Forgot
There was a time when Americans could walk into a department store, pick out something expensive, and pay for it over several weeks without borrowing a dime. It was called layaway, and for generations it helped families afford everything from Christmas presents to furniture. So why did this once-popular shopping tradition practically disappear?
How Layaway Actually Worked
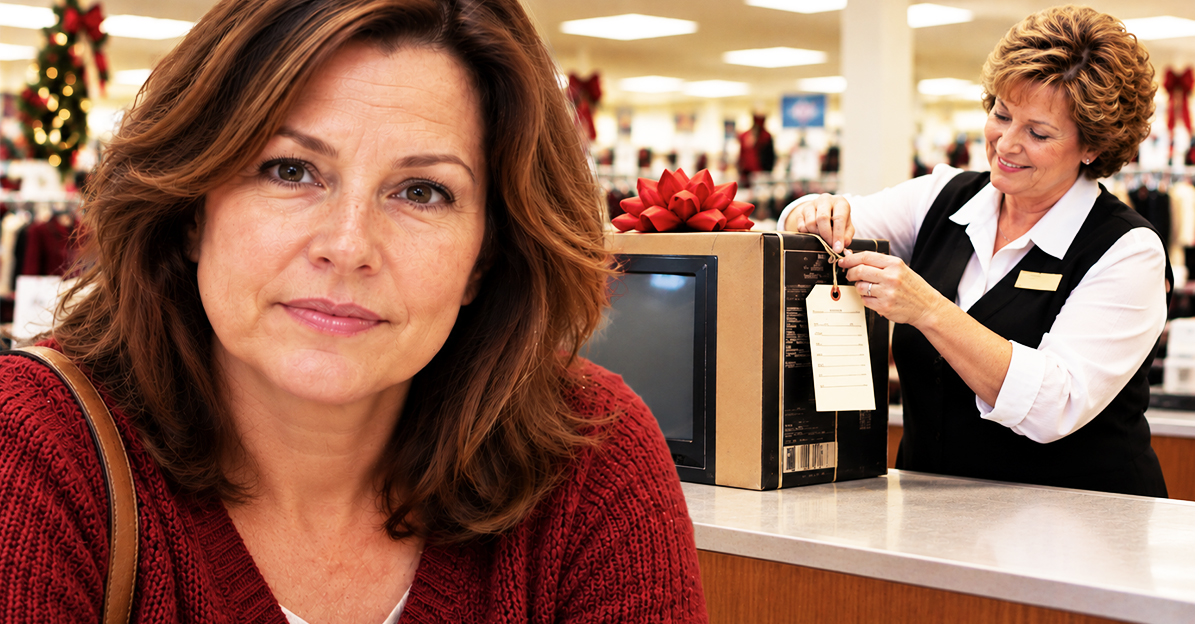
The idea was remarkably simple. You selected an item, paid a small deposit, and the store put it aside while you made regular payments. Once you'd paid the full purchase price, you could take it home. Unlike a credit card, there was no loan and generally no interest. You weren't borrowing money from the store. You were essentially saving toward a purchase, with the merchandise reserved for you.
A Department Store Tradition
Layaway became a familiar part of American shopping during the 20th century, particularly among families who couldn't afford large purchases all at once. Department stores offered payment plans for clothing, appliances, furniture, and other household necessities. During the Great Depression and subsequent decades, setting aside merchandise while customers gradually paid for it offered an alternative to taking on debt. The arrangement also helped retailers secure sales from shoppers with limited cash.
Christmas Made Layaway Famous
For many Americans, layaway was practically synonymous with Christmas shopping. Parents could choose toys and gifts months before December, make payments throughout the fall, and collect everything before the holidays. It helped spread seasonal expenses across several paychecks and kept presents hidden from curious children. Retailers benefited, too, because customers committed to purchases early instead of waiting until the last-minute holiday rush.
Credit Cards Changed Everything
Layaway began losing ground as credit cards became increasingly common during the 1960s and 1970s. Why wait months for a television when you could take it home immediately and pay later? Credit cards offered instant gratification, while layaway required patience. By the 1980s, the old system was steadily declining. Consumers increasingly preferred borrowing against future income to saving up before making a purchase.
Retailers Had Their Own Reasons
Layaway wasn't particularly convenient for stores, either. Retailers needed storage space for merchandise customers hadn't finished paying for, employees to manage accounts, and systems to track payments. Canceled purchases could leave stores holding inventory they might otherwise have sold. Credit cards eliminated many of those headaches because merchants generally received payment promptly while customers dealt with their lenders. The business case for keeping layaway gradually weakened.
Walmart Pulls The Plug
One of layaway's biggest setbacks came in 2006, when Walmart announced it was discontinuing its traditional program. The retailer cited declining demand and rising operating costs. The decision was significant because Walmart had long served budget-conscious shoppers who valued interest-free payment arrangements. Other major chains had already abandoned layaway, but Walmart's withdrawal seemed to confirm that the once-familiar shopping tradition was becoming obsolete.
The Recession Brings It Back
Then the Great Recession changed everything. As unemployment climbed and credit became harder to obtain, Americans rediscovered the appeal of paying gradually without borrowing. Sears reinstated layaway in 2008, while Kmart promoted its existing program. Walmart followed in 2011, bringing back seasonal layaway for selected merchandise. The comeback demonstrated that consumers hadn't necessarily rejected the concept. Many simply preferred more convenient alternatives when money was plentiful.
Buy Now, Pay Later Takes Over
Today, services offering buy-now-pay-later financing have largely taken over layaway's territory. Companies such as Affirm, Klarna, and Afterpay let shoppers divide purchases into installments while receiving their merchandise immediately. The crucial difference is that these arrangements generally involve borrowing. Many short-term plans charge no interest, but late fees, overdraft charges, or longer-term financing costs can still apply. Unlike traditional layaway, the purchase doesn't have to be fully paid for before the customer takes it home.
Layaway Wasn't Always Free
It's worth remembering that traditional layaway wasn't a perfect financial arrangement. Some retailers charged service fees, required minimum deposits, or imposed cancellation penalties. Customers who missed deadlines could lose fees or face restrictions on refunds. And because the merchandise remained at the store, buyers couldn't immediately use something they might genuinely need. Layaway avoided interest-bearing debt, but that didn't automatically make every plan cheaper or more practical than other payment options.
Could Layaway Make A Comeback?
Layaway hasn't disappeared completely, and its basic philosophy remains surprisingly relevant. Saving before spending eliminates interest charges and reduces the temptation to accumulate debts across multiple purchases. But shoppers don't necessarily need a retailer's formal program to achieve the same result. Setting aside money in a dedicated savings account can accomplish something similar, often without fees or restrictions. Perhaps layaway's greatest legacy isn't the payment plan itself, but the once-common belief that waiting until you could afford something was perfectly reasonable.
You May Also Like:
Stores From The 1990s That Families Budgeted Around Before Online Shopping Took Over
The Hidden Costs Of “Buy Now, Pay Later” That Most People Ignore